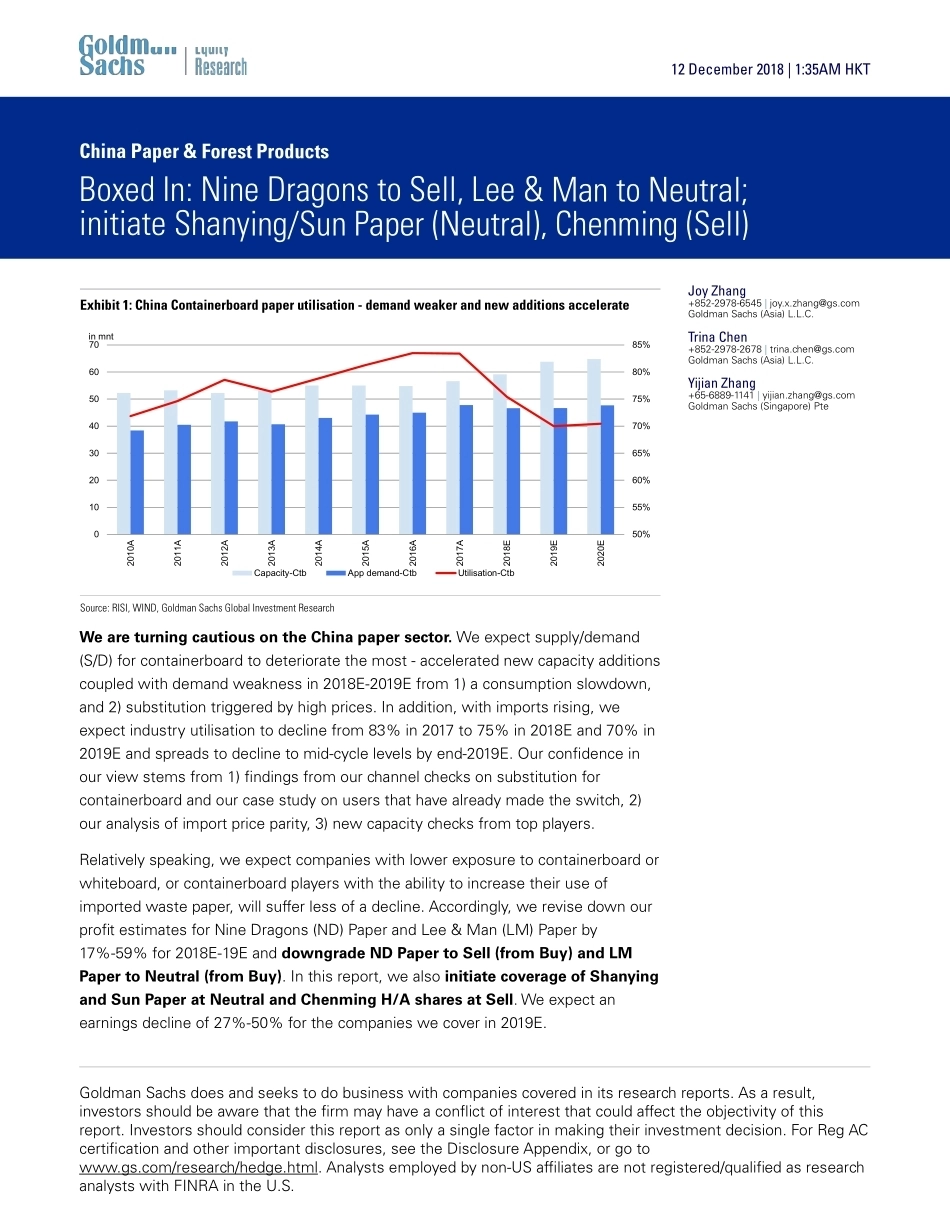
We are turning cautious on the China paper sector. We expect supply/demand (S/D) for containerboard to deteriorate the most - accelerated new capacity additions coupled with demand weakness in 2018E-2019E from 1) a consumption slowdown, and 2) substitution triggered by high prices. In addition, with imports rising, we expect industry utilisation to decline from 83% in 2017 to 75% in 2018E and 70% in 2019E and spreads to decline to mid-cycle levels by end-2019E. Our confidence in our view stems from 1) findings from our channel checks on substitution for containerboard and our case study on users that have already made the switch, 2) our analysis of import price parity, 3) new capacity checks from top players. Relatively speaking, we expect companies with lower exposure to containerboard or whiteboard, or containerboard players with the ability to increase their use of imported waste paper, will suffer less of a decline. Accordingly, we revise down our profit estimates for Nine Dragons (ND) Paper and Lee & Man (LM) Paper by 17%-59% for 2018E-19E and downgrade ND Paper to Sell (from Buy) and LM Paper to Neutral (from Buy). In this report, we also initiate coverage of Shanying and Sun Paper at Neutral and Chenming H/A shares at Sell. We expect an earnings decline of 27%-50% for the companies we cover in 2019E. Exhibit 1: China Containerboard paper utilisation - demand weaker and new additions accelerate 50%55%60%65%70%75%80%85%0102030405060702010A2011A2012A2013A2014A2015A2016A2017A2018E2019E2020ECapacity-CtbApp demand-CtbUtilisation-Ctbin mnt Source: RISI, WIND, Goldman Sachs Global Investment ResearchJoy Zhang +852-2978-6545 | joy.x.zhang@gs.com Goldman Sachs (Asia) L.L.C. Trina Chen +852-2978-2678 | trina.chen@gs.com Goldman Sachs (Asia) L.L.C. Yijian Zhang +65-6889-1141 | yijian.zhang@gs.com Goldman Sachs (Singapore) PteChina Paper & Forest Products Boxed In: Nine Dragons to Sell, Lee & Man to Neutral; initiate Shanying/Sun Paper (Neutral), Chenming (Sell)12 December 2018 | 1:35AM HKTGoldman Sachs does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. For Reg AC certification and other important disclosures, see the Disclosure Appendix, or go to www.gs.com/research/hedge.html. Analysts employed by non-US affiliates are not registered/qualified as research analysts with FINRA in the U.S. Investment summary: Boxed In3 Key charts5 Overall demand weakness likely to persist in 2019E6 Global implications16 Good times over, but where is the bottom?20 Chenming Paper (1812.HK/000488.SZ): on-going investment a headwind given harsh sector conditions; initiate at Sell27 Shanying (600567.SS): Negatives mostly in the price; initiate at Neutral39 Sun Paper (002078.SZ): room for cost improvement; initiate at Neutral52 Nine Dragons Paper (2689.HK): Accelerated new additions in the downcycle; down to Sell63 Lee & Man Paper (2314.HK, Neutral): lower profit decline70 M&A framework77 Disclosure Appendix79 12 December 2018 2Goldman SachsChina Paper & Forest ProductsTable of Contents Investment summary: Boxed In We are turning cautious on the China paper sector. We expect supply/demand (S/D) for containerboard to deteriorate the most, on accelerated new capacity additions coupled with demand weakness in 2018E-2019E from 1) a consumption slowdown, and 2) substitution triggered by high prices. With containerboard accounting for 80% of total packaging paper in China, we expect total packaging paper demand growth to slow to -3.0% yoy for 2018E (10M18 at -3.0%), -0.6% for 2019E and +1.4% for 2020E from +5.2% in 2017. Most downstream demand for packaging paper is from consumer sectors including food, electronics and white goods, which have all reported much slower output growth or negative growth in 2018 YTD versus 2017. We expect this trend to continue in 2019E due to macro factors like slower economic growth and the negative impact from trade wars. In addition, our channel checks on substitution of containerboard boxes, substitution box makers, logistic companies, e-commerce stores and industry companies that use containerboard boxes in their supply chains suggest that substitutions took place around mid-2017. By dividing containerboard paper demand into end-user type—e-commerce (39%), manufacturing supply chain (15%), and direct end-users (46%)—and overlaying this with results from our channel checks, we quantify the substitution impact to total containerboard demand at about 2% in 2018E. Our case study of two industrial companies where a switch to substitute products has been occurring indicates the level of containerboard paper prices at which substitution is triggered to be about Rmb4,100/t for corrugating medium and Rmb4,500/t for linerboard (VAT included). We assume 1% demand...




发表评论取消回复