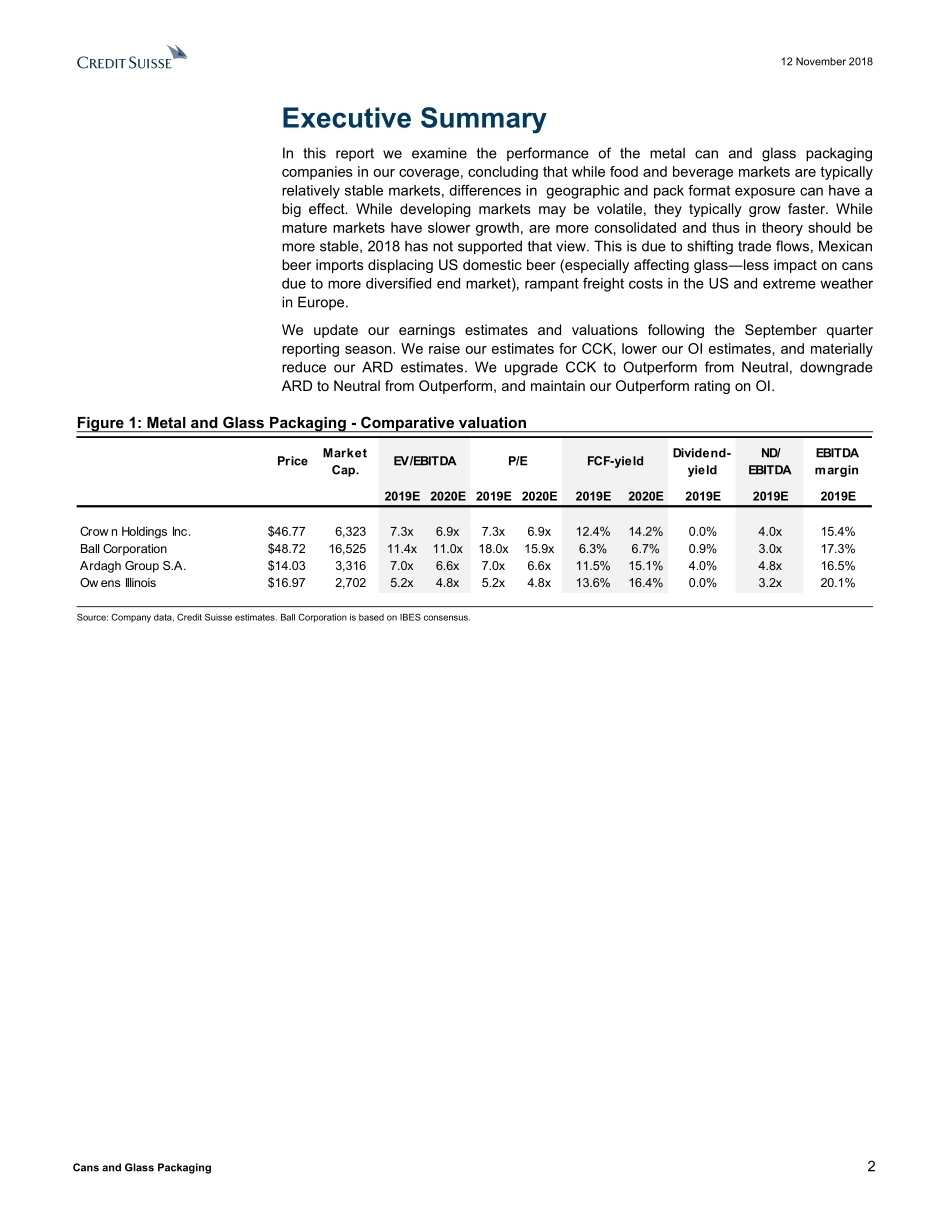
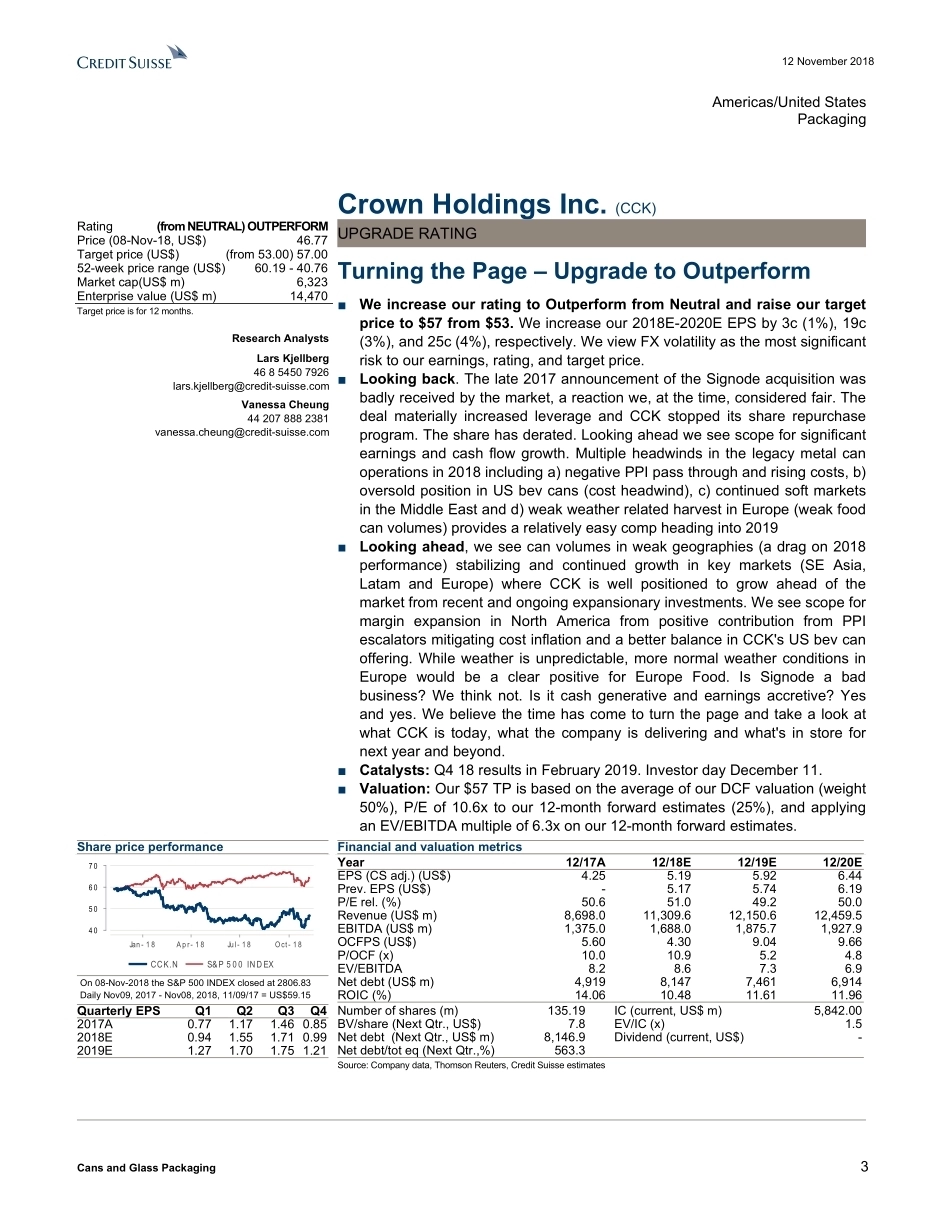
DISCLOSURE APPENDIX AT THE BACK OF THIS REPORT CONTAINS IMPORTANT DISCLOSURES, ANALYST CERTIFICATIONS, LEGAL ENTITY DISCLOSURE AND THE STATUS OF NON-US ANALYSTS. US Disclosure: Credit Suisse does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the Firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. 12 November 2018Americas/United StatesEquity ResearchMetal & Glass Containers Cans and Glass Packaging SECTOR REVIEWResearch AnalystsLars Kjellberg46 8 5450 7926lars.kjellberg@credit-suisse.comVanessa Cheung44 207 888 2381vanessa.cheung@credit-suisse.comGeographic Diversity Is Good■Geographical Diversification Pays Off. While food and beverage volumes show relatively steady growth globally, performance in different geographies can vary materially. The earnings impact from differences in geographical exposure and pack format can have a great impact on earnings for individual companies. Heading into 2018 we had a view that exposure to mature, consolidated markets, should be good for earnings stability and predictability. It hasn't worked out that way for glass and metal can companies. ■CCK – upgrade to Outperform (from Neutral), target raised to $57 from $53. CCK has derated materially since the announcement of the Signode acquisition late 2017. Approaching the anniversary of the deal announcement, we believe it is time to take a look at what CCK is today, what the company is delivering and what's in store for next year and beyond. We like what we see. CCK's bev can (52% of revenues) volumes are growing at 4%, double the pace of global #1 BLL. Signode (20% of revenues) is delivering the expected high cash conversion (92%, YTD) and CCK is on target to delever by 0.5x/year. Food (in Europe) is experiencing a challenging year due to weather, offset by strong performance elsewhere. Geographic and product diversification and exposure to growth markets have seen CCK deliver progressive operating income in 14 of the past 15 years (2012 only down year). We see that strong track record continuing in the foreseeable future.■ARD – downgrade to Neutral from Outperform, target price cut to $15.3 from $21.0. We downgrade to Neutral from Outperform, acknowledging that our investment case for ARD was based on stable and predictable earnings and deleveraging. Following significant guidance cuts in 2018, the premise of predictability now looks challenging and, as a result of lowered EBITDA outlook, leverage reduction has fallen at least two years behind target. We see continued high leverage and slow deleveraging adding risk to the equity investment and we believe is likely to delay plans for increased free float by swapping debt for equity for HOLDco owners. ■OI – maintain Outperform, target price cut to $24 from $32. Although the stock price reflects expectations of a structurally declining business, we see a credible path for further performance improvement. O-I is set to deliver a 2015-18E EPS CAGR of 11%. We expect 2018E-2020E EPS CAGR of 13% from improved volumes and costs and reversal of 2018 temporary headwinds.12 November 2018Cans and Glass Packaging2Executive SummaryIn this report we examine the performance of the metal can and glass packaging companies in our coverage, concluding that while food and beverage markets are typically relatively stable markets, differences in geographic and pack format exposure can have a big effect. While developing markets may be volatile, they typically grow faster. While mature markets have slower growth, are more consolidated and thus in theory should be more stable, 2018 has not supported that view. This is due to shifting trade flows, Mexican beer imports displacing US domestic beer (especially affecting glass―less impact on cans due to more diversified end market), rampant freight costs in the US and extreme weather in Europe. We update our earnings estimates and valuations following the September quarter reporting season. We raise our estimates for CCK, lower our OI estimates, and materially reduce our ARD estimates. We upgrade CCK to Outperform from Neutral, downgrade ARD to Neutral from Outperform, and maintain our Outperform rating on OI. Figure 1: Metal and Glass Packaging - Comparative valuationPriceMarketCap.Dividend-yieldND/EBITDAEBITDAmargin2019E 2020E 2019E 2020E2019E2020E2019E2019E2019ECrow n Holdings Inc.$46.776,3237.3x6.9x7.3x6.9x12.4%14.2%0.0%4.0x15.4%Ball Corporation$48.7216,52511.4x11.0x18.0x15.9x6.3%6.7%0.9%3.0x17.3%Ardagh Group S.A.$14.033,3167.0x6.6x7.0x6.6x11.5%15.1%4.0%4.8x16.5%Ow ens Illinois$16.972,7025.2x4.8x5.2x4.8x13.6%16.4%0.0%3.2x20.1%FCF-yieldEV/EBITDAP/ESource: Company data, Credit Suisse estimates. Ball Corporation is based on IBES consensus.12 November 2018Cans and Glass Packaging3Americas/United StatesPackaging Crown Holdings Inc. (CCK)UPGRADE RATINGRati...




发表评论取消回复