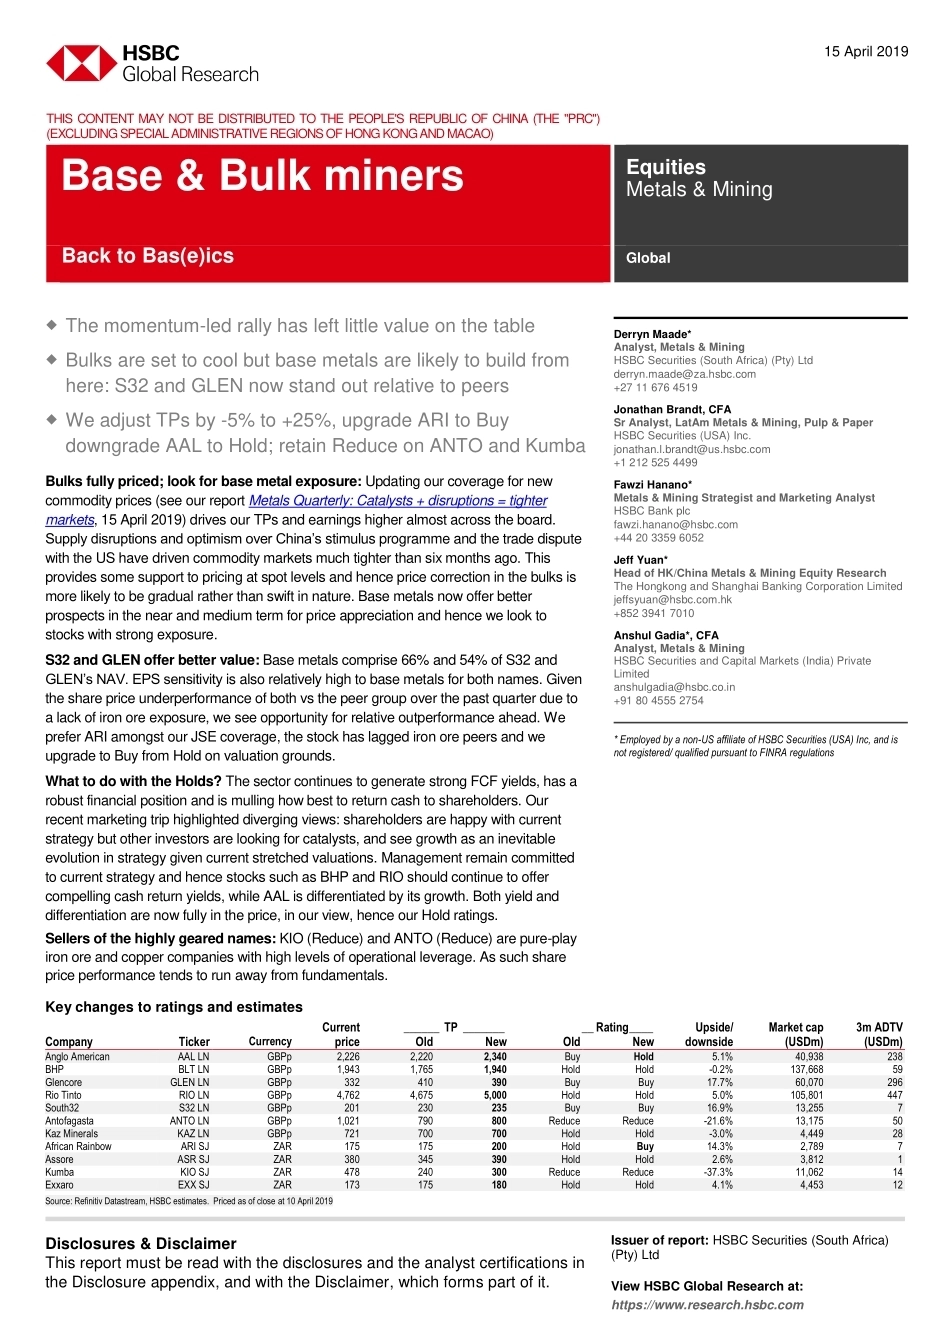
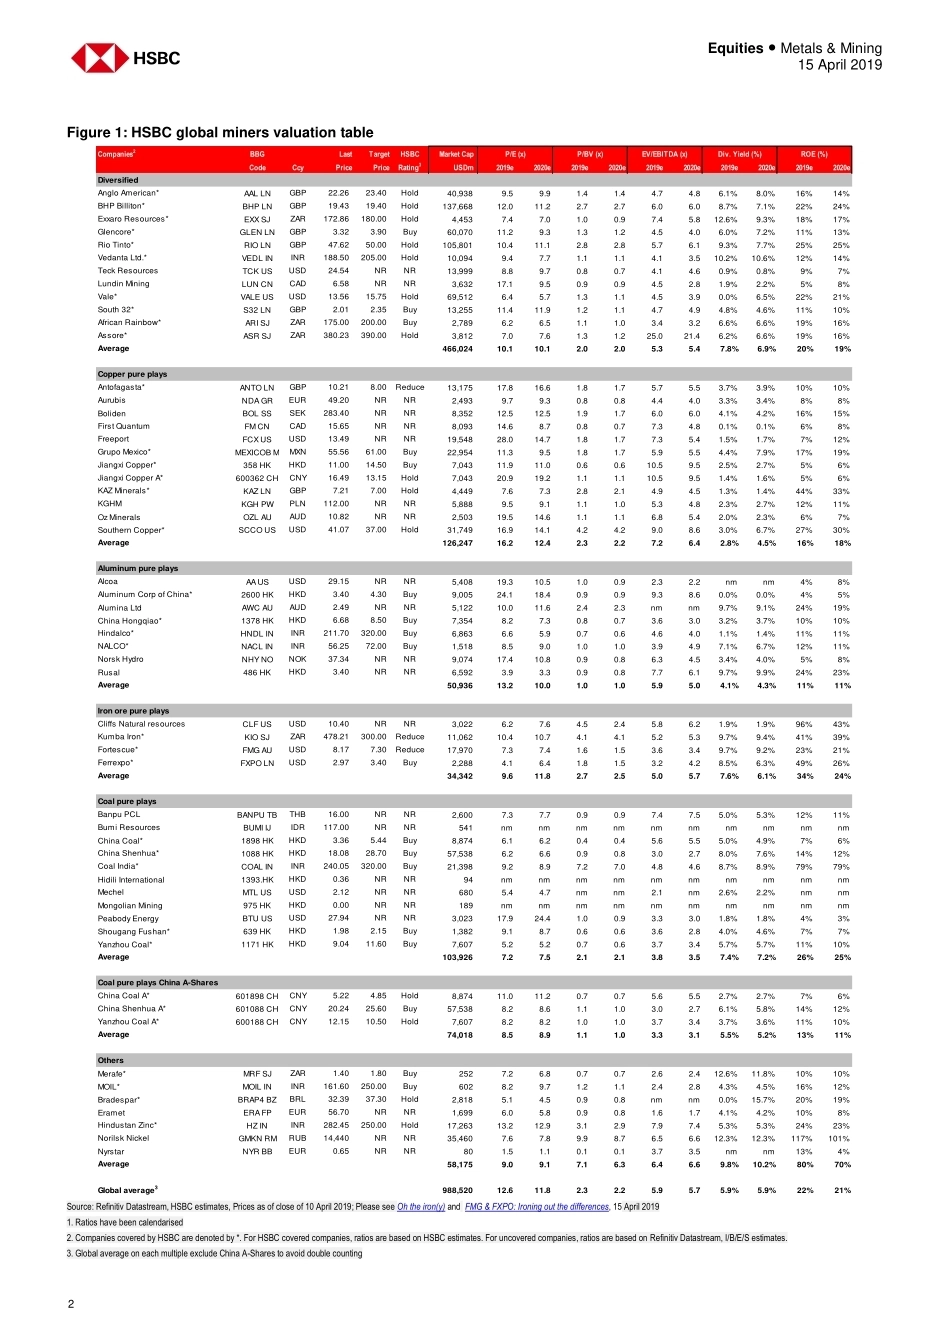
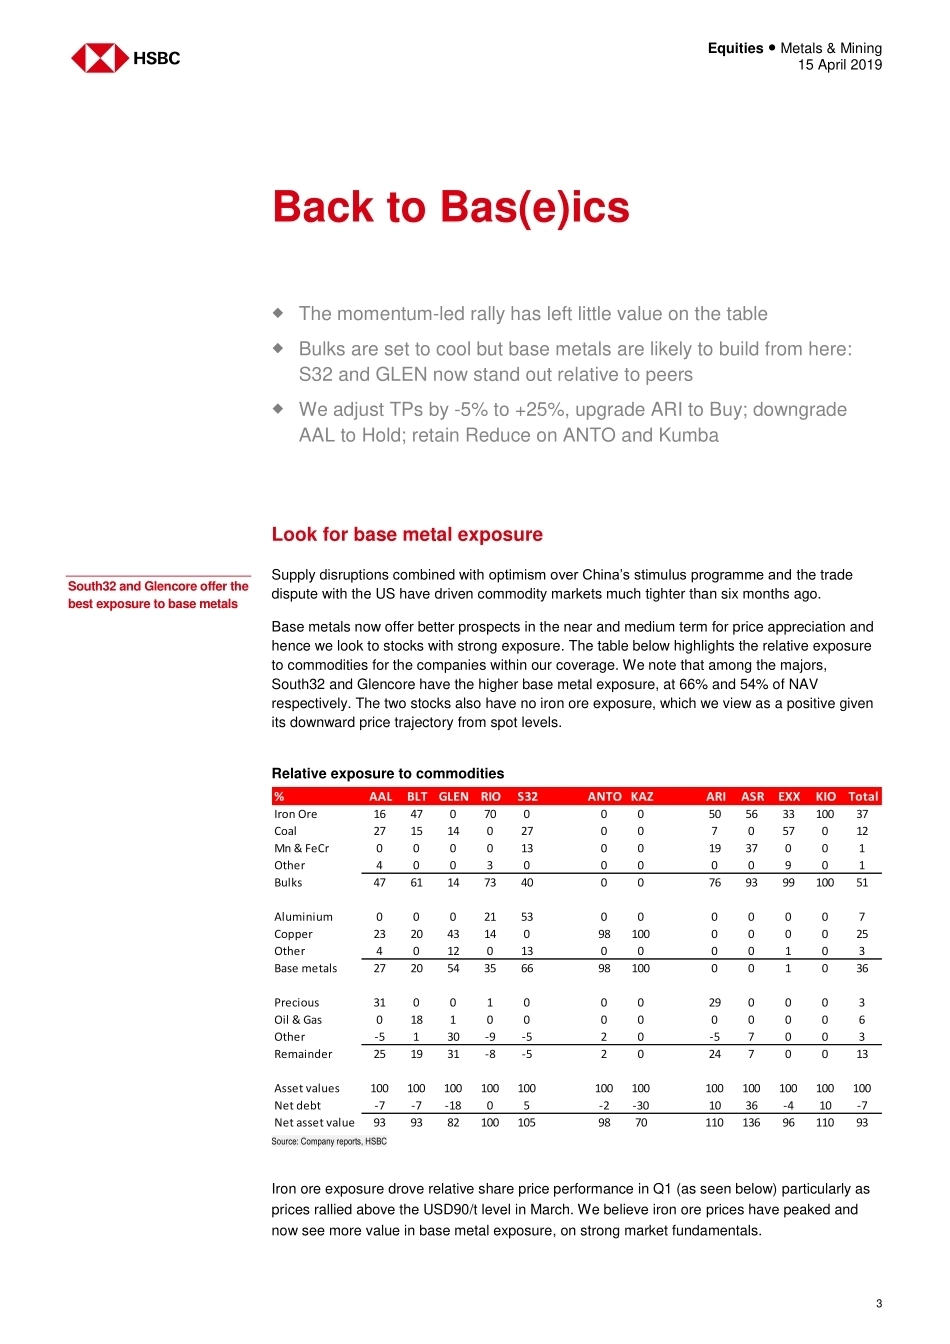
Disclosures & Disclaimer This report must be read with the disclosures and the analyst certifications in the Disclosure appendix, and with the Disclaimer, which forms part of it. Issuer of report: HSBC Securities (South Africa) (Pty) Ltd View HSBC Global Research at: https://www.research.hsbc.com THIS CONTENT MAY NOT BE DISTRIBUTED TO THE PEOPLE'S REPUBLIC OF CHINA (THE "PRC") (EXCLUDING SPECIAL ADMINISTRATIVE REGIONS OF HONG KONG AND MACAO) The momentum-led rally has left little value on the table Bulks are set to cool but base metals are likely to build from here: S32 and GLEN now stand out relative to peers We adjust TPs by -5% to +25%, upgrade ARI to Buy downgrade AAL to Hold; retain Reduce on ANTO and Kumba Bulks fully priced; look for base metal exposure: Updating our coverage for new commodity prices (see our report Metals Quarterly: Catalysts + disruptions = tighter markets, 15 April 2019) drives our TPs and earnings higher almost across the board. Supply disruptions and optimism over China’s stimulus programme and the trade dispute with the US have driven commodity markets much tighter than six months ago. This provides some support to pricing at spot levels and hence price correction in the bulks is more likely to be gradual rather than swift in nature. Base metals now offer better prospects in the near and medium term for price appreciation and hence we look to stocks with strong exposure. S32 and GLEN offer better value: Base metals comprise 66% and 54% of S32 and GLEN’s NAV. EPS sensitivity is also relatively high to base metals for both names. Given the share price underperformance of both vs the peer group over the past quarter due to a lack of iron ore exposure, we see opportunity for relative outperformance ahead. We prefer ARI amongst our JSE coverage, the stock has lagged iron ore peers and we upgrade to Buy from Hold on valuation grounds. What to do with the Holds? The sector continues to generate strong FCF yields, has a robust financial position and is mulling how best to return cash to shareholders. Our recent marketing trip highlighted diverging views: shareholders are happy with current strategy but other investors are looking for catalysts, and see growth as an inevitable evolution in strategy given current stretched valuations. Management remain committed to current strategy and hence stocks such as BHP and RIO should continue to offer compelling cash return yields, while AAL is differentiated by its growth. Both yield and differentiation are now fully in the price, in our view, hence our Hold ratings. Sellers of the highly geared names: KIO (Reduce) and ANTO (Reduce) are pure-play iron ore and copper companies with high levels of operational leverage. As such share price performance tends to run away from fundamentals. 15 April 2019 Derryn Maade* Analyst, Metals & Mining HSBC Securities (South Africa) (Pty) Ltd derryn.maade@za.hsbc.com +27 11 676 4519 Jonathan Brandt, CFA Sr Analyst, LatAm Metals & Mining, Pulp & Paper HSBC Securities (USA) Inc. jonathan.l.brandt@us.hsbc.com +1 212 525 4499 Fawzi Hanano* Metals & Mining Strategist and Marketing Analyst HSBC Bank plc fawzi.hanano@hsbc.com +44 20 3359 6052 Jeff Yuan* Head of HK/China Metals & Mining Equity Research The Hongkong and Shanghai Banking Corporation Limited jeffsyuan@hsbc.com.hk +852 3941 7010 Anshul Gadia*, CFA Analyst, Metals & Mining HSBC Securities and Capital Markets (India) Private Limited anshulgadia@hsbc.co.in +91 80 4555 2754 * Employed by a non-US affiliate of HSBC Securities (USA) Inc, and is not registered/ qualified pursuant to FINRA regulations Base & Bulk miners Equities Metals & Mining Global Key changes to ratings and estimates Current ______ TP _______ __ Rating ____ Upside/ Market cap 3m ADTV Company Ticker Currency price Old New Old New downside (USDm) (USDm) Anglo American AAL LN GBPp 2,226 2,220 2,340 Buy Hold 5.1% 40,938 238 BHP BLT LN GBPp 1,943 1,765 1,940 Hold Hold -0.2% 137,668 59 Glencore GLEN LN GBPp 332 410 390 Buy Buy 17.7% 60,070 296 Rio Tinto RIO LN GBPp 4,762 4,675 5,000 Hold Hold 5.0% 105,801 447 South32 S32 LN GBPp 201 230 235 Buy Buy 16.9% 13,255 7 Antofagasta ANTO LN GBPp 1,021 790 800 Reduce Reduce -21.6% 13,175 50 Kaz Minerals KAZ LN GBPp 721 700 700 Hold Hold -3.0% 4,449 28 African Rainbow ARI SJ ZAR 175 175 200 Hold Buy 14.3% 2,789 7 Assore ASR SJ ZAR 380 345 390 Hold Hold 2.6% 3,812 1 Kumba KIO SJ ZAR 478 240 300 Reduce Reduce -37.3% 11,062 14 Exxaro EXX SJ ZAR 173 175 180 Hold Hold 4.1% 4,453 12 Source: Refinitiv Datastream, HSBC estimates. Priced as of close at 10 April 2019 Back to Bas(e)ics Equities ● Metals & Mining 15 April 2019 2 Figure 1: HSBC global miners valuation table Source: Refinitiv Datastream, HSBC estimates, Prices as of close of 10 April 2019; Please see Oh the iron(y) and FMG & FXPO: Ironing out the differences, 15 April 2019 1. Ratios have been calendarised 2. Companies covered by HSBC are denoted by *. For HSBC covered companies, ratios are based on H...




发表评论取消回复