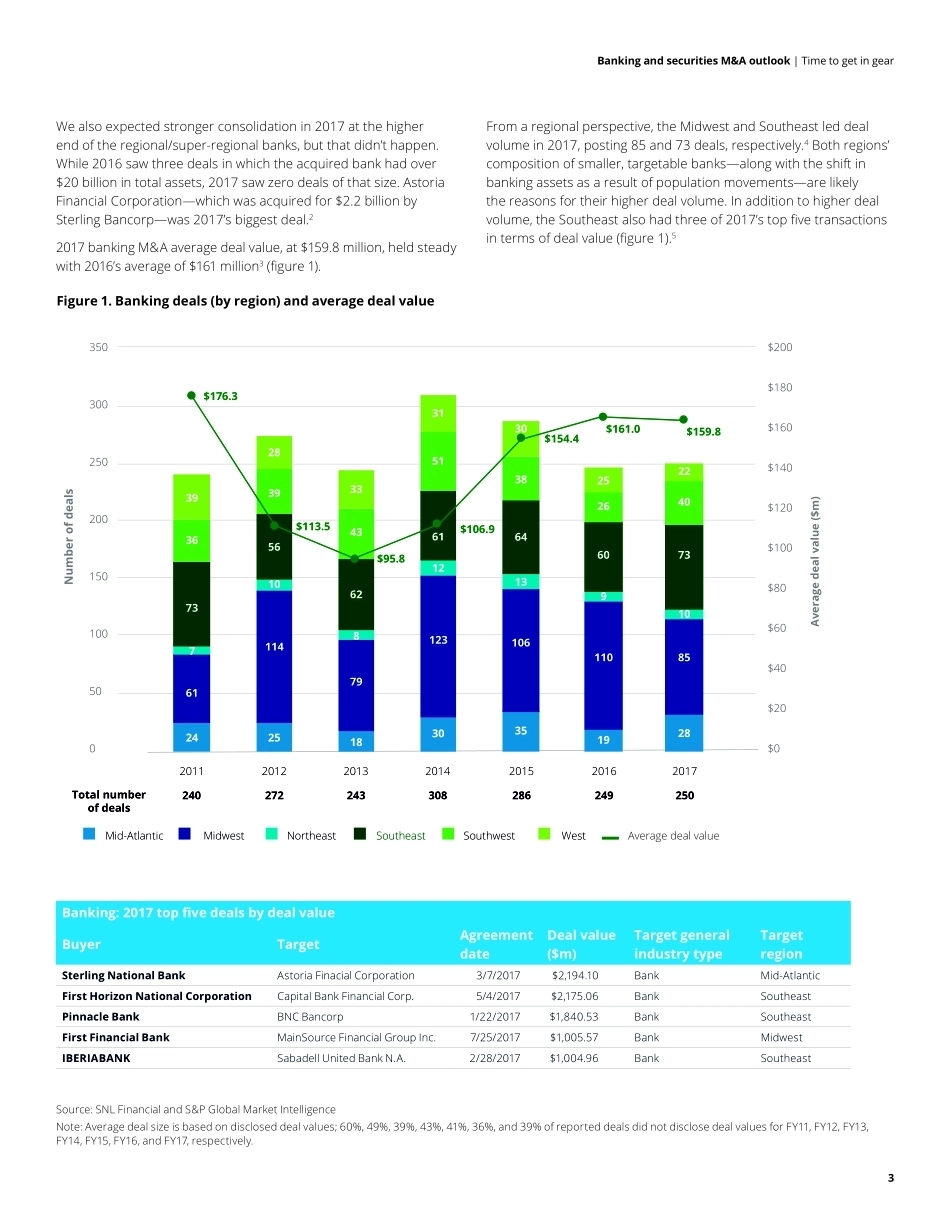
Banking and securities M&A outlook Time to get in gearBanking and securities M&A outlook | Time to get in gear2IntroductionEntering 2017, there seemed to be positive momentum for increased deal-making in banking, specialty finance, investment management and securities, and financial technology (fintech). Macro-level catalysts included an improving economy, sustained stock market rally, steadily rising interest rates, pro-business election results, and the expected easing of financial services industry (FSI) regulations. Add organization-level triggers of continuing margin pressure, ample cash reserves, and the need for digital capabilities, and the combination of factors warranted an optimistic outlook. Yet, similar to 2016, the M&A engine essentially remained in neutral: Deal sizes increased in 2017, but there were fewer transactions overall.Entering 2018, we continue to be optimistic about banking and securities M&A. Virtually all of the above drivers remain in place and are being bolstered by increasing regulatory clarity and US tax reform legislation—both of which will benefit bottom lines and add to capital war chests. We do, however, anticipate that organizations will need time to digest the implications of new legislation and may delay deal-making to the second half of the year.BankingWith 250 announced deals as of December 19, banking M&A volume in 2017 was almost a carbon copy of the prior year’s 249 transactions (figure 1).1 2017’s total was a bit disappointing, as the year began with numerous natural drivers for consolidation—an improving economy, sustained stock market rally, ample capital levels, and expectations for a loosening of banking regulations under the new Trump administration. However, delayed regulatory leadership changes, prolonged uncertainty around tax and health care reform, and a late-2016 run-up in stock prices (especially for small banks) let the air out of M&A’s tires somewhat in 2017. After several years of false starts, will banking and securities merger and acquisition (M&A) activity get in gear in 2018?Banking and securities M&A outlook | Time to get in gear3We also expected stronger consolidation in 2017 at the higher end of the regional/super-regional banks, but that didn’t happen. While 2016 saw three deals in which the acquired bank had over $20 billion in total assets, 2017 saw zero deals of that size. Astoria Financial Corporation—which was acquired for $2.2 billion by Sterling Bancorp—was 2017’s biggest deal.22017 banking M&A average deal value, at $159.8 million, held steady with 2016’s average of $161 million3 (figure 1). Banking: 2017 top five deals by deal valueBuyerTargetAgreement dateDeal value ($m)Target general industry typeTarget regionSterling National BankAstoria Finacial Corporation3/7/2017$2,194.10 BankMid-AtlanticFirst Horizon National CorporationCapital Bank Financial Corp.5/4/2017$2,175.06 BankSoutheastPinnacle BankBNC Bancorp1/22/2017$1,840.53 Bank SoutheastFirst Financial BankMainSource Financial Group Inc.7/25/2017$1,005.57 Bank Midwest IBERIABANKSabadell United Bank N.A.2/28/2017$1,004.96 Bank Southeast M&A Activity - Banking240272243308286249Total number of deals24617733639$176.3$113.5$95.8$106.9$154.4$161.039285610114798624333315161121233035106136438302526609110192518Mid-AtlanticMidwestNortheastSoutheastSouthwestWestAverage deal value250$159.8224073108528 2011 2012 2013 2014 2015 2016 2017050100150350300250200$0$20$40$60$200$180$140$100$160$120$80Number of dealsAverage deal value ($m)Figure 1. Banking deals (by region) and average deal valueSource: SNL Financial and S&P Global Market IntelligenceNote: Average deal size is based on disclosed deal values; 60%, 49%, 39%, 43%, 41%, 36%, and 39% of reported deals did not disclose deal values for FY11, FY12, FY13, FY14, FY15, FY16, and FY17, respectively.From a regional perspective, the Midwest and Southeast led deal volume in 2017, posting 85 and 73 deals, respectively.4 Both regions’ composition of smaller, targetable banks—along with the shift in banking assets as a result of population movements—are likely the reasons for their higher deal volume. In addition to higher deal volume, the Southeast also had three of 2017’s top five transactions in terms of deal value (figure 1).54Continuing a multiyear trend, the majority of banking M&A deals in 2017 occurred at the small bank level, with most acquisition targets holding less than $1 billion in assets (figure 2). Pressured by prolonged, relatively low interest rates and burdensome regulatory compliance and technology upgrades that are driving high operating costs, many small banks are choosing to consolidate or be purchased rather than go it alone.203256258218274232420320< $1B assets$1B – $10B assets>$10B assets050100150300250200 2013 2014 2015 2016214342 2017Number of targetsFigure 2. Bank transactions by asset sizeTargets by asset sizeSource: SNL Financial and S&P Global Market Intelligence Banking and securities M&A outlook | Time to get in gear...




发表评论取消回复