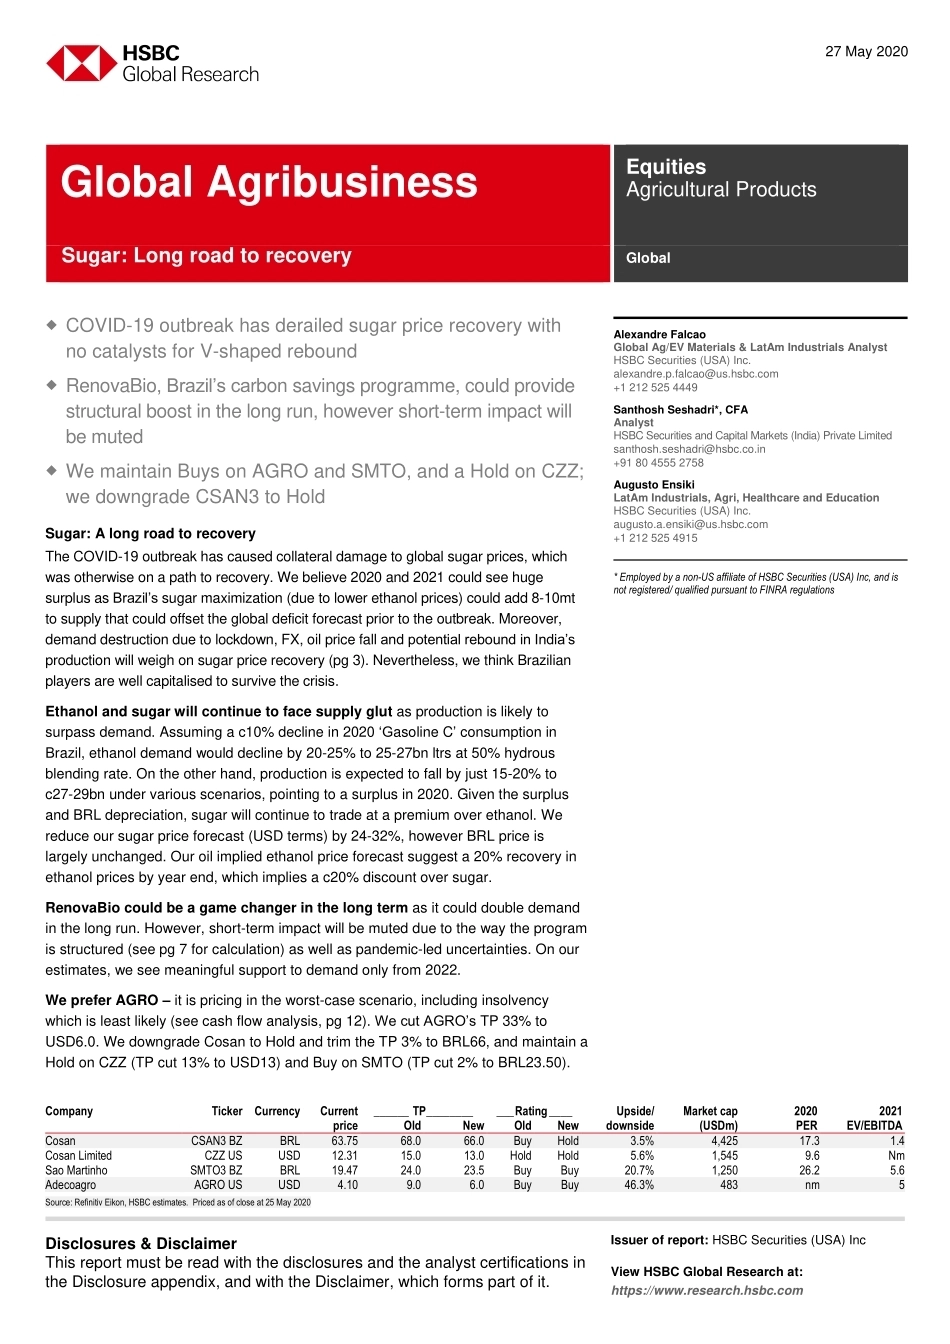
Disclosures & Disclaimer This report must be read with the disclosures and the analyst certifications in the Disclosure appendix, and with the Disclaimer, which forms part of it. Issuer of report: HSBC Securities (USA) Inc View HSBC Global Research at: https://www.research.hsbc.com COVID-19 outbreak has derailed sugar price recovery with no catalysts for V-shaped rebound RenovaBio, Brazil’s carbon savings programme, could provide structural boost in the long run, however short-term impact will be muted We maintain Buys on AGRO and SMTO, and a Hold on CZZ; we downgrade CSAN3 to Hold Sugar: A long road to recovery The COVID-19 outbreak has caused collateral damage to global sugar prices, which was otherwise on a path to recovery. We believe 2020 and 2021 could see huge surplus as Brazil’s sugar maximization (due to lower ethanol prices) could add 8-10mt to supply that could offset the global deficit forecast prior to the outbreak. Moreover, demand destruction due to lockdown, FX, oil price fall and potential rebound in India’s production will weigh on sugar price recovery (pg 3). Nevertheless, we think Brazilian players are well capitalised to survive the crisis. Ethanol and sugar will continue to face supply glut as production is likely to surpass demand. Assuming a c10% decline in 2020 ‘Gasoline C’ consumption in Brazil, ethanol demand would decline by 20-25% to 25-27bn ltrs at 50% hydrous blending rate. On the other hand, production is expected to fall by just 15-20% to c27-29bn under various scenarios, pointing to a surplus in 2020. Given the surplus and BRL depreciation, sugar will continue to trade at a premium over ethanol. We reduce our sugar price forecast (USD terms) by 24-32%, however BRL price is largely unchanged. Our oil implied ethanol price forecast suggest a 20% recovery in ethanol prices by year end, which implies a c20% discount over sugar. RenovaBio could be a game changer in the long term as it could double demand in the long run. However, short-term impact will be muted due to the way the program is structured (see pg 7 for calculation) as well as pandemic-led uncertainties. On our estimates, we see meaningful support to demand only from 2022. We prefer AGRO – it is pricing in the worst-case scenario, including insolvency which is least likely (see cash flow analysis, pg 12). We cut AGRO’s TP 33% to USD6.0. We downgrade Cosan to Hold and trim the TP 3% to BRL66, and maintain a Hold on CZZ (TP cut 13% to USD13) and Buy on SMTO (TP cut 2% to BRL23.50). Company Ticker Currency Current ______ TP ________ ___ Rating ____ Upside/ Market cap 2020 2021 price Old New Old New downside (USDm) PER EV/EBITDA Cosan CSAN3 BZ BRL 63.75 68.0 66.0 Buy Hold 3.5% 4,425 17.3 1.4 Cosan Limited CZZ US USD 12.31 15.0 13.0 Hold Hold 5.6% 1,545 9.6 Nm Sao Martinho SMTO3 BZ BRL 19.47 24.0 23.5 Buy Buy 20.7% 1,250 26.2 5.6 Adecoagro AGRO US USD 4.10 9.0 6.0 Buy Buy 46.3% 483 nm 5 Source: Refinitiv Eikon, HSBC estimates. Priced as of close at 25 May 2020 27 May 2020 Alexandre Falcao Global Ag/EV Materials & LatAm Industrials Analyst HSBC Securities (USA) Inc. alexandre.p.falcao@us.hsbc.com +1 212 525 4449 Santhosh Seshadri*, CFA Analyst HSBC Securities and Capital Markets (India) Private Limited santhosh.seshadri@hsbc.co.in +91 80 4555 2758 Augusto Ensiki LatAm Industrials, Agri, Healthcare and Education HSBC Securities (USA) Inc. augusto.a.ensiki@us.hsbc.com +1 212 525 4915 * Employed by a non-US affiliate of HSBC Securities (USA) Inc, and is not registered/ qualified pursuant to FINRA regulations Global Agribusiness Equities Agricultural Products Global Sugar: Long road to recovery Equities ● Agricultural Products 27 May 2020 2 Sugar and Ethanol 3 Supply/demand dynamics 3 RenovaBio 7 RenovaBio could be a game changer in the long run 7 Operational challenges 8 Impact on companies 9 Ethanol supply/demand impact 9 New capacity additions in Brazil 9 Company section 10 Valuation and risks 13 Disclosure appendix 18 Disclaimer 23 Contents 3 Equities ● Agricultural Products 27 May 2020 Supply/demand dynamics COVID-19 has derailed sugar price recovery COVID-19 has caused collateral damage to the global sugar industry which was otherwise on a path to recovery. Sugar prices declined drastically mainly due to the collapse in oil price (and ethanol) demand, with April ethanol demand in Brazil declining 50% yoy. As a result, sugar is trading at a premium over ethanol for the first time in the last few years. This will incentivise Brazil to maximize sugar production that could churn out an additional 8-10mt of sugar (c12mt at max capacity of 50% sugar 50% ethanol). The additional sugar production from Brazil will be more than enough to offset 8-10mt of deficit forecast prior to the COVID-19 outbreak. As a large portion of sugar is used in beverages and confectionaries, sugar demand could be affected by production shutdowns. The quantum of impact is less clear at this point, however, some industry estimates suggest as much ...




发表评论取消回复