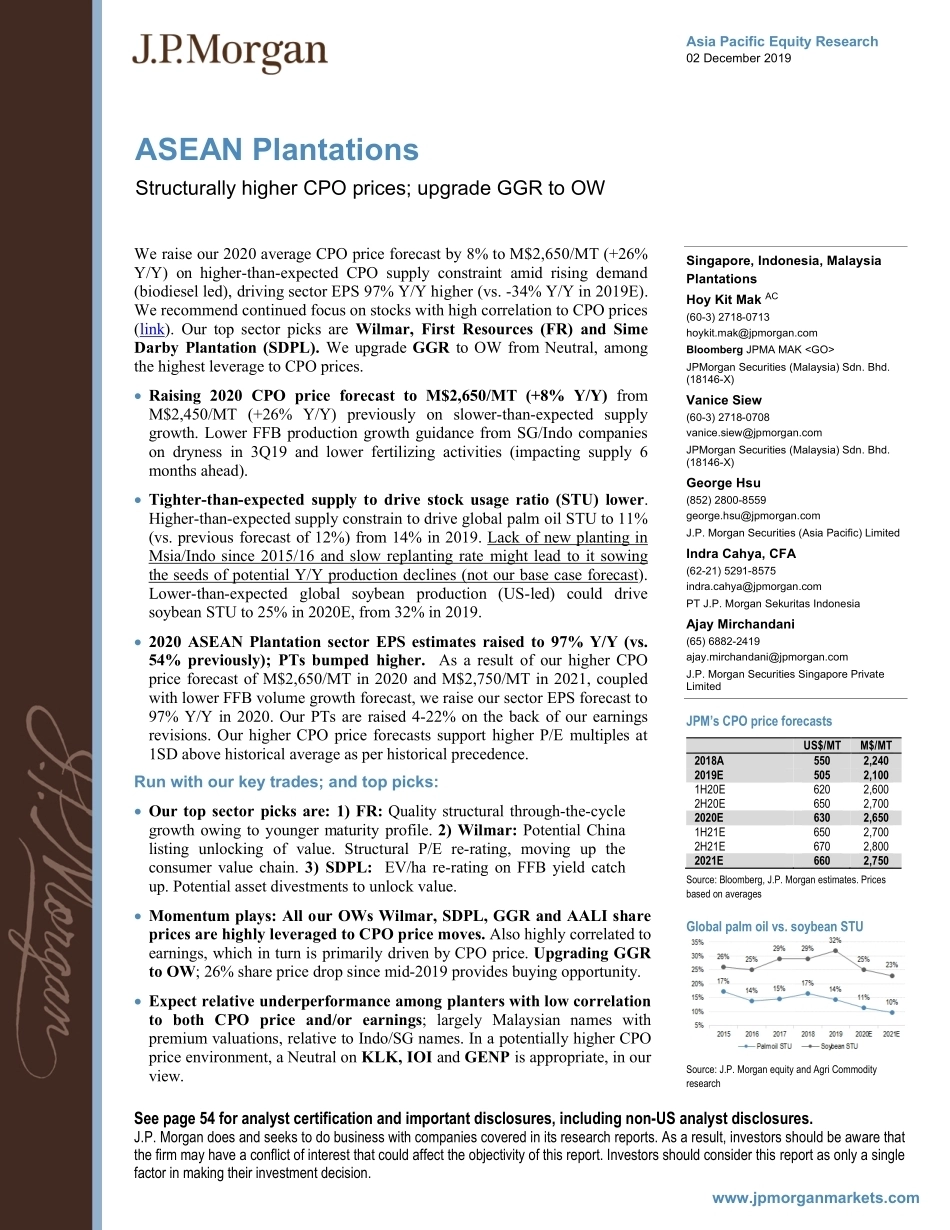
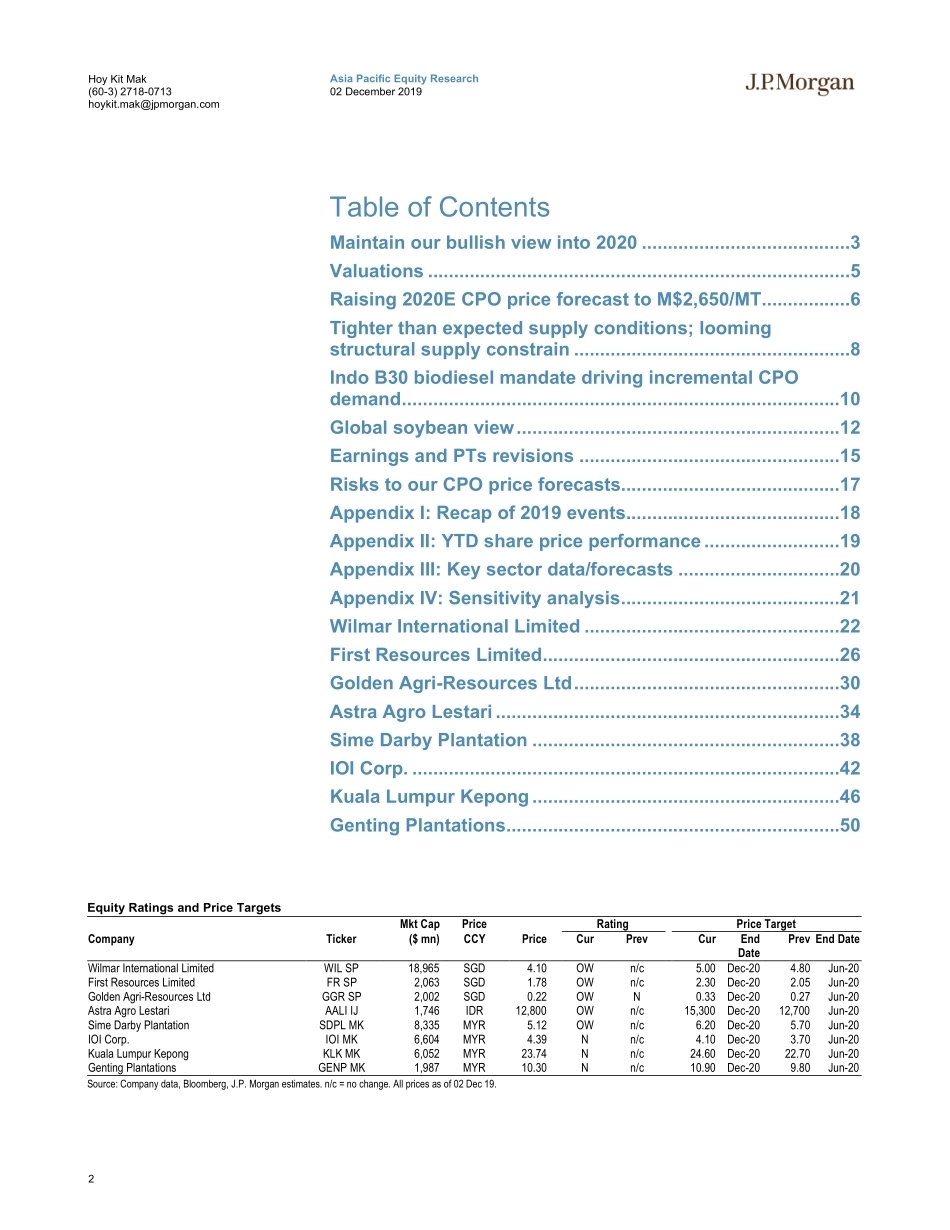
www.jpmorganmarkets.comAsia Pacific Equity Research02 December 2019ASEAN PlantationsStructurally higher CPO prices; upgrade GGR to OWSingapore, Indonesia, MalaysiaPlantationsHoy Kit Mak AC(60-3) 2718-0713hoykit.mak@jpmorgan.comBloomberg JPMA MAK JPMorgan Securities (Malaysia) Sdn. Bhd. (18146-X)Vanice Siew(60-3) 2718-0708vanice.siew@jpmorgan.comJPMorgan Securities (Malaysia) Sdn. Bhd. (18146-X)George Hsu(852) 2800-8559george.hsu@jpmorgan.comJ.P. Morgan Securities (Asia Pacific) LimitedIndra Cahya, CFA(62-21) 5291-8575indra.cahya@jpmorgan.comPT J.P. Morgan Sekuritas IndonesiaAjay Mirchandani(65) 6882-2419ajay.mirchandani@jpmorgan.comJ.P. Morgan Securities Singapore Private LimitedSee page 54 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.We raise our 2020 average CPO price forecast by 8% to M$2,650/MT (+26% Y/Y) on higher-than-expected CPO supply constraint amid rising demand (biodiesel led), driving sector EPS 97% Y/Y higher (vs. -34% Y/Y in 2019E). We recommend continued focus on stocks with high correlation to CPO prices(link). Our top sector picks are Wilmar, First Resources (FR) and Sime Darby Plantation (SDPL). We upgrade GGR to OW from Neutral, among the highest leverage to CPO prices. Raising 2020 CPO price forecast to M$2,650/MT (+8% Y/Y) from M$2,450/MT (+26% Y/Y) previously on slower-than-expected supply growth. Lower FFB production growth guidance from SG/Indo companieson dryness in 3Q19 and lower fertilizing activities (impacting supply 6 months ahead). Tighter-than-expected supply to drive stock usage ratio (STU) lower. Higher-than-expected supply constrain to drive global palm oil STU to 11% (vs. previous forecast of 12%) from 14% in 2019. Lack of new planting in Msia/Indo since 2015/16 and slow replanting rate might lead to it sowing the seeds of potential Y/Y production declines (not our base case forecast). Lower-than-expected global soybean production (US-led) could drive soybean STU to 25% in 2020E, from 32% in 2019. 2020 ASEAN Plantation sector EPS estimates raised to 97% Y/Y (vs. 54% previously); PTs bumped higher. As a result of our higher CPO price forecast of M$2,650/MT in 2020 and M$2,750/MT in 2021, coupled with lower FFB volume growth forecast, we raise our sector EPS forecast to 97% Y/Y in 2020. Our PTs are raised 4-22% on the back of our earnings revisions. Our higher CPO price forecasts support higher P/E multiples at 1SD above historical average as per historical precedence. Run with our key trades; and top picks: Our top sector picks are: 1) FR: Quality structural through-the-cycle growth owing to younger maturity profile. 2) Wilmar: Potential China listing unlocking of value. Structural P/E re-rating, moving up the consumer value chain. 3) SDPL: EV/ha re-rating on FFB yield catch up. Potential asset divestments to unlock value. Momentum plays: All our OWs Wilmar, SDPL, GGR and AALI share prices are highly leveraged to CPO price moves. Also highly correlated to earnings, which in turn is primarily driven by CPO price. Upgrading GGR to OW; 26% share price drop since mid-2019 provides buying opportunity. Expect relative underperformance among planters with low correlation to both CPO price and/or earnings; largely Malaysian names with premium valuations, relative to Indo/SG names. In a potentially higher CPO price environment, a Neutral on KLK, IOI and GENP is appropriate, in our view.JPM’s CPO price forecastsUS$/MTM$/MT2018A5502,2402019E5052,1001H20E6202,6002H20E6502,7002020E6302,6501H21E6502,7002H21E6702,8002021E6602,750Source: Bloomberg, J.P. Morgan estimates. Prices based on averagesGlobal palm oil vs. soybean STU Source: J.P. Morgan equity and Agri Commodity research2Asia Pacific Equity Research02 December 2019Hoy Kit Mak(60-3) 2718-0713hoykit.mak@jpmorgan.comTable of ContentsMaintain our bullish view into 2020 ........................................3Valuations .................................................................................5Raising 2020E CPO price forecast to M$2,650/MT.................6Tighter than expected supply conditions; looming structural supply constrain .....................................................8Indo B30 biodiesel mandate driving incremental CPO demand....................................................................................10Global soybean view..............................................................12Earnings and PTs revisions ..................................................15Risks to our CPO price forecasts..........................................17Appendix I: Recap of 2019 events.........................................18Appendix II: YTD sha...




发表评论取消回复