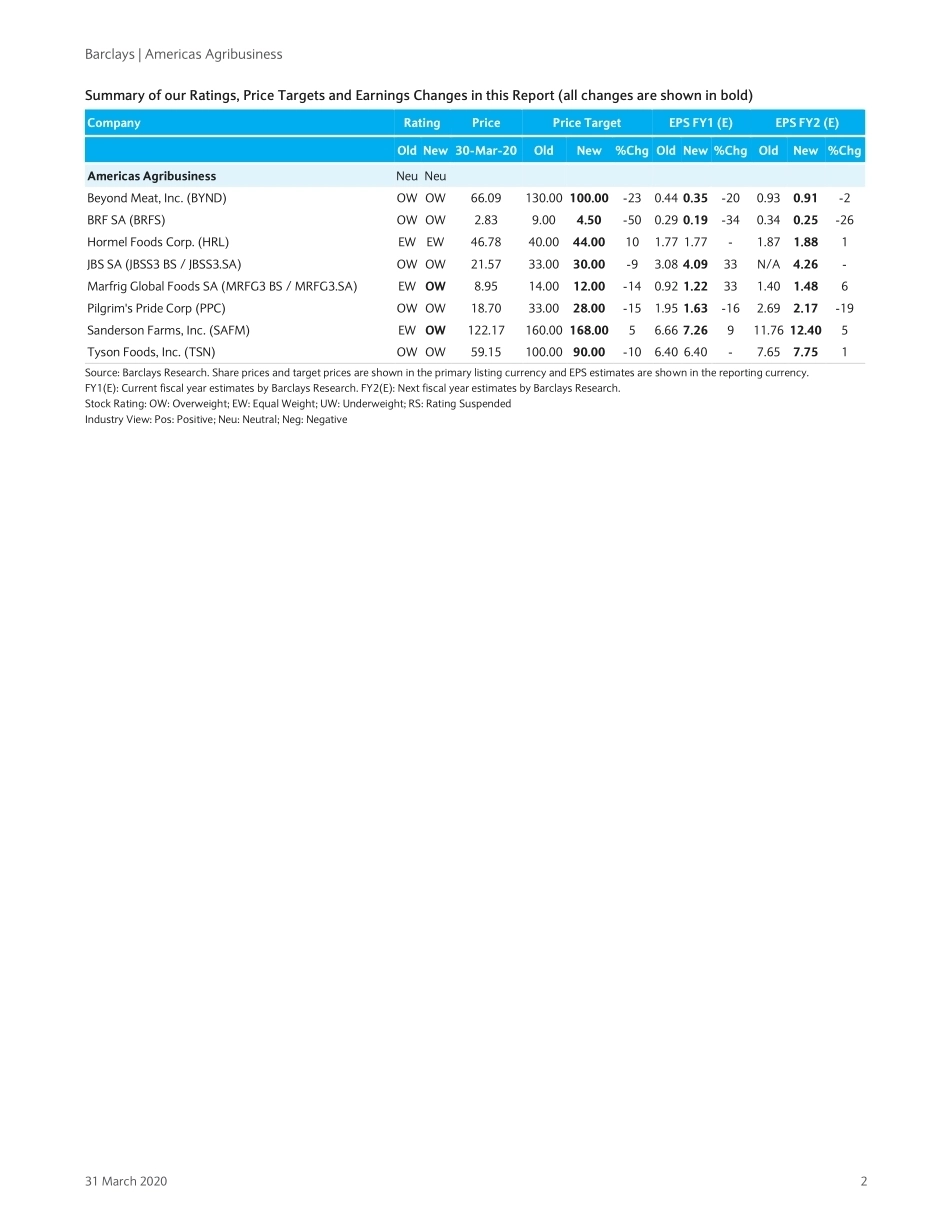
Equity Research 31 March 2020 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. This research report has been prepared in whole or in part by equity research analysts based outside the US who are not registered/qualified as research analysts with FINRA. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 37. Restricted - Internal Americas Agribusiness Ultimately, we all have to eat As the impact of COVID-19 outbreak grows and restaurants and foodservice operators have closed in most jurisdictions, protein sales in retail outlets have surged—ultimately, we all have to eat. As a result, we are updating estimates for all our US and BZ protein companies under coverage and upgrading SAFM and Marfrig to OW from EW. In most cases, we are increasing our estimates for upcoming quarters while leaving our long-term assumptions broadly unchanged. Investors should not lose sight of the fact that even in times of COVID-19 there is a global animal-based protein shortage, which should continue to reinforce fundamentals for our coverage universe during an economic downturn. We believe that in the short term the companies which can easily adapt and shift sales from foodservice into retail channels, as well as companies with a strong balance sheet and healthy liquidity position, are likely to outperform. We see substantial upside potential for companies with leverage between 2–3x ND/EBITDA which, in comparison with companies holding net cash positions, underperformed in recent weeks. In the short term, we believe the expression ’cash is king’ should be of incremental relevance. Hence we upgrade SAFM to OW from EW and increase our PT to $168; we maintain HRL at EW yet increase our HRL price target by 10% to $44 from $40. In the US we continue to see most upside potential for TSN (Top Pick), PPC and BYND, yet we believe higher leverage (i.e. TSN and PPC) and potential logistic issues for BYND could limit upside in coming weeks. In Brazil, we believe investors’ focus has recently been on U.S.$ leveraged companies, yet investors ignored the fact that all three (JBS, BRF, and Marfrig) generate most of income in international markets and consequently leverage is not too much of a concern. Particularly in the case of Marfrig, with 80% of gross profit being generated in the U.S., we see significant upside potential and upgrade the shares to OW but trim our PT to R$12 from R$14. We believe HRL and SAFM have relatively outperformed in recent weeks due to their strong cash position: During times of heightened volatility investors tend to reduce equity holdings and increase cash positions. Within the portfolio of equity holdings, we believe there is a bias towards holding shares of companies with low leverage or preferably even net cash positions. Since the S&P 500 hit an all-time high on 19 Feb 2020, SAFM shares have come down 5.6% while HRL shares are down ~1% vs. the S&P500 down 21.5%. The situation in Brazil is similar: JBS and MRFG outperformed the IBOV Index while BRF underperformed. We attribute the difference mainly to the higher relative exposure of BRF’s sales to domestic sales in Brazil, as all three companies have similar leverage levels, most of which is US$ denominated. Main risks to our relatively positive outlook: Any spike in raw material prices as a result of supply chain disruption, increased trade barriers, and persisting global FX weakness compared to the USD. INDUSTRY UPDATE Americas Agribusiness NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. Americas Agribusiness Benjamin M. Theurer +52 55 5241 3322 benjamin.theurer@barclays.com BBMX, Mexico Antonio Hernandez, CFA + 52 55 5241 3323 antonio.hernandez@barclays.com BBMX, Mexico Barclays | Americas Agribusiness 31 March 2020 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 30-Mar-20 Old New %Chg Old New %Chg Old New %Chg Americas Agribusiness Neu Neu Beyond Meat, Inc. (BYND) OW OW 66.09 130.00 100.00 -23 0.44 0.35 -20 0.93 0.91 -2 BRF SA (BRFS) OW OW 2.83 9.00 4.50 -50 0.29 0.19 -34 0.34 0.25 -26 Hormel Foods Corp. (HRL) EW EW 46.78 40.00 44.00 10 1.77 1.77 - 1.87 1.88 1 JBS SA (JBSS3 BS / JBSS3.SA) OW OW 21.57 33.00 30.00 -9 3.08 4.09 33 N/A 4.26 - Marfrig Global Foods SA (MRFG3 BS / MRFG3.SA) EW OW 8.95 14.00 12.00 -14 0.92 1.22 33 1.40 1.48 6 Pilgrim's Pride Corp (PPC) OW OW 18.70 33.00 28.00 -15 1.95 1.63 -16 2.69 2.17 -19 Sanderson Farms, Inc. (SAFM) EW OW 122.17 160.00 168.00 5 6.66 7.26 9 11.76 12.40 5 Tyson Foods, Inc. ...




发表评论取消回复