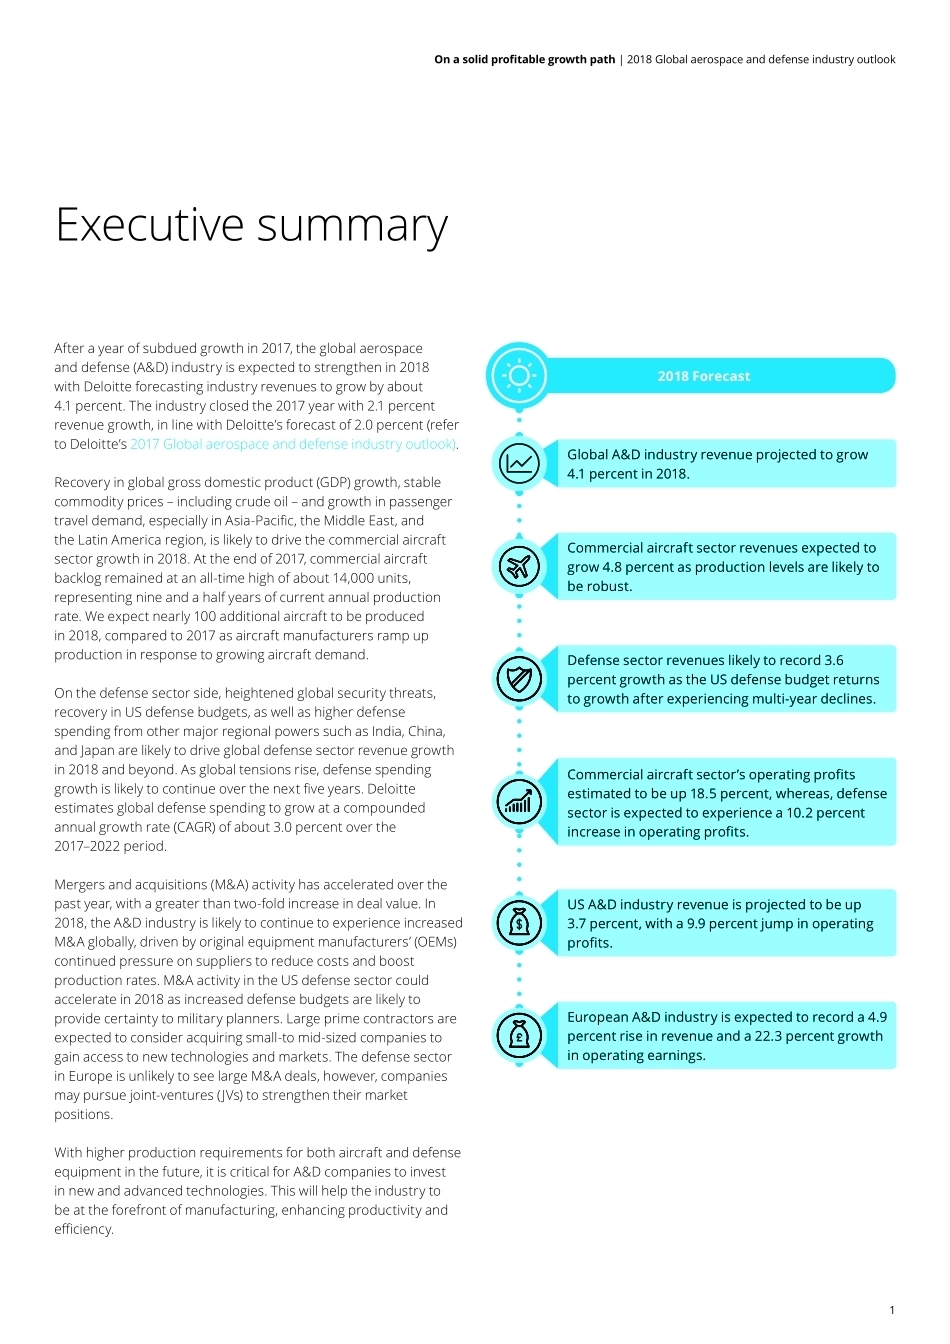
On a solid profitable growth path2018 Global aerospace and defense industry outlookContentsExecutive summary 1Commercial aircraft sector outlook 2Defense sector outlook 6Regional perspectives 9Major aerospace and defense industry trends 12Outlook for M&A activity in 2018 15Global aerospace and defense industry shareholder return 17 performance2017 financial performance 18Endnotes 21Authors 25Contacts 25Executive summaryAfter a year of subdued growth in 2017, the global aerospace and defense (A&D) industry is expected to strengthen in 2018 with Deloitte forecasting industry revenues to grow by about 4.1 percent. The industry closed the 2017 year with 2.1 percent revenue growth, in line with Deloitte’s forecast of 2.0 percent (refer to Deloitte’s 2017 Global aerospace and defense industry outlook). Recovery in global gross domestic product (GDP) growth, stable commodity prices – including crude oil – and growth in passenger travel demand, especially in Asia-Pacific, the Middle East, and the Latin America region, is likely to drive the commercial aircraft sector growth in 2018. At the end of 2017, commercial aircraft backlog remained at an all-time high of about 14,000 units, representing nine and a half years of current annual production rate. We expect nearly 100 additional aircraft to be produced in 2018, compared to 2017 as aircraft manufacturers ramp up production in response to growing aircraft demand. On the defense sector side, heightened global security threats, recovery in US defense budgets, as well as higher defense spending from other major regional powers such as India, China, and Japan are likely to drive global defense sector revenue growth in 2018 and beyond. As global tensions rise, defense spending growth is likely to continue over the next five years. Deloitte estimates global defense spending to grow at a compounded annual growth rate (CAGR) of about 3.0 percent over the 2017–2022 period. Mergers and acquisitions (M&A) activity has accelerated over the past year, with a greater than two-fold increase in deal value. In 2018, the A&D industry is likely to continue to experience increased M&A globally, driven by original equipment manufacturers’ (OEMs) continued pressure on suppliers to reduce costs and boost production rates. M&A activity in the US defense sector could accelerate in 2018 as increased defense budgets are likely to provide certainty to military planners. Large prime contractors are expected to consider acquiring small-to mid-sized companies to gain access to new technologies and markets. The defense sector in Europe is unlikely to see large M&A deals, however, companies may pursue joint-ventures (JVs) to strengthen their market positions.With higher production requirements for both aircraft and defense equipment in the future, it is critical for A&D companies to invest in new and advanced technologies. This will help the industry to be at the forefront of manufacturing, enhancing productivity and efficiency.2018 ForecastGlobal A&D industry revenue projected to grow 4.1 percent in 2018.Commercial aircraft sector revenues expected to grow 4.8 percent as production levels are likely to be robust.Defense sector revenues likely to record 3.6 percent growth as the US defense budget returns to growth after experiencing multi-year declines.Commercial aircraft sector’s operating profits estimated to be up 18.5 percent, whereas, defense sector is expected to experience a 10.2 percent increase in operating profits.US A&D industry revenue is projected to be up 3.7 percent, with a 9.9 percent jump in operating profits. European A&D industry is expected to record a 4.9 percent rise in revenue and a 22.3 percent growth in operating earnings.1On a solid profitable growth path | 2018 Global aerospace and defense industry outlookCommercial aircraft sector outlookThe global commercial aircraft sector is expected to record a 4.8 percent growth in revenues in 2018.1 The sector is likely to experience stronger growth in 2018 after a subdued performance in 2017, primarily driven by an increase in production levels as aircraft manufacturers look to ramp up production to cater to growing aircraft demand. We expect nearly 100 additional commercial aircraft to be produced in 2018, primarily led by narrow body aircraft. Major aircraft manufacturers, Airbus and Boeing, have indicated production rate increases in 2018 and 2019, with Airbus likely to ramp up production of its A320neo in 2018. Boeing is expected to increase the production rate of its 737 from 47 per month in 2017 to 52 per month in 2018 and 57 per month in 2019.2 Travel demand (revenue passenger kilometers or RPKs) increased at a CAGR of 5.1 percent over the last 10 years. Annual passenger enplanements rose from about 2.5 billion in 2008 to more than 4.0 billion in 2017. The year-on-year increase in 2017 was led by the Asia-Pacific region3 and will likely continue to drive passenger growth in the long-term due to the increasing share of midd...




发表评论取消回复