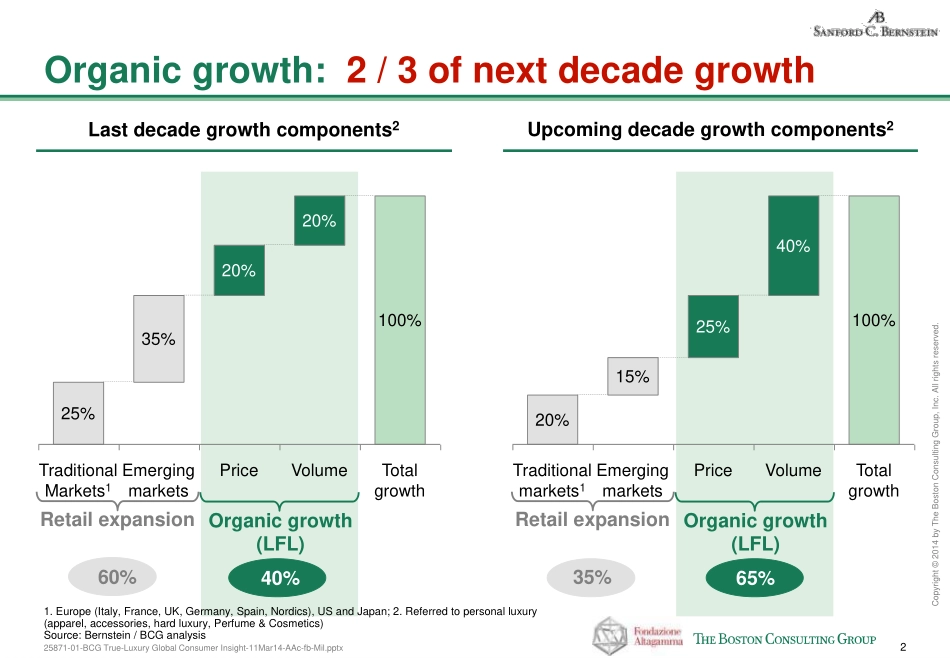
True-Luxury Global Consumer Insight Antonio Achille, Partner & Managing Director 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 1 True-Luxury Global Consumer Insightwe will address 6 "W" questions Why now? Where will growth come from? What will it take to win luxury Consumer? Which luxury segments will drive growth? What's in for you? What makes our study unique? 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 2 Organic growth: 2 / 3 of next decade growth 1. Europe (Italy, France, UK, Germany, Spain, Nordics), US and Japan; 2. Referred to personal luxury (apparel, accessories, hard luxury, Perfume & Cosmetics) Source: Bernstein / BCG analysis Last decade growth components2 Upcoming decade growth components2 20% Price 35% 20% Total growth Traditional Markets1 25% Emerging markets 100% Volume Organic growth (LFL) 40% Retail expansion . 60% 40% Volume 25% 100% Total growth Traditional markets1 20% Price Emerging markets 15% Organic growth (LFL) 65% Retail expansion . 35% 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 3 The CONSUMER era Source: BCG 2013 specific survey '80s '90s '00s 2014 next decade • Style & Design for elites • Temple of Desire • The rise of Global Brands • Retail as part of Brand experience • "Real estate rush" • Consumer: engine of top line and margin growth +Consumer Design +Brand +Retail 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 4 True-Luxury Global Consumer Insightwe will address 6 "W" questions Why now? Where will growth come from? What will it take to win luxury Consumer? Which luxury segments will drive growth? What's in for you? What makes our study unique? 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 5 True-Luxury Consumers talk to you today 1.Cars & Yacht Source: BCG Analysis Cluster Aspirational Prospects Rest of the world Sample (#) ~5 K ~25 K Ultra Beyond money Very high High Core luxury Avg. yearly spend including cars1(K€) <2K€ - 60 K€ 130 K€ 10 K€ 3 K€ Focus of analysis Avg. 30K€ ~10K ~30K 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 6 All luxury categories in scope: our actual sample spent ~230 M€ in luxury goods last year 507015032033560504012060651,500 1,000 500 0 Total 1,320 Other Arts Techno- logy Cars & Yacht Hotel & Exclusive vacations Food & Wine Furnit-ures Cosmetic Watch & jewellery Apparel2 Acces-sories Personal luxury (285 €B) Experiential luxury (445 €B) Cars & Yacht (320€B) Others (270 €B) Luxury market (€B) 1.Personal and Experiential luxury Note: Some numbers are rounded. Source: BCG 2013 specific survey, BCG-IPSOS market research Covered in the Global Luxury Consumer Insight P&E 1 Market: 730 €B 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 7 Mapped Consumers opinion on 100+ luxury brands Source: BCG 2013 specific survey Note: Including: cars, hotel, furniture & design, sunglasses (not exhaustive) 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 8 Sounding board of WW leading brands to ensure robustness and actionability of the insight Source: BCG 2013 specific survey 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 9 True-Luxury Global Consumer Insightwe will address 6 "W" questions Why now? Where will growth come from? What will it take to win luxury Consumer? Which luxury segments will drive growth? What's in for you? What makes our study unique? 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 10 Core luxury Cluster Total Luxury Consumers1 Aspirational Ultra Beyond Very high High Total Core lux. ~380 350 32 Aspirational 2013 2 4 9 17 # (M) Bn(€)1 2020 3 6 12 21 # (M) Bn(€)1 ~440 400 42 +10 M +60 M +50 M 1. Including experiential and personal luxury, excluding cars Source: BCG Analysis 380M Luxury Consumers to become 440M by 2020 25871-01-BCG True-Luxury Global Consumer Insight-11Mar14-AAc-fb-Mil.pptx Copyright © 2014 by The Boston Consulting Group, Inc. All rights reserved. 11 Core luxury Personal and experiential luxury market to grow from today 730 to 880 Bn€ 1. Including experiential and personal luxury, excluding cars Source: BCG Analysis Cluster Total Luxur...




发表评论取消回复