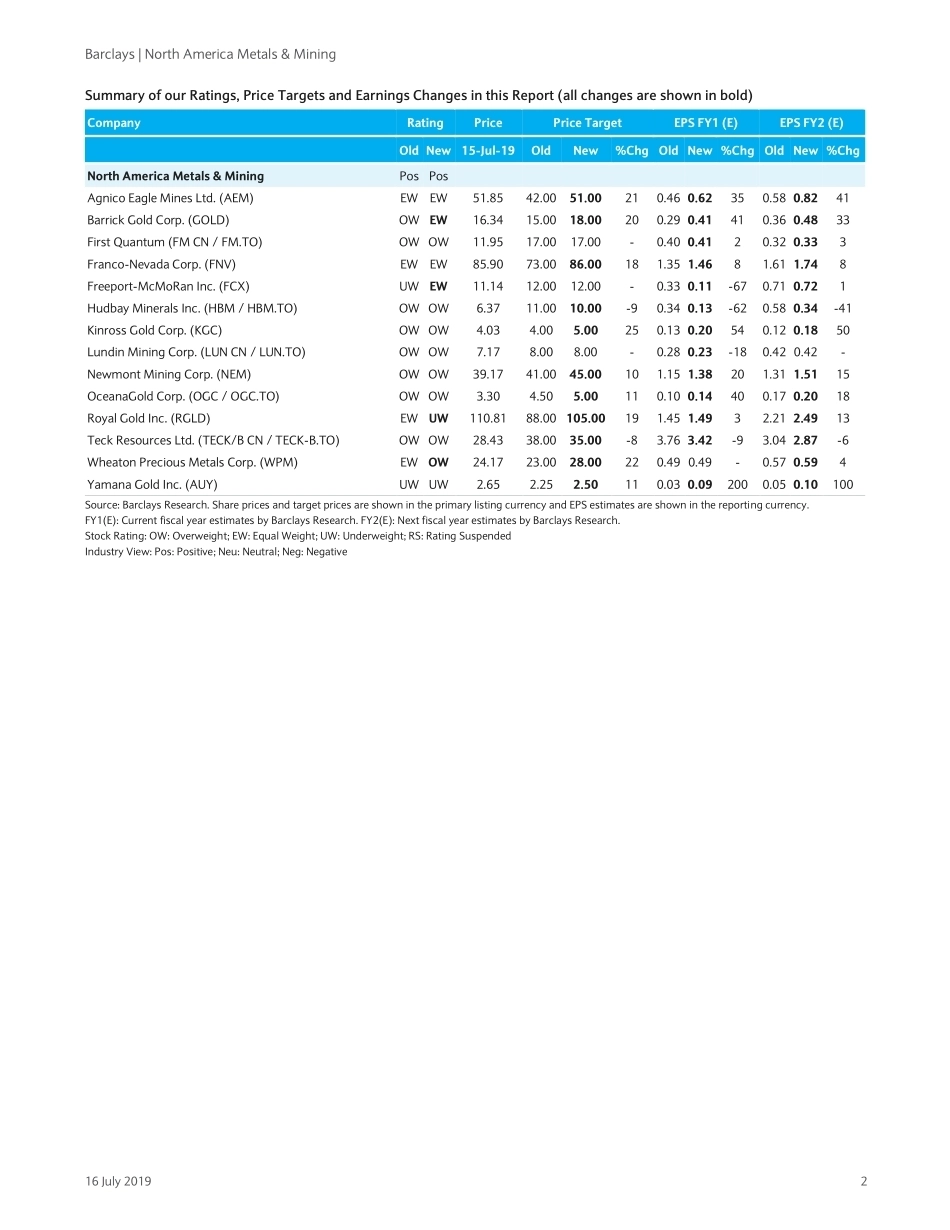
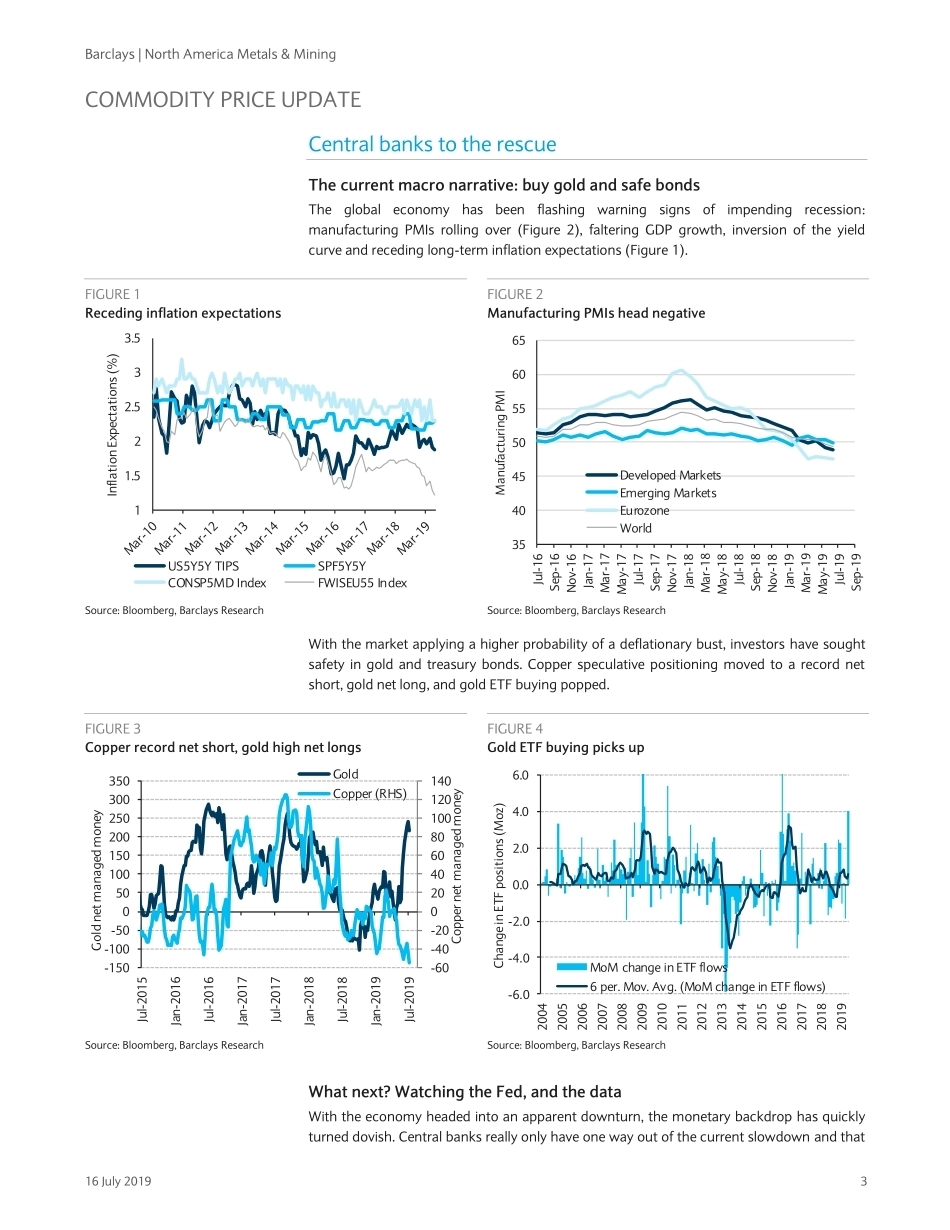
Equity Research 16 July 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. This research report has been prepared in whole or in part by equity research analysts based outside the US who are not registered/qualified as research analysts with FINRA. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 51. Restricted - Internal North America Metals & Mining Awaiting reflation Central banks to the rescue: With the global economy headed into an apparent downturn, the monetary backdrop is quickly turning dovish. Gold has been a favored hedge and delivered a very welcome rally above US$1,400/oz. We believe gold can sustain some of its gains but we are not expecting a meaningful breakout from here for now. In our view, central banks really only have one way out of the current slowdown and that is through reflation. If this economic cycle can be prolonged, recession probabilities could again recede with the record managed money futures net short against copper and high net longs against gold likely to reverse. Raising multiples on gold equities: Gold multiples inflate in a bull market. While we have increased our gold P/NAV multiples by ~20% we are somewhat cautious of a retracement and we are not calling for unbridled upside. That said, we continue to see upside re-rate potential from NEM, KGC, and OGC. The gold miners will need to reinvest in operations after years of depleting their capital base, but with the gold price allowing for margin expansion we believe they may be able to deliver the delicate balance of modest free cash flow while also reinvesting in exploration and growth, thereby justifying higher multiples. The top quality names have seen significant multiple inflation with AEM, FNV, and RGLD trading at an average of 2.02x P/NAV, versus peers at 1.28x. We are downgrading RGLD to Underweight as we see the 35% rally over recent weeks as overdone, and we raise WPM to Overweight as our preferred streamer on valuation. We also downgrade GOLD to Equal Weight on valuation. Base metal equities trading below replacement value: While the industrial complex may have to muddle through some soft data and underwhelming stimulus in China before we see the effects of reflation, we see base metals as offering good potential returns for contrarian investors. The capital cycle remains our friend here; industry capex has been too low for years and many of the miners are trading below replacement value. While FCX remains our least preferred base metal miner, we can’t ignore the substantial production growth ahead in both copper and gold if it can deliver on its guidance at Grasberg. While we continue to view Grasberg as a risk, progress to-date has been encouraging. With downside over the next year potentially limited, we upgrade to Equal Weight. Quarterly preview and commodity price update: We have marked-to-market Q2/19 commodity prices and made modest changes to forecasts. We increased our gold outlook for the next two years by 5%/4%, averaging $1,400/oz in H2/19 and $1,350/oz in 2020, in-line with our long-term price forecast of $1,350. This increased our gold earnings forecasts. Base metal forecasts were reduced modestly. INDUSTRY UPDATE North America Metals & Mining POSITIVE Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. North America Metals & Mining Matthew Murphy, CFA +1 416 863 8963 matthew.murphy@barclays.com BCCI, Canada David Hove, CFA +1 416 863 8935 david.hove@barclays.com BCCI, Canada Stefan Karolidis +1 416 863 8958 stefan.karolidis@barclays.com BCCI, Canada European Mining Ian Rossouw, CFA +44 (0)20 3555 2620 ian.rossouw@barclays.com Barclays, UK Barclays | North America Metals & Mining 16 July 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 15-Jul-19 Old New %Chg Old New %Chg Old New %Chg North America Metals & Mining Pos Pos Agnico Eagle Mines Ltd. (AEM) EW EW 51.85 42.00 51.00 21 0.46 0.62 35 0.58 0.82 41 Barrick Gold Corp. (GOLD) OW EW 16.34 15.00 18.00 20 0.29 0.41 41 0.36 0.48 33 First Quantum (FM CN / FM.TO) OW OW 11.95 17.00 17.00 - 0.40 0.41 2 0.32 0.33 3 Franco-Nevada Corp. (FNV) EW EW 85.90 73.00 86.00 18 1.35 1.46 8 1.61 1.74 8 Freeport-McMoRan Inc. (FCX) UW EW 11.14 12.00 12.00 - 0.33 0.11 -67 0.71 0.72 1 Hudbay Minerals Inc. (HBM / HBM.TO) OW OW 6.37 11.00 10.00 -9 0.34 0.13 -62 0.58 0.34 -41 Kinross Gold Corp. (KGC) OW OW 4.03 4.00 5.00 25 0.13 0.20 54 0.12 0.18 50 Lundin Mining Corp. (LUN CN / LUN.TO) OW OW 7.17 8.00 8.00 - 0.28 0.23 -18 0.42 0.42...




发表评论取消回复