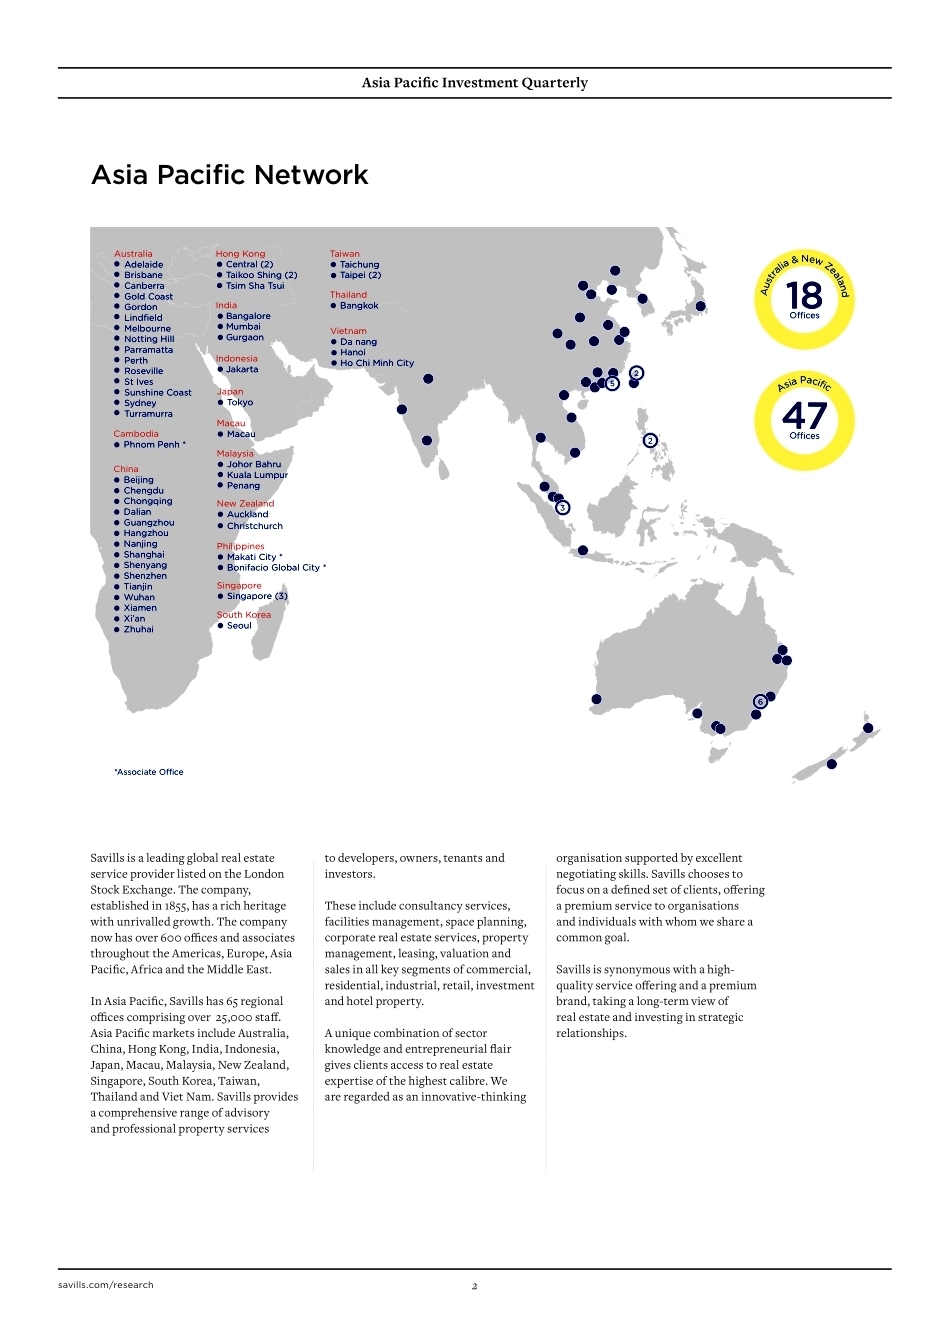
REPORTSavills ResearchAsia Pacifi c – Q4 2018Investment Quarterly每日免费阅读行业报告1、每日星球内分享10+精品报告;2、不定时分享国际投行报告,脱水研报等;3、行业报告均为公开内容,版权归原作者所有,星球仅分享内部学习。扫描右侧二维码即刻加入【行业报告(免费) 】星球(此页只为更多需要行业报告的朋友提供便利,希望不会影响您的阅读,谢谢理解!)2savills.com/researchAsia Pacifi c Investment Quarterly3562*Associate Office218Offices Australia & New Zealand47OfficesAsia PacificAustraliaAdelaideBrisbaneCanberraGold CoastGordonLindfieldMelbourneNotting HillParramattaPerthRosevilleSt IvesSunshine CoastSydneyTurramurraChinaBeijingChengduChongqingDalianGuangzhouHangzhouNanjingShanghaiShenyangShenzhen TianjinWuhanXiamenXi’anZhuhaiTaiwanTaichungTaipei (2)ThailandBangkokVietnamDa nangHanoiHo Chi Minh CityHong KongCentral (2)Taikoo Shing (2)Tsim Sha TsuiIndiaBangaloreMumbaiGurgaonIndonesiaJakartaNew ZealandAucklandChristchurchJapanTokyoMacauMacauSingaporeSingapore (3)South KoreaSeoulMalaysiaJohor BahruKuala LumpurPenangCambodiaPhnom Penh *PhilippinesMakati City *Bonifacio Global City * Savills is a leading global real estate service provider listed on the London Stock Exchange. The company, established in 1855, has a rich heritage with unrivalled growth. The company now has over 600 offi ces and associates throughout the Americas, Europe, Asia Pacifi c, Africa and the Middle East.In Asia Pacifi c, Savills has 65 regional offi ces comprising over 25,000 staff . Asia Pacifi c markets include Australia, China, Hong Kong, India, Indonesia, Japan, Macau, Malaysia, New Zealand, Singapore, South Korea, Taiwan, Thailand and Viet Nam. Savills provides a comprehensive range of advisory and professional property services to developers, owners, tenants and investors. These include consultancy services, facilities management, space planning, corporate real estate services, property management, leasing, valuation and sales in all key segments of commercial, residential, industrial, retail, investment and hotel property.A unique combination of sector knowledge and entrepreneurial fl air gives clients access to real estate expertise of the highest calibre. We are regarded as an innovative-thinking organisation supported by excellent negotiating skills. Savills chooses to focus on a defi ned set of clients, off ering a premium service to organisations and individuals with whom we share a common goal. Savills is synonymous with a high-quality service off ering and a premium brand, taking a long-term view of real estate and investing in strategic relationships.Asia Pacifi c Network3Asia Pacifi c Investment QuarterlyContent04050607080910111213141516171819202122AustraliaChina (Northern) - BeijingChina (Northern) - TianjinChina (Western) - ChengduChina (Southern) - GuangzhouChina (Southern) - ShenzhenChina (Eastern) - ShanghaiHong KongIndonesiaJapanMacauMalaysiaNew ZealandSingaporeSouth KoreaTaiwanThailandViet NamMajor transactions Q4 20184savills.com/researchAsia Pacifi c Investment QuarterlyAustraliaShrabastee MallikDirectorResearch & Consultancy+61 2 8215 8880smallik@savills.com.auPaul CraigCEO+61 2 8215 8888pcraig@savills.com.auAustralian’s commercial property sector continued to record notable capital value growth with ongoing yield compression recorded across all non-residential property classes, over the last quarter of 2018, as investor appetite remained as strong as ever. Much of the conversation over 2018 revolved around how much longer the yield compression cycle across Australian non-residential property would last, particularly for the offi ce markets of Sydney CBD and Melbourne CBD. However, total sales volumes remained strong, with AUD$29.75 billion of offi ce, industrial and retail assets transacting in 2018. Transaction volumes in the offi ce sector continued to dominate, with total volumes in Q4/2018 being boosted by commercial property fund manager Charter Hall’s purchase of two offi ce buildings in Sydney for AUD$804 million, just before the end of the year.Total returns in the offi ce sector continued to be boosted by capital value growth, with total returns recorded at 14.4% in the 12 months to September 2018 (latest available from MSCI / IPD). The Sydney CBD and fringe markets drove this performance with returns recorded at 18.0% in Parramatta and 17.1% in Sydney CBD. Positively, total returns in Brisbane CBD and Perth CBD continued their upward trend, returning 9.8% and 8.7%. In the industrial sector, total returns moderated somewhat in the September quarter, returning 11.6% in the 12 months to September 2018, though all markets nationally performed well above their long term CAGRs. The proliferation of ecommerce in Australia is driving the industrial sector’s outperformance in the capital cities, with growth in the ecommerce industry (which is still in its infancy, and will likely see aggressive growth over the short to medium term) having a positive fl ow on eff ect to industrial demand.Rising global bond yields over 2018 saw the conversation turning to what this will mean for real estate yields, particularly in Australia, where domestic monetary policy ...




发表评论取消回复