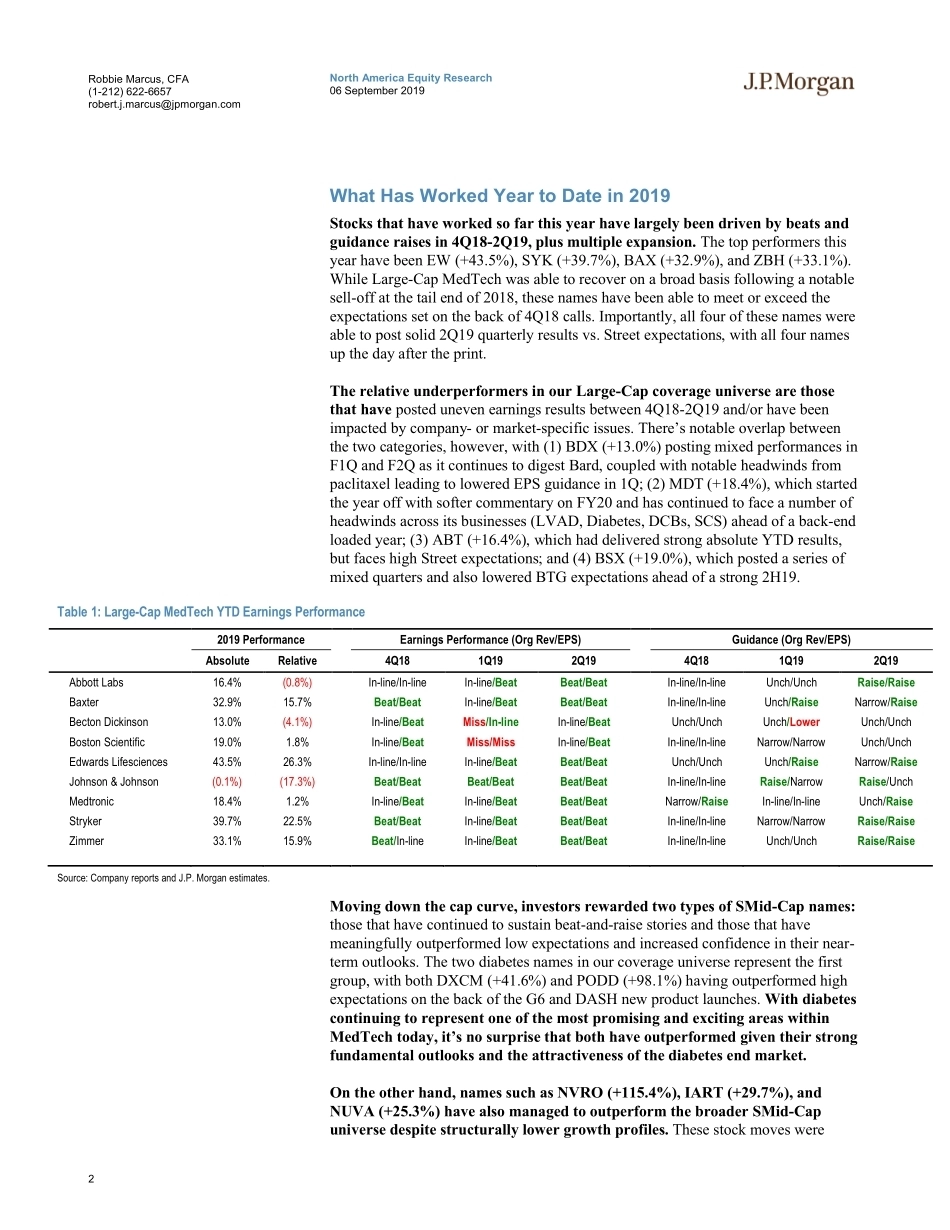
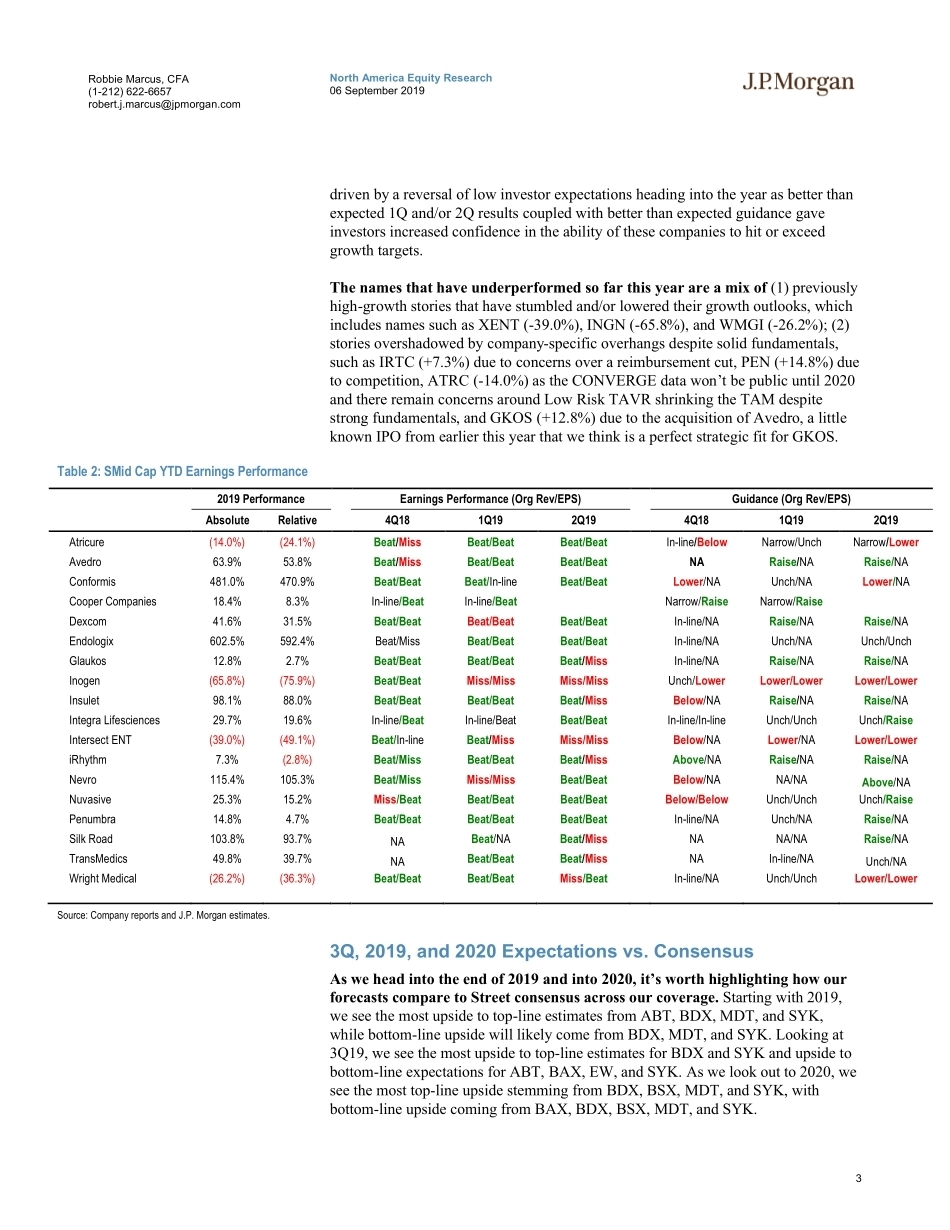
North America Equity Research06 September 2019 Medical Supplies & DevicesBack to School; 1H19 Recap, 2H19 and 2020 OutlookMedical Supplies & DevicesRobbie Marcus, CFA AC(1-212) 622-6657robert.j.marcus@jpmorgan.comAllen Gong(1-212) 622-9520allen.gong@jpmorgan.comChristian Moore(1-212) 622-7458christian.d.moore@jpmorgan.comJ.P. Morgan Securities LLCSee page 19 for analyst certification and important disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.www.jpmorganmarkets.comAs we move past 2Q19 earnings and into the final months of the year, we thought it would be worthwhile to take a step back and take a look at (1) how the MedTech sector has performed YTD, (2) our thoughts on valuation andfundamentals as we move toward 3Q19 earnings and 2020 guidance, and (3) a broad overview of our positioning with respect to our coverage universe. Heading into 2H19, our top picks are Baxter and iRhythm, plus what we’d own into 2H19 are BSX, MDT, SYK, ZBH, DXCM, IART, NVRO, NUVA, PODD, and SILK. All references to stock prices and valuation are based on the 9/4/19 close. MedTech stocks have (again) posted solid results so far in 2019 with an average gain of 19.3% year to date. Large-cap names have outperformed the S&P 500 by 2% and the Healthcare index by roughly 15%, an inverse of 2018 where MedTech outperformed by 19% and 8%, respectively. This picture largely holds when looking at performance by end market, with Cardio Devices and Orthopedics outperforming by 10% and 13%, respectively, vs. 37% and 4% in 2018. The only outlier here is Suppliers as legal concerns for J&J brought performance down for the whole group (-2%). Excluding JNJ, Suppliers are also outperforming the S&P, albeit at a lower 4%. SMid cap MedTech has been more volatile, with our coverage of small-cap names up 15% excluding ELGX and recent IPOs, with outperformance of 5% over the Russel 2000. Within Large Cap, multiple expansion has been the biggest driver of share price gains. Currently, large-cap MedTech stocks are trading at 20.9x NTM cash EPS, 16.5x NTM EBITDA, and a FCF yield of 4.5%, about two turns above the 18.3x, 14.4x, and 5.4% we saw entering 2019. While we’ve seensome choppiness in the market related to macro concerns around globaluncertainty, trade tariffs, and interest rates in May and August, MedTech continues to be the preferred place to hide in Healthcare as it doesn’t have direct exposure to drug price reform. As a result, the group trades at a 25.6% premium to the S&P 500, a modest step down from the 27.8% we saw in January. SMid-Cap multiples have remained relatively stable, excluding the many successful IPOs we’ve seen this year. Currently, SMid-cap names are trading at roughly 6.0x trailing EV/sales, although there remains a notable spread between high-multiple and low-multiple names (12.3x at the high end vs. 2.9x at the low end). We believe fundamentals at these high-multiple names remain strong, however, and we continue to see these elevated valuations as sustainable given a healthy setup for beat-and-raise quarters plus a strong market multiple. Sector fundamentals continue to look strong with healthy, stable end markets and record levels of innovation supporting the pipeline. While comps for the large-cap universe gets harder in the back half, we nonetheless expect to see an acceleration from the ~4.8% growth seen in 1H19 to ~5.8% in the back half as our names lap company-specific headwinds and benefit from new product ramps. On the other hand, we expect both Mid Caps and SmallCaps will moderate, with growth of 8.0-9.0% ex-DXCM (from ~12.0%) and high-growth IPOs 6.0-6.5% (from 9-10%), respectively. With FX headwinds moderating as well in the back half of the year, we continue to expect EPS growth in the high single digits for the full year.2North America Equity Research06 September 2019Robbie Marcus, CFA(1-212) 622-6657robert.j.marcus@jpmorgan.com What Has Worked Year to Date in 2019Stocks that have worked so far this year have largely been driven by beats and guidance raises in 4Q18-2Q19, plus multiple expansion. The top performers this year have been EW (+43.5%), SYK (+39.7%), BAX (+32.9%), and ZBH (+33.1%). While Large-Cap MedTech was able to recover on a broad basis following a notable sell-off at the tail end of 2018, these names have been able to meet or exceed the expectations set on the back of 4Q18 calls. Importantly, all four of these names were able to post solid 2Q19 quarterly results vs. Street expectations, with all four names up the day after the print. The relative underperformers in our Large-Cap coverage universe are those that have posted uneven earnings results between 4Q18-2Q19 and/or have been impacted by company- or marke...




发表评论取消回复