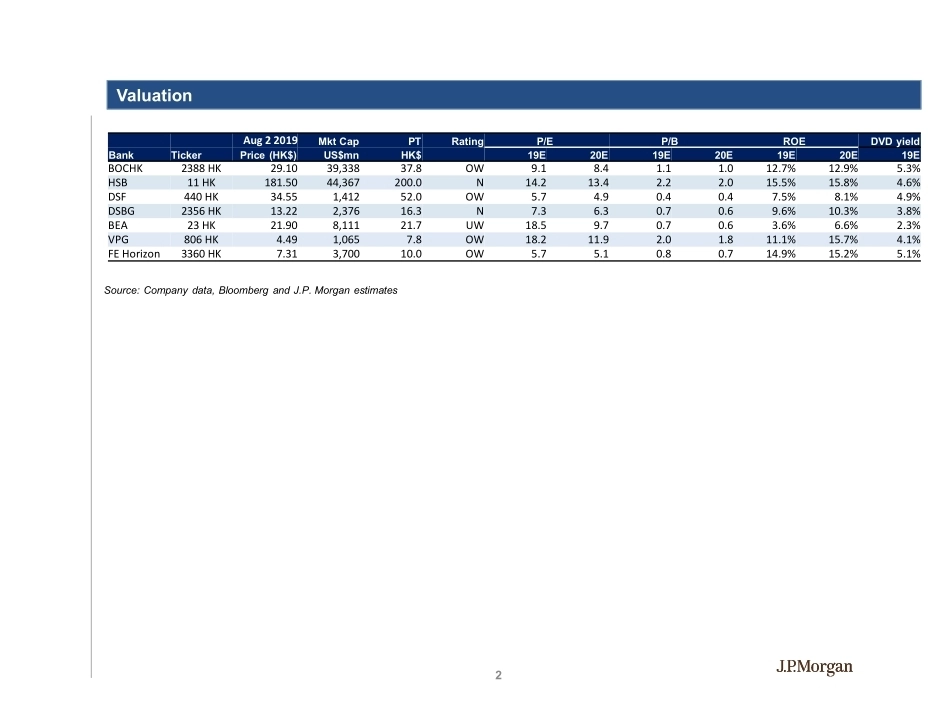
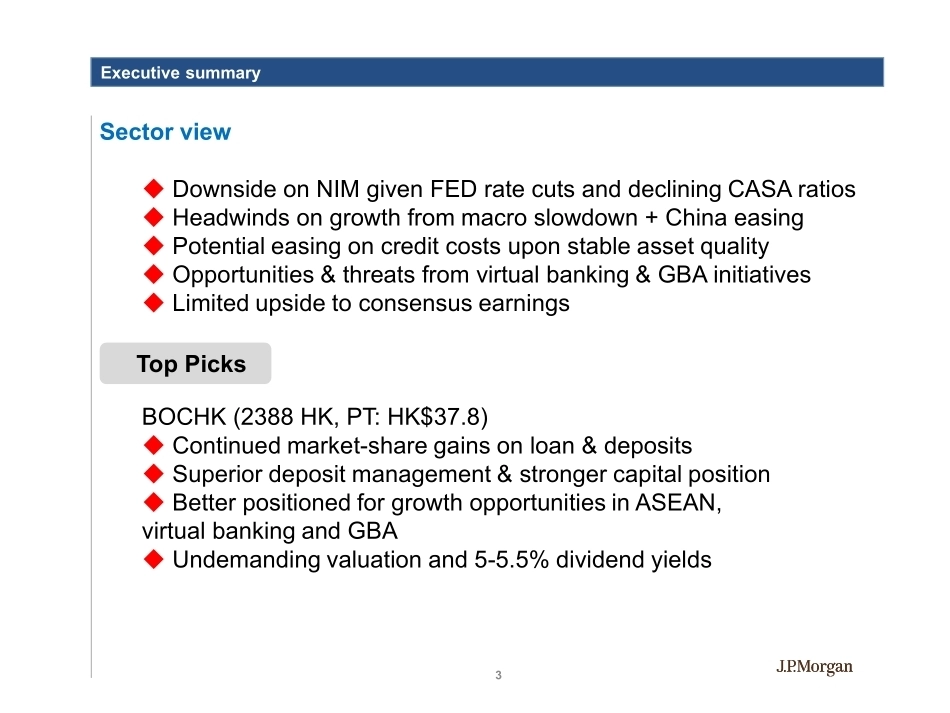
See the end pages of this presentation for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Asia Pacific Equity ResearchAugust 2019Hong Kong BanksModerating outlook, but largely in the priceJemmy HuangACJ.P. Morgan Securities (Asia Pacific) LimitedTelephone: (886) 2-2725-9870Email: jemmy.s.huang@jpmorgan.comLeo WengJ.P. Morgan Securities (Asia Pacific) LimitedTelephone: (852) 2800-8511Email: leo.weng@jpmorgan.comKatherine LeiJ.P. Morgan Securities (Asia Pacific) LimitedTelephone: (852) 2800-8552Email: katherine.lei@jpmorgan.com2Source: Company data, Bloomberg and J.P. Morgan estimatesAug 2 2019Mkt CapPTRatingP/EP/BROEDVD yieldBankTickerPrice (HK$)US$mnHK$19E20E19E20E19E20E19EBOCHK2388 HK29.10 39,338 37.8 OW9.1 8.4 1.1 1.0 12.7%12.9%5.3%HSB11 HK181.50 44,367 200.0 N14.2 13.4 2.2 2.0 15.5%15.8%4.6%DSF440 HK34.55 1,412 52.0 OW5.7 4.9 0.4 0.4 7.5%8.1%4.9%DSBG2356 HK13.22 2,376 16.3 N7.3 6.3 0.7 0.6 9.6%10.3%3.8%BEA23 HK21.90 8,111 21.7 UW18.5 9.7 0.7 0.6 3.6%6.6%2.3%VPG806 HK4.49 1,065 7.8 OW18.2 11.9 2.0 1.8 11.1%15.7%4.1%FE Horizon3360 HK7.31 3,700 10.0 OW5.7 5.1 0.8 0.7 14.9%15.2%5.1%Valuation 3Executive summarySector view◆ Downside on NIM given FED rate cuts and declining CASA ratios◆ Headwinds on growth from macro slowdown + China easing◆ Potential easing on credit costs upon stable asset quality◆ Opportunities & threats from virtual banking & GBA initiatives◆ Limited upside to consensus earningsBOCHK (2388 HK, PT: HK$37.8)◆ Continued market-share gains on loan & deposits◆ Superior deposit management & stronger capital position◆ Better positioned for growth opportunities in ASEAN, virtual banking and GBA ◆ Undemanding valuation and 5-5.5% dividend yieldsTop Picks 4PPOP – loan growth momentum to stay lukewarmLoan growth by sector – 1Q19Source: HKMA and J.P. Morgan.Loans in HK ex mortgages vs GDPHK: Trade volume vs trade financeSource: CEIC, HKMA and J.P. MorganSource: CEIC, HKMA and J.P. Morgan•Sector loan growth has trended down from 4.4% in 4Q18 to 3.1% in 1Q19 and 3.3% as of 2Q19•FCY denominated loans were the key drag (-4% yoy) while HKD denominated loans registered steady growth (+8% yoy) in 1H19 likely due to lower funding costs•Mortgage growth (8% YoY as of 1Q19) has been decent but it remains to be seen whether the momentum could be sustained into 2H19•Non-mortgage consumer lending is facing pressure as well given slowdown on private consumption•We expect mid single-digit loan growth in FY19, similar to FY18, with potential upside if comprehensive deal is reached for the US-China trade talks5HK property transactions vs new mortgagesHK personal lending vs private consumptionSource: HKMA, CEIC and J.P. MorganSource: CEIC and J.P. MorganHK offshore lending vs China loan growthLoan growth by currencySource: HKMA and J.P. MorganSource: HKMA and J.P. MorganPPOP – loan growth slowdown on moderating macro outlook & lower risk appetites at banks6PPOP – NIM to face pressure after FED rate cutsNIM sensitivity on 25bps decline of USD & HKD yieldsNote: Figures are based on 25bps downward shifts of USD & HKD yield curvesSource: CEIC and J.P. Morgan•We expect NIM in 1H19 to be up YoY but down HoH at large banks, tracking the HIBOR movement, and the migration should be better than feared given the HIBOR rally in 2Q19•However, declining CASA ratio and lengthening duration of time deposits are the adverse factors•FED rate cuts signal an official turn on the interest rate cycle on USD while HKD is likely to follow suit under the currency peg mechanism•Based on our sensitivity analysis, every 25bps of downward shift on USD and HKD yield curves would result in 7-14bps of NIM contraction in the coming 12 months; HSB is likely to face bigger pressure than peers while BEA could benefit from declining funding costs in ChinaNIM migrationSource: Company data and J.P. Morgan estimates.201620172018A2019E2020EBOCHK1.32%1.57%1.62%1.63%1.62%BEA1.60%1.65%1.73%1.79%1.79%HSB1.85%1.94%2.18%2.13%2.13%DSBG1.98%1.98%2.01%1.84%1.87%2H161H172H171H182H18BOCHK1.35%1.62%1.53%1.53%1.70%BEA1.62%1.64%1.67%1.70%1.76%HSB1.86%1.94%1.94%2.10%2.26%DSBG2.01%1.94%2.02%2.09%1.93%NIM vs. Prime-HIBOR spread vs. deposit spread (%)Source: Company data, Oriental Daily, and J.P. Morgan7LIBOR-HIBOR spreads3M1Y USD forward curve vs. 3M1Y HKD forward curveSource: Bloomberg, J.P. Morgan.Source: Bloomberg, CEIC and J.P. MorganAggregate balance (excess liquidity) has further declined upon HKMA moves in 2Q19HKD Exchange rateSource: HKMA J.P. MorganSource: Bloomberg and J.P. MorganPPOP – LIBOR/HIBOR spreads and USD/HKD FX rates indicate liquidity remains sufficient8Composite interest rates vs. weighted deposit ra...




发表评论取消回复