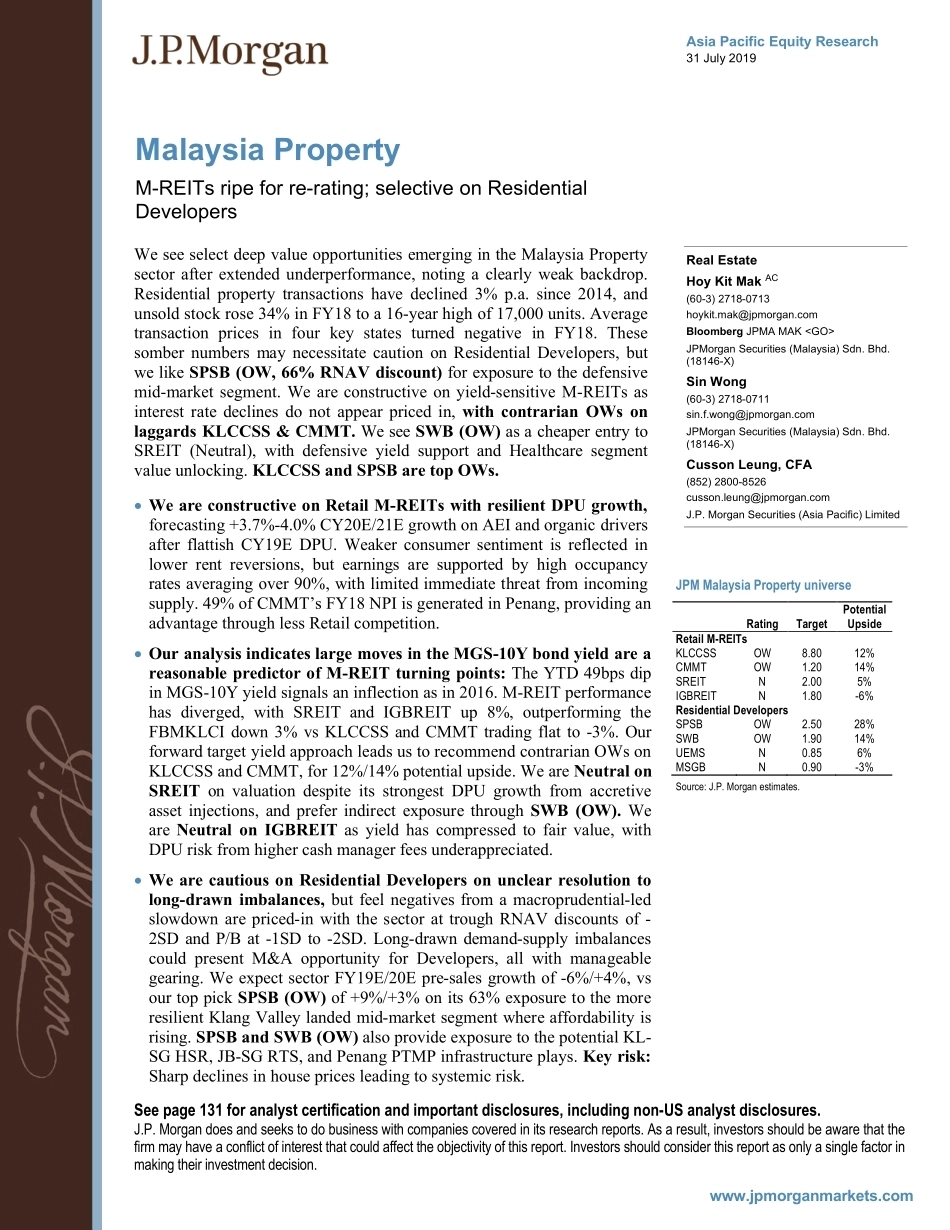
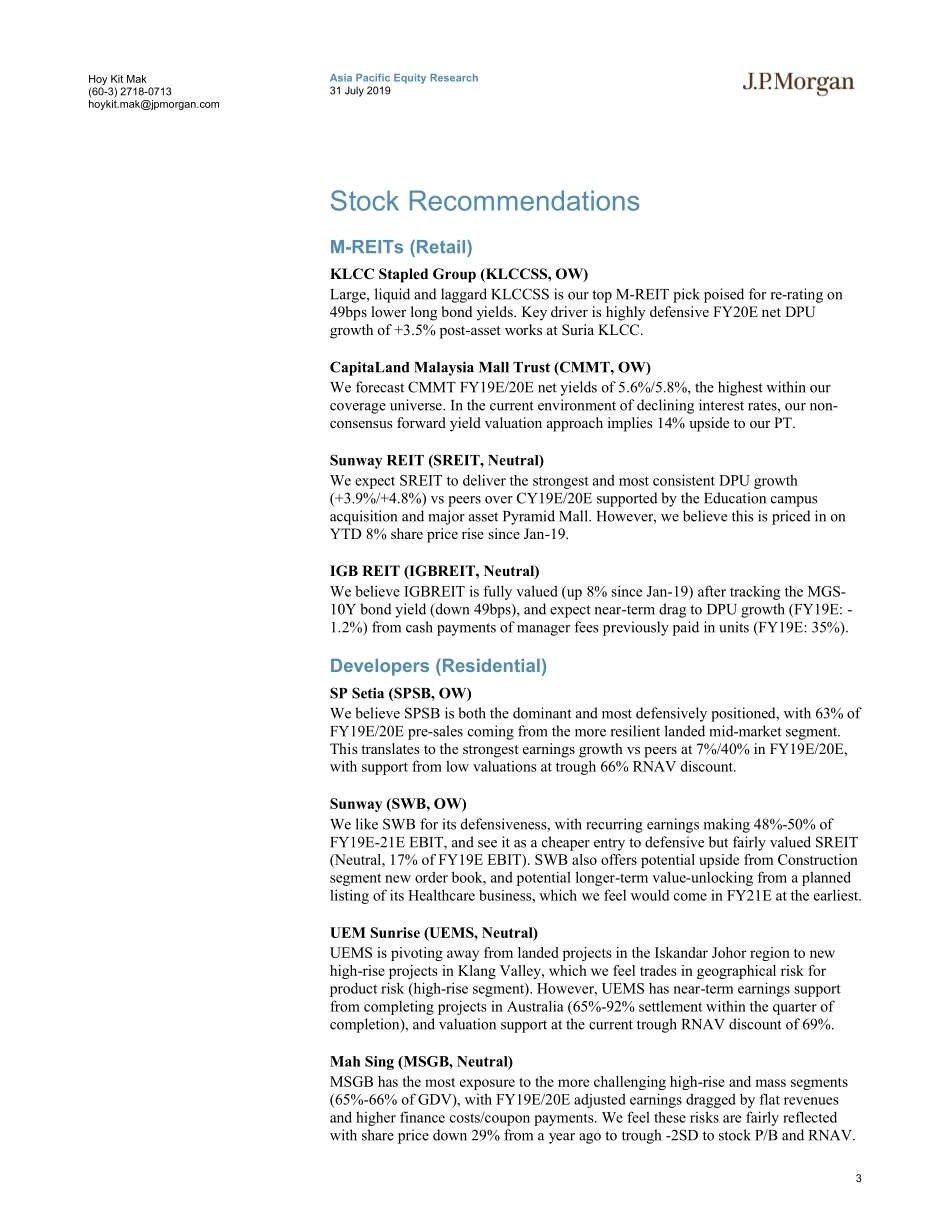
Asia Pacific Equity Research31 July 2019 Malaysia PropertyM-REITs ripe for re-rating; selective on Residential DevelopersReal EstateHoy Kit Mak AC(60-3) 2718-0713hoykit.mak@jpmorgan.comBloomberg JPMA MAK JPMorgan Securities (Malaysia) Sdn. Bhd. (18146-X)Sin Wong(60-3) 2718-0711sin.f.wong@jpmorgan.comJPMorgan Securities (Malaysia) Sdn. Bhd. (18146-X)Cusson Leung, CFA(852) 2800-8526cusson.leung@jpmorgan.comJ.P. Morgan Securities (Asia Pacific) LimitedSee page 131 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.www.jpmorganmarkets.comWe see select deep value opportunities emerging in the Malaysia Property sector after extended underperformance, noting a clearly weak backdrop. Residential property transactions have declined 3% p.a. since 2014, and unsold stock rose 34% in FY18 to a 16-year high of 17,000 units. Average transaction prices in four key states turned negative in FY18. These somber numbers may necessitate caution on Residential Developers, but we like SPSB (OW, 66% RNAV discount) for exposure to the defensive mid-market segment. We are constructive on yield-sensitive M-REITs as interest rate declines do not appear priced in, with contrarian OWs on laggards KLCCSS & CMMT. We see SWB (OW) as a cheaper entry to SREIT (Neutral), with defensive yield support and Healthcare segment value unlocking. KLCCSS and SPSB are top OWs. We are constructive on Retail M-REITs with resilient DPU growth,forecasting +3.7%-4.0% CY20E/21E growth on AEI and organic drivers after flattish CY19E DPU. Weaker consumer sentiment is reflected in lower rent reversions, but earnings are supported by high occupancy rates averaging over 90%, with limited immediate threat from incoming supply. 49% of CMMT’s FY18 NPI is generated in Penang, providing an advantage through less Retail competition. Our analysis indicates large moves in the MGS-10Y bond yield are a reasonable predictor of M-REIT turning points: The YTD 49bps dip in MGS-10Y yield signals an inflection as in 2016. M-REIT performance has diverged, with SREIT and IGBREIT up 8%, outperforming the FBMKLCI down 3% vs KLCCSS and CMMT trading flat to -3%. Our forward target yield approach leads us to recommend contrarian OWs on KLCCSS and CMMT, for 12%/14% potential upside. We are Neutral on SREIT on valuation despite its strongest DPU growth from accretive asset injections, and prefer indirect exposure through SWB (OW). We are Neutral on IGBREIT as yield has compressed to fair value, with DPU risk from higher cash manager fees underappreciated. We are cautious on Residential Developers on unclear resolution to long-drawn imbalances, but feel negatives from a macroprudential-led slowdown are priced-in with the sector at trough RNAV discounts of -2SD and P/B at -1SD to -2SD. Long-drawn demand-supply imbalances could present M&A opportunity for Developers, all with manageable gearing. We expect sector FY19E/20E pre-sales growth of -6%/+4%, vs our top pick SPSB (OW) of +9%/+3% on its 63% exposure to the more resilient Klang Valley landed mid-market segment where affordability is rising. SPSB and SWB (OW) also provide exposure to the potential KL-SG HSR, JB-SG RTS, and Penang PTMP infrastructure plays. Key risk:Sharp declines in house prices leading to systemic risk.JPM Malaysia Property universeRatingTargetPotential UpsideRetail M-REITsKLCCSSOW8.8012%CMMTOW1.2014%SREITN2.005%IGBREITN1.80-6%Residential DevelopersSPSBOW2.5028%SWBOW1.9014%UEMSN0.856%MSGBN0.90-3%Source: J.P. Morgan estimates.2Asia Pacific Equity Research31 July 2019Hoy Kit Mak(60-3) 2718-0713hoykit.mak@jpmorgan.com Table of ContentsStock Recommendations.........................................................3Investment Summary ...............................................................4Our key thesis in killer charts..................................................8Retail M-REITs: Imminent re-rating in a rate cut environment..............................................................................9M-REIT valuation methodology: Time for change to capture turning point ...........................................................................12Defensive DPU growth of 3.7%-4.0% in CY20E-21E after year of AEIs.............................................................................15Deep dive on M-REIT assets..................................................19Retail segment outlook..........................................................21Office segment outlook..........................................................25Residential Developers: Survival of the fittest.....................26Residential mid-market landed segment is the only bright ...




发表评论取消回复