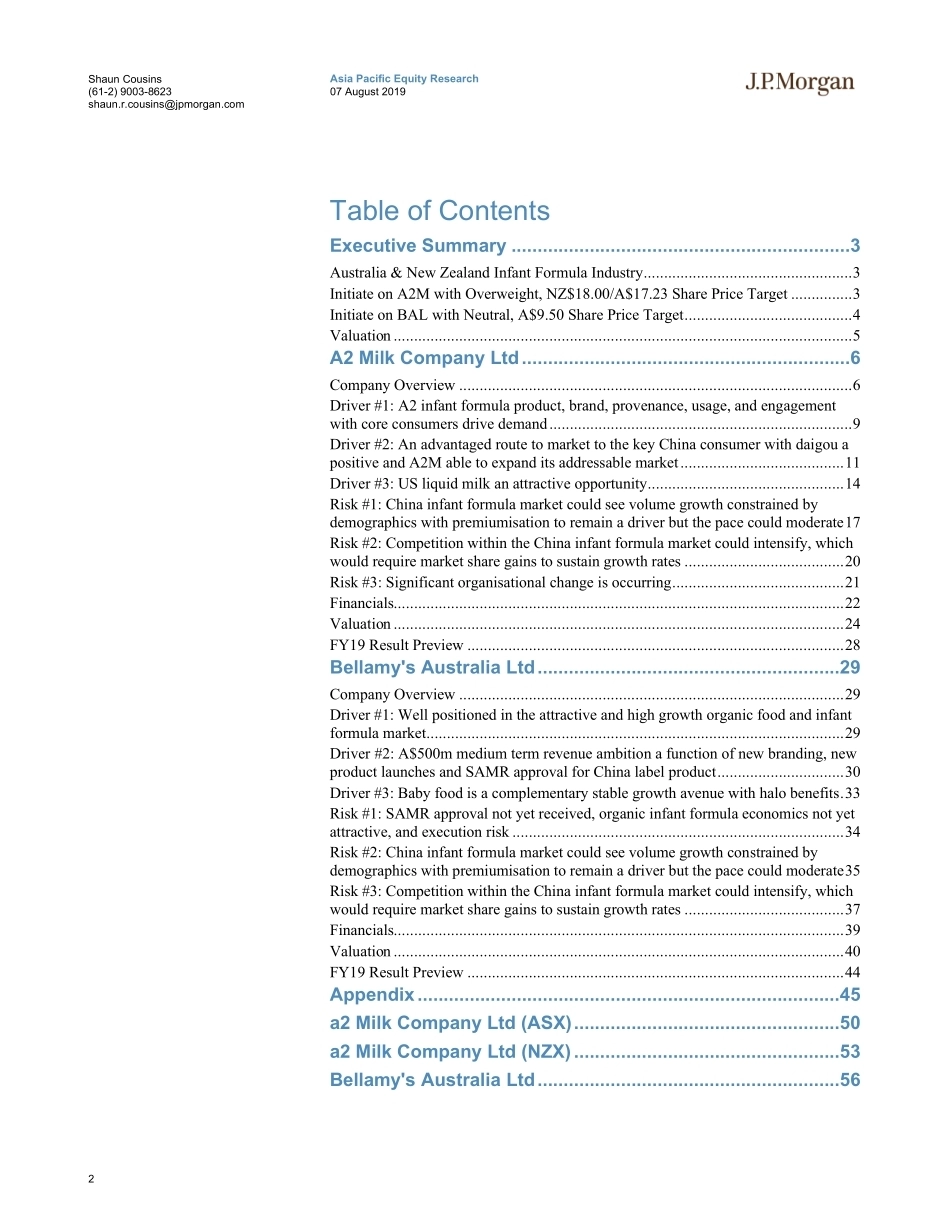
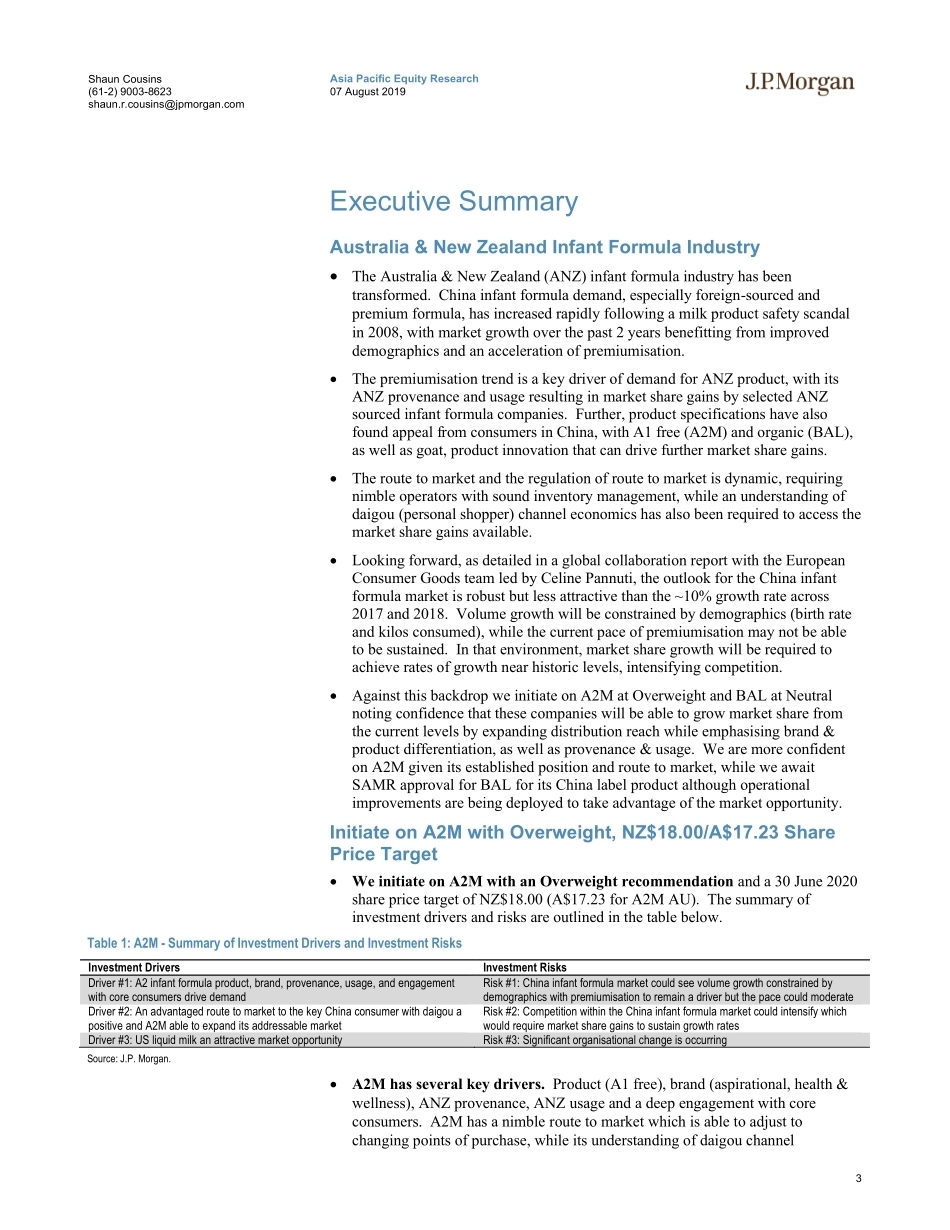
www.jpmorganmarkets.comAsia Pacific Equity Research07 August 2019Equity Ratings and Price TargetsMkt CapPriceRatingPrice TargetCompanyTicker($ mn)CCYPriceCurPrevCurEnd DatePrev End Datea2 Milk Company Ltd (ASX)A2M AU7,846.75AUD15.79OW—17.23Jun-20——a2 Milk Company Ltd (NZX)ATM NZ7,948.49NZD16.57OW—18.00Jun-20——Bellamy's Australia LtdBAL AU699.36AUD9.13N—9.50Jun-20——Source: Company data, Bloomberg, J.P. Morgan estimates. n/c = no change. All prices as of 07 Aug 19.ANZ Infant Formula IndustryProduct (A2, Organic), Brand, Usage and Provenance are Positives - Initiate on A2M (OW) and BAL (N)Australia, New ZealandAustralian Consumer SectorShaun Cousins AC(61-2) 9003-8623shaun.r.cousins@jpmorgan.comBloomberg JPMA COUSINS J.P. Morgan Securities Australia LimitedShalin J Doshi(91-22) 6157-3036shalin.doshi@jpmorgan.comJ.P. Morgan Securities Australia Limited/ J.P. Morgan India Private LimitedEuropean Consumer Goods and BeveragesCeline Pannuti, CFA(44-20) 7134-7123celine.pannuti@jpmorgan.comJ.P. Morgan Securities plcAnkur Gupta(91-22) 6157-5999ankur.x.gupta@jpmorgan.comJ.P. Morgan India Private LimitedSamuel Vialla(44-20) 7134-8804samuel.vialla@jpmorgan.comJ.P. Morgan Securities plcSee page 59 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.The ANZ infant formula industry has been transformed by China demand with attributes of product, brand, usage and provenance key drivers. Initiate on A2M at OW (PT NZ$18.00) as we are confident of further market share gains assisted by expanding its addressable market. Initiate on BAL at N (PT A$9.50) with business enhancement underpinning A$500m revenue ambition, yet execution risk remains. ANZ infant formula industry. The dramatic rise in demand from China has been transformational. The premiumisation trend is a key driver of demand for ANZ product, with its ANZ provenance and usage resulting in market share gains by selected ANZ sourced infant formula companies. Looking forward, as part of a global collaboration report with our European Consumer Goods team, we highlight the outlook for the China infant formula market is robust but less attractive than the ~10% growth rate across 2017 and 2018. A2M – drivers. Product (A1 free), brand (aspirational, health & wellness), ANZ provenance, ANZ usage and the deep engagement with core consumers are key demand drivers. A2M has a nimble route to market which is able to adjust to changing points of purchase, while its understanding of daigou channel economics is a competitive advantage. There are some increasing industry risks, but we are confident further market share gains will be achieved. A2Mcan expand its addressable market (geographically, greater MBS presence) and continued to perform well when competitors have entered the A2 category. A2M – Overweight. Despite share price outperformance, there is valuation support (DCF NZ$17.40) while the premium multiple is justified given the strong forecast revenue, EBITDA and EPS growth (3yr CAGR 23.2%). BAL – drivers. Product (predominantly organic, a fast growing category where BAL has sourcing capability), brand (known and trusted for organics) and Australian provenance. BAL has set a A$500m revenue ambition predicated on new branding & product formulation, new product development (including China-label, subject to SAMR approval) with these initiatives supported by investments in marketing and its China team. There are increasing industry risks, especially the desire from China for domestic production to grow to 60% (47% currently), which for BAL could impact the timing of SAMR approval. BAL – Neutral. There is modest valuation support (DCF A$9.03) and the prospect for P/E multiple expansion if earnings growth can be achieved. Yet we are cautious about the pace of multiple expansion given execution risk and the less established position which makes BAL more vulnerable to industry risks. 2Asia Pacific Equity Research07 August 2019Shaun Cousins(61-2) 9003-8623shaun.r.cousins@jpmorgan.comTable of ContentsExecutive Summary .................................................................3Australia & New Zealand Infant Formula Industry...................................................3Initiate on A2M with Overweight, NZ$18.00/A$17.23 Share Price Target ...............3Initiate on BAL with Neutral, A$9.50 Share Price Target.........................................4Valuation ................................................................................................................5A2 Milk Company Ltd...............................................................6Company Overview ..............................................




发表评论取消回复