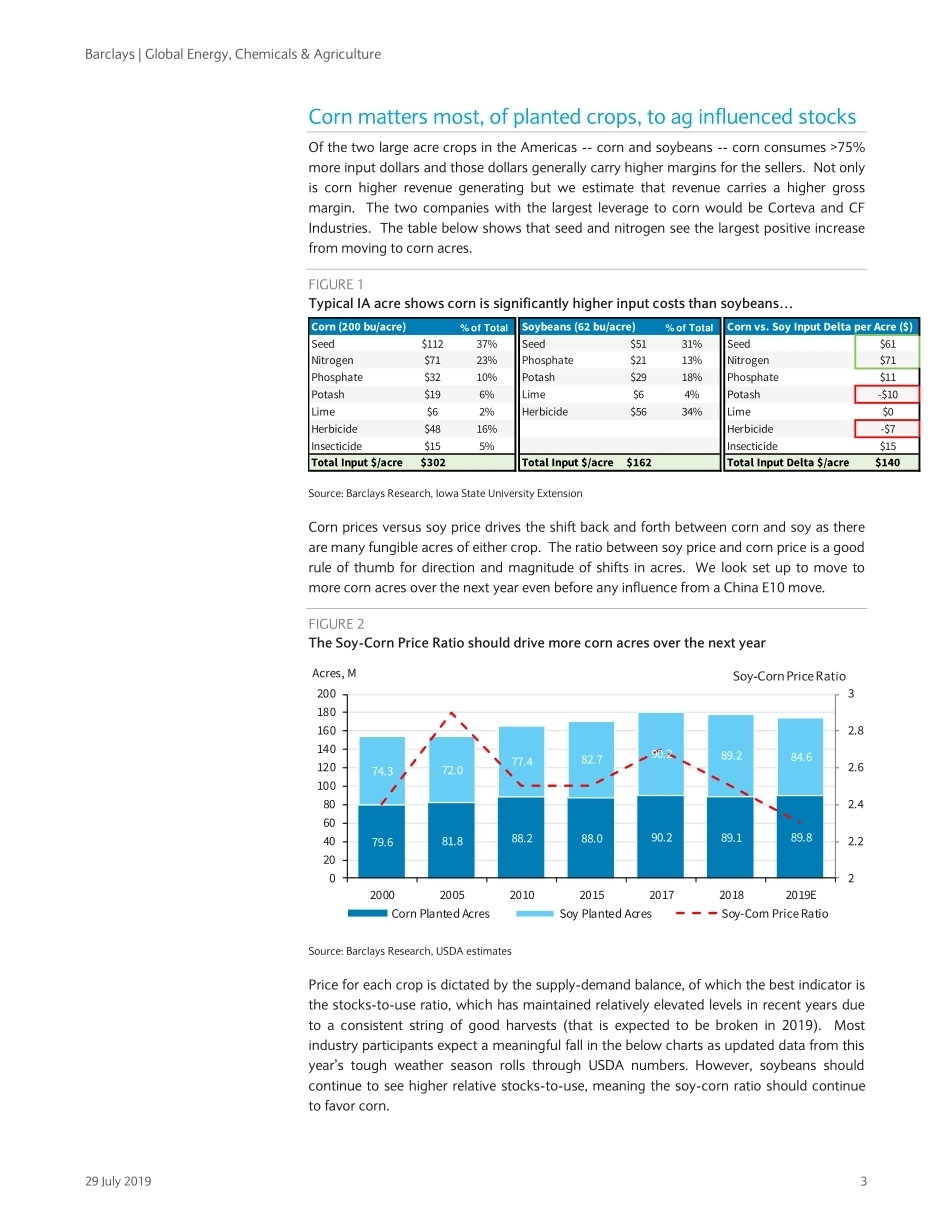
Equity Research 29 July 2019 FOCUS Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. This research report has been prepared in whole or in part by equity research analysts based outside the US who are not registered/qualified as research analysts with FINRA. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 27. Restricted - Internal Global Energy, Chemicals & Agriculture China E-10: Corn Boost, Round Two? Although current investor Ag focus is squarely on the challenging short-term weather-disrupted US dynamics, this report dives into an underappreciated opportunity: the potential corn-demand boost from China E10 biofuel adoption. Not only could this be significant, it is topical with the ongoing trade/tariff discussions, which could include a provision for accelerated Chinese E10 implementation (to the benefit of US corn players). In this report we provide an overview and potential implications, along with an illustrative scenario analyses for seed, fertilizer, energy, oxygenates, machinery and enzyme companies. Relevant companies: BAYN, CTVA, DE, CF, NTR, MOS, DD, NZYM (not covered), BASF. China already has a stated policy to mandate a 10% ethanol blend in its gasoline pool by 2020, reflecting the positive octane enhancement, chance to reduce dependence on energy imports and potential to utilize corn stockpiles. If realized, global Ag and Energy market impacts could be significant. The simple math for overall sizing purposes (not incremental): China’s 2018 gasoline demand was ~46bn gallons; a 10% ethanol blend would require ~4.6bn gallons of ethanol. One corn bushel produces ~3 gallons of ethanol, which implies ~1.6bn corn bushels needed to fulfill China’s entire 2018 need. This is equivalent to >9m U.S. corn acres. We lay out our bull/base/bear scenarios later in this report. There will likely be a portfolio approach to procuring this ethanol: a) Chinese ethanol from Chinese crops, b) Chinese ethanol from coal, c) US corn ethanol, and d) Brazilian sugar cane ethanol. While China is currently less than a fifth of the way to building the requisite ethanol production capacity, it does have several new plants under construction; so using supplementary US/Brazilian supply would be a logical bridge. Our base case would be an initial ~5% demand increase for US corn. An ag mini-cycle?: After 5+ years of a generally negative ag outlook, we can now see the potential for a mini ag upcycle. a) weather driving corn stocks-to-use down + b) corn prices higher driving more corn acres in 2020 + c) ASF pushing China to more poultry + cattle protein which consumes more western corn + d) new demand from Chinese corn ethanol = best corn (ag) outlook since drought of 2012. Who wins: a) Corn seed companies - With >30% US corn market share each, BAYN (Papadakis, OW PT€85) and CTVA (Fischer, EW PT$32) should see price and volume gains from a demand boost (corn seed revenue per acre is 2x soy), b) Fertilizer companies – Corn uses ~$70/acre more fertilizer than soy. CF (nitrogen) has more corn leverage than NTR or MOS. c) Ag Machinery companies d) Ethanol producers e) Enzyme companies should see an uptick in enzyme demand though Syngenta’s Enogen technology is causing some obsolescence in traditional enzyme products; Who loses: a) MTBE/Methanol producers – their product is displaced, b) Protein producers – fuel demand drives higher prices for their animal feed. . INDUSTRY UPDATE U.S. Chemicals POSITIVE Unchanged U.S. Chemicals Duffy Fischer +1 212 526 3212 duffy.fischer@barclays.com BCI, US European Pharmaceuticals Emmanuel Papadakis, PhD CFA +44 (0)20 3134 1246 emmanuel.papadakis@barclays.com Barclays, UK U.S. Machinery & Construction Adam Seiden, CFA +1 212 526 2212 adam.seiden@barclays.com BCI, US Americas Agribusiness Benjamin M. Theurer +52 55 5241 3322 benjamin.theurer@barclays.com BBMX, Mexico European Chemicals Sebastian Satz, CFA + 44 (0) 20 3134 7201 sebastian.satz@barclays.com Barclays, UK Alex Stewart, CFA +44 (0)20 3555 4957 alex.stewart@barclays.com Barclays, UK European Integrated Oil & Refining Lydia Rainforth, CFA +44 (0)20 3134 6669 lydia.rainforth@barclays.com Barclays, UK Barclays | Global Energy, Chemicals & Agriculture 29 July 2019 2 CONTENTS Corn matters most, of planted crops, to ag influenced stocks .......................................................... 3 China: Triangulating a potential policy move on E-10 ......................................................................... 5 How ethanol and corn can impact multiple industries: ....................................................................... 8 Potential Bull, Base, Bear Case Scenarios for Corn: ............




发表评论取消回复