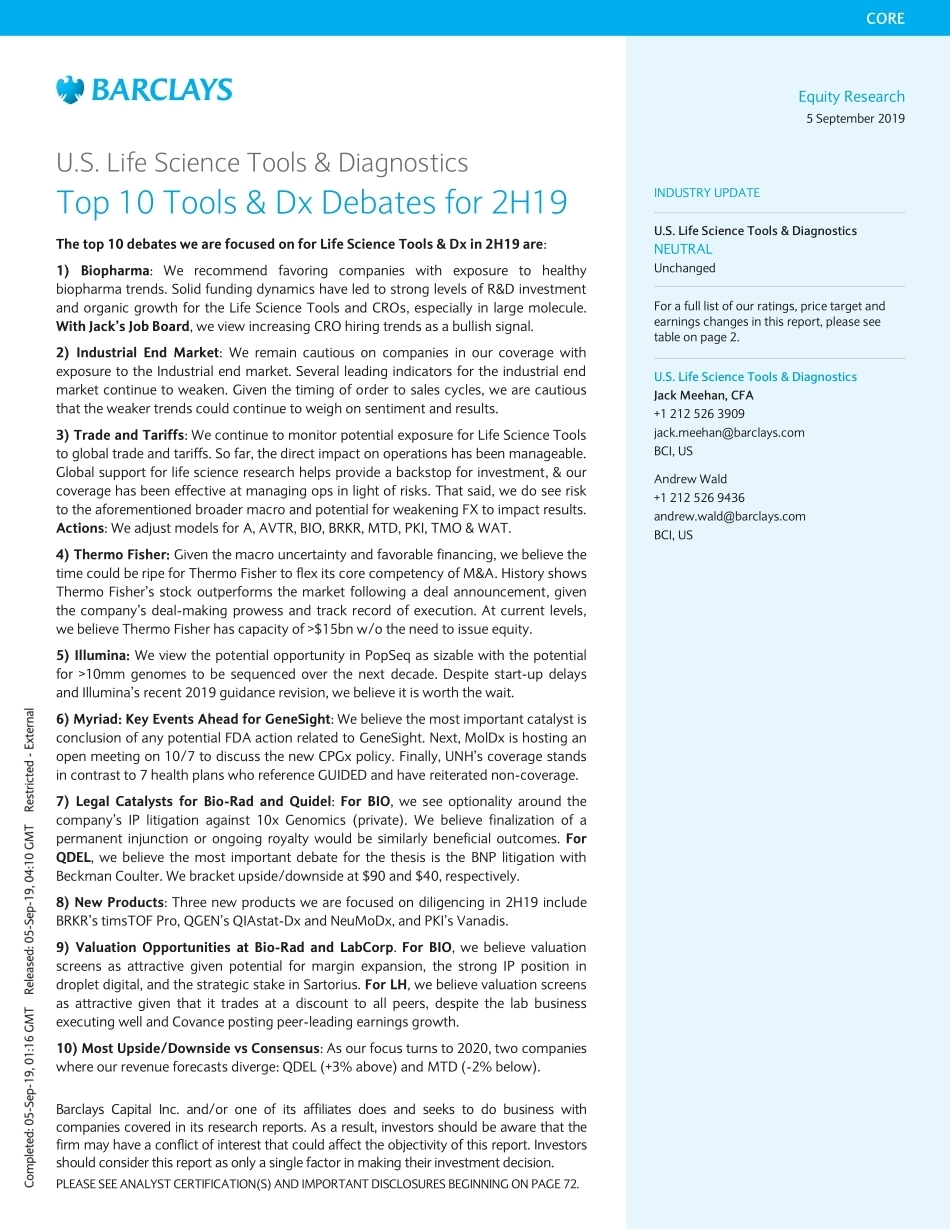
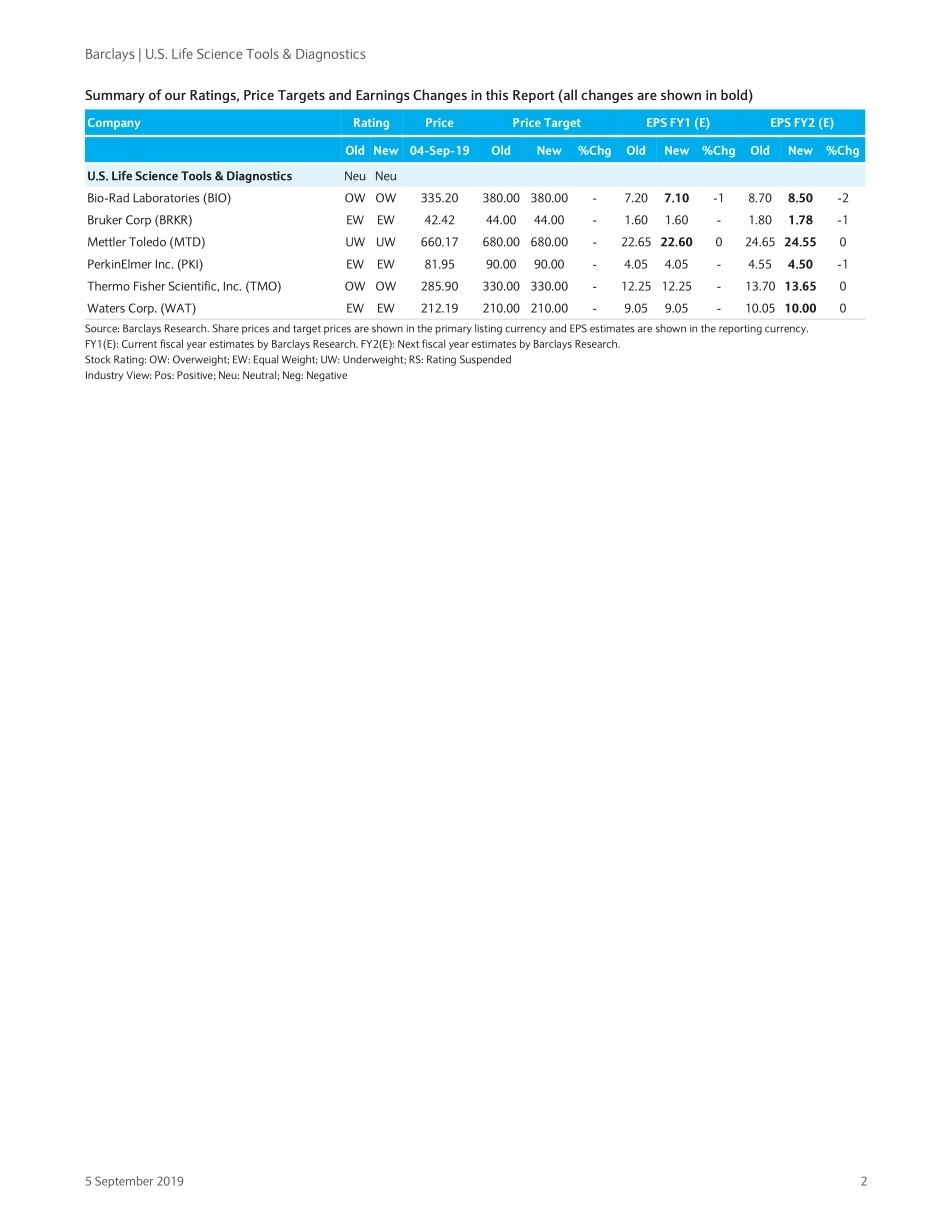
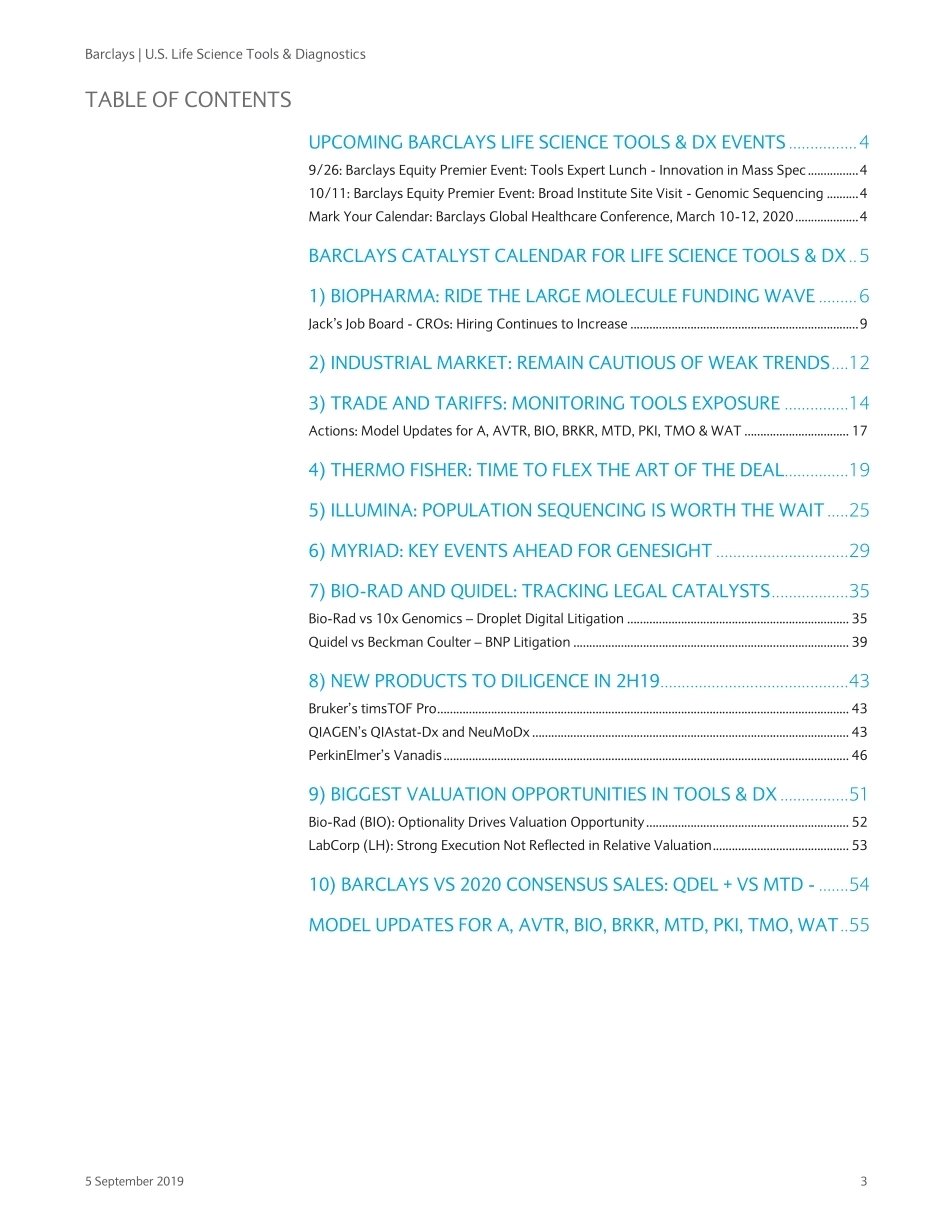
Equity Research 5 September 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 72. Restricted - Internal U.S. Life Science Tools & Diagnostics Top 10 Tools & Dx Debates for 2H19 The top 10 debates we are focused on for Life Science Tools & Dx in 2H19 are: 1) Biopharma: We recommend favoring companies with exposure to healthy biopharma trends. Solid funding dynamics have led to strong levels of R&D investment and organic growth for the Life Science Tools and CROs, especially in large molecule. With Jack’s Job Board, we view increasing CRO hiring trends as a bullish signal. 2) Industrial End Market: We remain cautious on companies in our coverage with exposure to the Industrial end market. Several leading indicators for the industrial end market continue to weaken. Given the timing of order to sales cycles, we are cautious that the weaker trends could continue to weigh on sentiment and results. 3) Trade and Tariffs: We continue to monitor potential exposure for Life Science Tools to global trade and tariffs. So far, the direct impact on operations has been manageable. Global support for life science research helps provide a backstop for investment, & our coverage has been effective at managing ops in light of risks. That said, we do see risk to the aforementioned broader macro and potential for weakening FX to impact results. Actions: We adjust models for A, AVTR, BIO, BRKR, MTD, PKI, TMO & WAT. 4) Thermo Fisher: Given the macro uncertainty and favorable financing, we believe the time could be ripe for Thermo Fisher to flex its core competency of M&A. History shows Thermo Fisher’s stock outperforms the market following a deal announcement, given the company’s deal-making prowess and track record of execution. At current levels, we believe Thermo Fisher has capacity of >$15bn w/o the need to issue equity. 5) Illumina: We view the potential opportunity in PopSeq as sizable with the potential for >10mm genomes to be sequenced over the next decade. Despite start-up delays and Illumina’s recent 2019 guidance revision, we believe it is worth the wait. 6) Myriad: Key Events Ahead for GeneSight: We believe the most important catalyst is conclusion of any potential FDA action related to GeneSight. Next, MolDx is hosting an open meeting on 10/7 to discuss the new CPGx policy. Finally, UNH’s coverage stands in contrast to 7 health plans who reference GUIDED and have reiterated non-coverage. 7) Legal Catalysts for Bio-Rad and Quidel: For BIO, we see optionality around the company’s IP litigation against 10x Genomics (private). We believe finalization of a permanent injunction or ongoing royalty would be similarly beneficial outcomes. For QDEL, we believe the most important debate for the thesis is the BNP litigation with Beckman Coulter. We bracket upside/downside at $90 and $40, respectively. 8) New Products: Three new products we are focused on diligencing in 2H19 include BRKR’s timsTOF Pro, QGEN’s QIAstat-Dx and NeuMoDx, and PKI’s Vanadis. 9) Valuation Opportunities at Bio-Rad and LabCorp. For BIO, we believe valuation screens as attractive given potential for margin expansion, the strong IP position in droplet digital, and the strategic stake in Sartorius. For LH, we believe valuation screens as attractive given that it trades at a discount to all peers, despite the lab business executing well and Covance posting peer-leading earnings growth. 10) Most Upside/Downside vs Consensus: As our focus turns to 2020, two companies where our revenue forecasts diverge: QDEL (+3% above) and MTD (-2% below). INDUSTRY UPDATE U.S. Life Science Tools & Diagnostics NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. Life Science Tools & Diagnostics Jack Meehan, CFA +1 212 526 3909 jack.meehan@barclays.com BCI, US Andrew Wald +1 212 526 9436 andrew.wald@barclays.com BCI, US Barclays | U.S. Life Science Tools & Diagnostics 5 September 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 04-Sep-19 Old New %Chg Old New %Chg Old New %Chg U.S. Life Science Tools & Diagnostics Neu Neu Bio-Rad Laboratories (BIO) OW OW 335.20 380.00 380.00 - 7.20 7.10 -1 8.70 8.50 -2 Bruker Corp (BRKR) EW EW 42.42 44.00 44.00 - 1.60 1.60 - 1.80 1.78 -1 Mettler Toledo (MTD) UW UW 660.17 680.00 680.00 - 22.65 22.60 0 24.65 24.55 0 PerkinElmer Inc. (PKI) EW EW 81.95 90.00 90.00 - 4.05 4.05 - 4.55 4.50 -1 Thermo Fisher Scientific, Inc. (TMO) OW OW 285.90 330.00 330....




发表评论取消回复