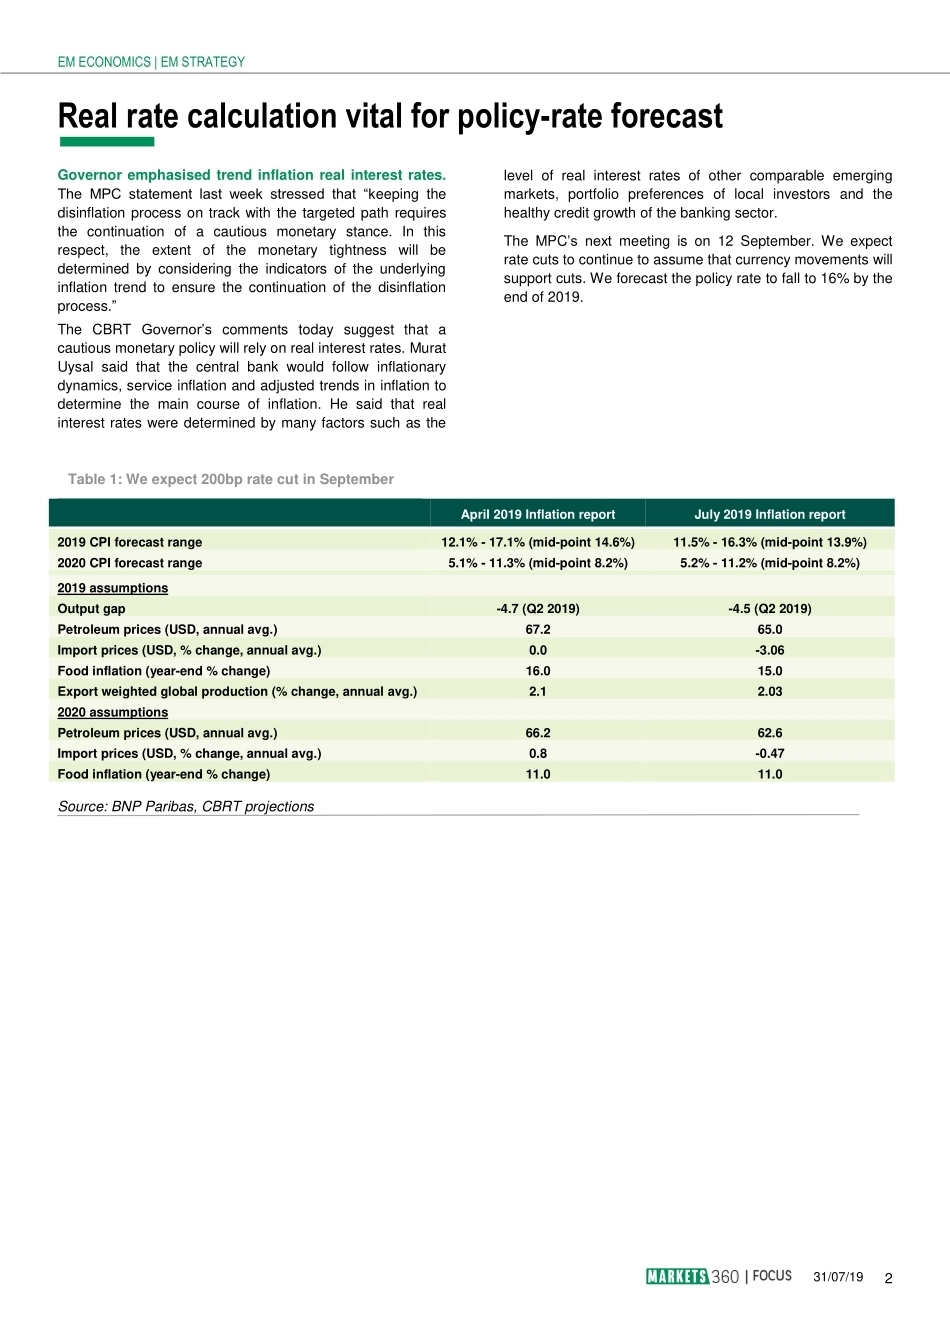
1 31/07/19 Hakan Aklar, Chief Economist | Turk Ekonomi Bank A.S.Turkey – Inflation report supports rate cutsKEY MESSAGES The Turkish central bank lowered its year-end 2019 CPI inflation forecast to 13.9% from 14.6%, by revising import, food and energy price forecasts downwards. The governor stressed adjusted inflation trends and real interest rates influenced the bank’s monetary policy stance. We expect year-end CPI inflation at 13.5% and expect further rate cuts, bringing policy rates to 16% by the end of the year. CPI inflation forecast for end-2019 falls to 13.9%. The new governor of the Central Bank of Turkey (CBRT), Murat Uysal, introduced the third inflation report of this year, revising the year-end CPI forecast from 14.6% to 13.9% (the mid-point of a range between 11.5% and 16.3%). The end-2019 inflation revision relied on lower import prices, a downward revision in food price inflation from 16% to 15% and average Brent oil prices from USD67.2/bbl to USD65/bbl (Table 1). The CBRT has kept 2020 and 2021 inflation forecasts unchanged at 8.2% and 5.4%, respectively. According to the CBRT’s latest expectations survey, the market expects 15% inflation at the end of 2019 and 13.9% in the 12-month. We revise our 2019 inflation forecast from 16% to 13.5%: The central bank’s Monetary Policy Committee (MPC) cut the 1-week lending rate by 425bp to 19.75% last week and sounded dovish, referring to a lower inflation trend in the coming months. In our note last week (Turkey – CBRT starts easing with 425bp policy rate cut, 25 July) we mentioned that risks to our 16% year-end CPI inflation forecast were to the downside. We now expect only a limited contribution to inflation from administered price adjustments thanks to the central bank’s profit transfers to the Treasury. In light of the high level of food inflation, we think a further downward correction in food prices is highly likely. Moreover, we expect less volatility in currency thanks to a more positive global backdrop. We think that 13.5% CPI inflation at the end of year is achievable. However, we expect CPI inflation to remain around this level in H1 2020, as a favourable base effect disappears then. Our expectation for 2020 CPI inflation is 11%. FOCUS | CEEMEA31 July 2019 Please refer to important information at the end of this reportEM ECONOMICS | EM STRATEGY MARKET VIEW We prefer long TRY relative value strategies and are also paid in 5Y XCCY, taking advantage of significant carry on both legs (see Turkey: Tactically long TRY and pay 5y rates, 2 July). In terms of what is priced into the curve into year-end, we think a policy rate of 16% is already in line with market expectations. 2 31/07/19 Hakan Aklar , Chief Economist | Turk Ekonomi Bank A.S. Real rate calculation vital for policy-rate forecast Governor emphasised trend inflation real interest rates. The MPC statement last week stressed that “keeping the disinflation process on track with the targeted path requires the continuation of a cautious monetary stance. In this respect, the extent of the monetary tightness will be determined by considering the indicators of the underlying inflation trend to ensure the continuation of the disinflation process.” The CBRT Governor’s comments today suggest that a cautious monetary policy will rely on real interest rates. Murat Uysal said that the central bank would follow inflationary dynamics, service inflation and adjusted trends in inflation to determine the main course of inflation. He said that real interest rates were determined by many factors such as the level of real interest rates of other comparable emerging markets, portfolio preferences of local investors and the healthy credit growth of the banking sector. The MPC’s next meeting is on 12 September. We expect rate cuts to continue to assume that currency movements will support cuts. We forecast the policy rate to fall to 16% by the end of 2019. April 2019 Inflation report July 2019 Inflation report 2019 CPI forecast range 12.1% - 17.1% (mid-point 14.6%) 11.5% - 16.3% (mid-point 13.9%) 2020 CPI forecast range 5.1% - 11.3% (mid-point 8.2%) 5.2% - 11.2% (mid-point 8.2%) 2019 assumptions Output gap -4.7 (Q2 2019) -4.5 (Q2 2019) Petroleum prices (USD, annual avg.) 67.2 65.0 Import prices (USD, % change, annual avg.) 0.0 -3.06 Food inflation (year-end % change) 16.0 15.0 Export weighted global production (% change, annual avg.) 2.1 2.03 2020 assumptions Petroleum prices (USD, annual avg.) 66.2 62.6 Import prices (USD, % change, annual avg.) 0.8 -0.47 Food inflation (year-end % change) 11.0 11.0 Source: BNP Paribas, CBRT projections EM ECONOMICS | EM STRATEGY Table 1: We expect 200bp rate cut in September 3 LEGAL NOTICE 31/07/19 This document has been written by our Strategist and Economist teams within the BNP Paribas group of companies (collectively “BNPP”); it does not purport to be an exhaustive analysis, and may be subject to conflicts of interest resulting from their interaction with sales and tradin...




发表评论取消回复