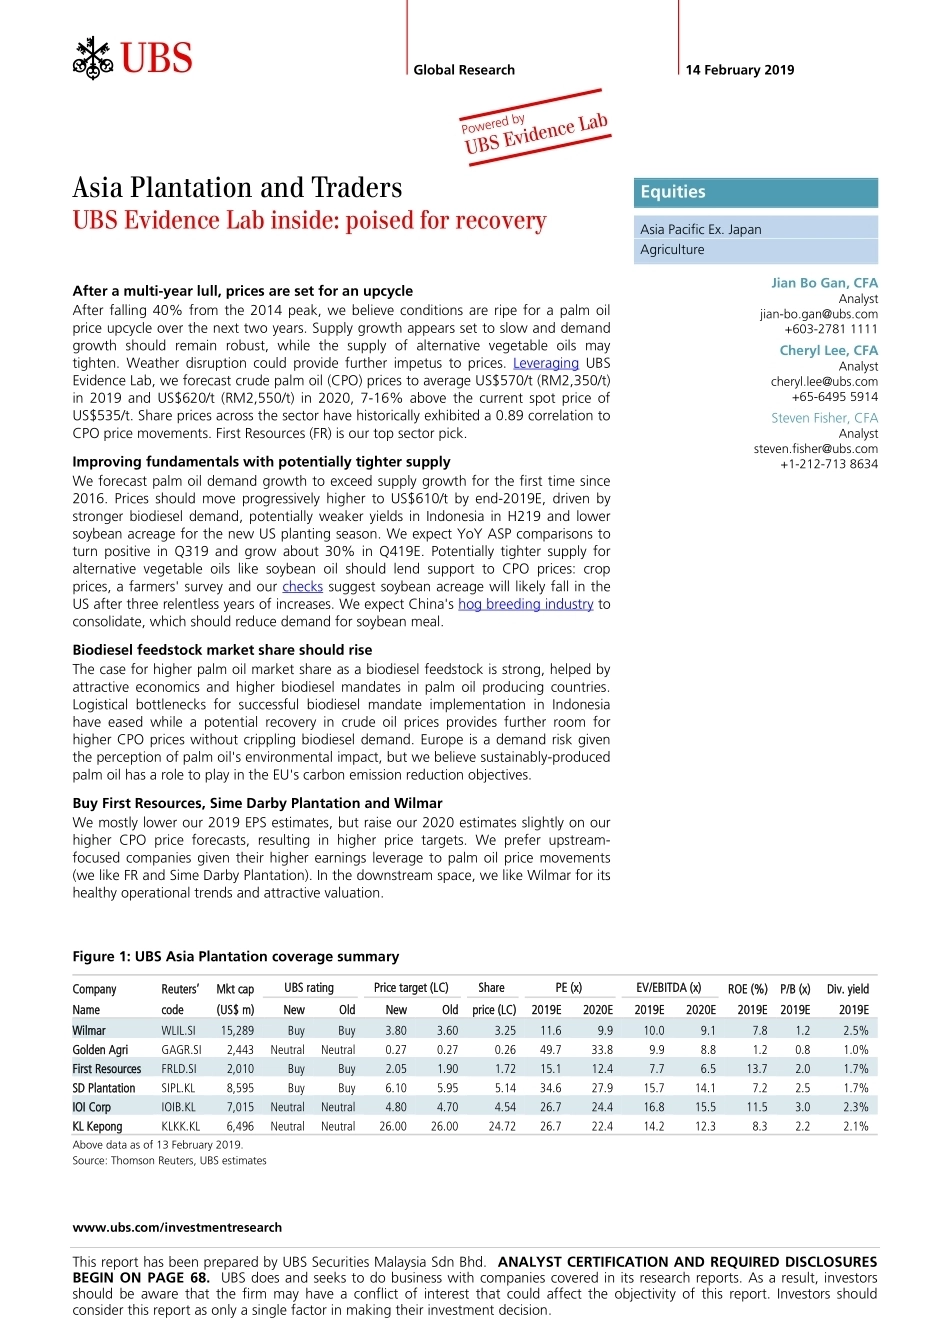
www.ubs.com/investmentresearch This report has been prepared by UBS Securities Malaysia Sdn Bhd. ANALYST CERTIFICATION AND REQUIRED DISCLOSURES BEGIN ON PAGE 68. UBS does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Global Research 14 February 2019 Asia Plantation and Traders UBS Evidence Lab inside: poised for recovery After a multi-year lull, prices are set for an upcycle After falling 40% from the 2014 peak, we believe conditions are ripe for a palm oil price upcycle over the next two years. Supply growth appears set to slow and demand growth should remain robust, while the supply of alternative vegetable oils may tighten. Weather disruption could provide further impetus to prices. Leveraging UBS Evidence Lab, we forecast crude palm oil (CPO) prices to average US$570/t (RM2,350/t) in 2019 and US$620/t (RM2,550/t) in 2020, 7-16% above the current spot price of US$535/t. Share prices across the sector have historically exhibited a 0.89 correlation to CPO price movements. First Resources (FR) is our top sector pick. Improving fundamentals with potentially tighter supply We forecast palm oil demand growth to exceed supply growth for the first time since 2016. Prices should move progressively higher to US$610/t by end-2019E, driven by stronger biodiesel demand, potentially weaker yields in Indonesia in H219 and lower soybean acreage for the new US planting season. We expect YoY ASP comparisons to turn positive in Q319 and grow about 30% in Q419E. Potentially tighter supply for alternative vegetable oils like soybean oil should lend support to CPO prices: crop prices, a farmers' survey and our checks suggest soybean acreage will likely fall in the US after three relentless years of increases. We expect China's hog breeding industry to consolidate, which should reduce demand for soybean meal. Biodiesel feedstock market share should rise The case for higher palm oil market share as a biodiesel feedstock is strong, helped by attractive economics and higher biodiesel mandates in palm oil producing countries. Logistical bottlenecks for successful biodiesel mandate implementation in Indonesia have eased while a potential recovery in crude oil prices provides further room for higher CPO prices without crippling biodiesel demand. Europe is a demand risk given the perception of palm oil's environmental impact, but we believe sustainably-produced palm oil has a role to play in the EU's carbon emission reduction objectives. Buy First Resources, Sime Darby Plantation and Wilmar We mostly lower our 2019 EPS estimates, but raise our 2020 estimates slightly on our higher CPO price forecasts, resulting in higher price targets. We prefer upstream-focused companies given their higher earnings leverage to palm oil price movements (we like FR and Sime Darby Plantation). In the downstream space, we like Wilmar for its healthy operational trends and attractive valuation. Figure 1: UBS Asia Plantation coverage summary Company Reuters’ Mkt cap UBS rating Price target (LC) Share PE (x) EV/EBITDA (x) ROE (%) P/B (x) Div. yield Name code (US$ m) New Old New Old price (LC) 2019E 2020E 2019E 2020E 2019E 2019E 2019E Wilmar WLIL.SI 15,289 Buy Buy 3.80 3.60 3.25 11.6 9.9 10.0 9.1 7.8 1.2 2.5% Golden Agri GAGR.SI 2,443 Neutral Neutral 0.27 0.27 0.26 49.7 33.8 9.9 8.8 1.2 0.8 1.0% First Resources FRLD.SI 2,010 Buy Buy 2.05 1.90 1.72 15.1 12.4 7.7 6.5 13.7 2.0 1.7% SD Plantation SIPL.KL 8,595 Buy Buy 6.10 5.95 5.14 34.6 27.9 15.7 14.1 7.2 2.5 1.7% IOI Corp IOIB.KL 7,015 Neutral Neutral 4.80 4.70 4.54 26.7 24.4 16.8 15.5 11.5 3.0 2.3% KL Kepong KLKK.KL 6,496 Neutral Neutral 26.00 26.00 24.72 26.7 22.4 14.2 12.3 8.3 2.2 2.1% Above data as of 13 February 2019. Source: Thomson Reuters, UBS estimates Equities Asia Pacific Ex. Japan Agriculture Jian Bo Gan, CFA Analyst jian-bo.gan@ubs.com +603-2781 1111 Cheryl Lee, CFA Analyst cheryl.lee@ubs.com +65-6495 5914 Steven Fisher, CFA Analyst steven.fisher@ubs.com +1-212-713 8634 Asia Plantation and Traders 14 February 2019 2 Contents OUR THESIS IN PICTURES .................................................................... 4 PLANTERS AT A GLANCE .................................................................... 5 PIVOTAL QUESTIONS ........................................................................... 6 Q: Will palm oil prices rise in 2019-20? ........................................................ 6 Q: Will palm oil's market share as a biodiesel feedstock increase in 2019-20? .................................................................................................................. 14 Q: Will production growth of alternative vegetable oils decelerate in 2019-20? .....................................................................




发表评论取消回复