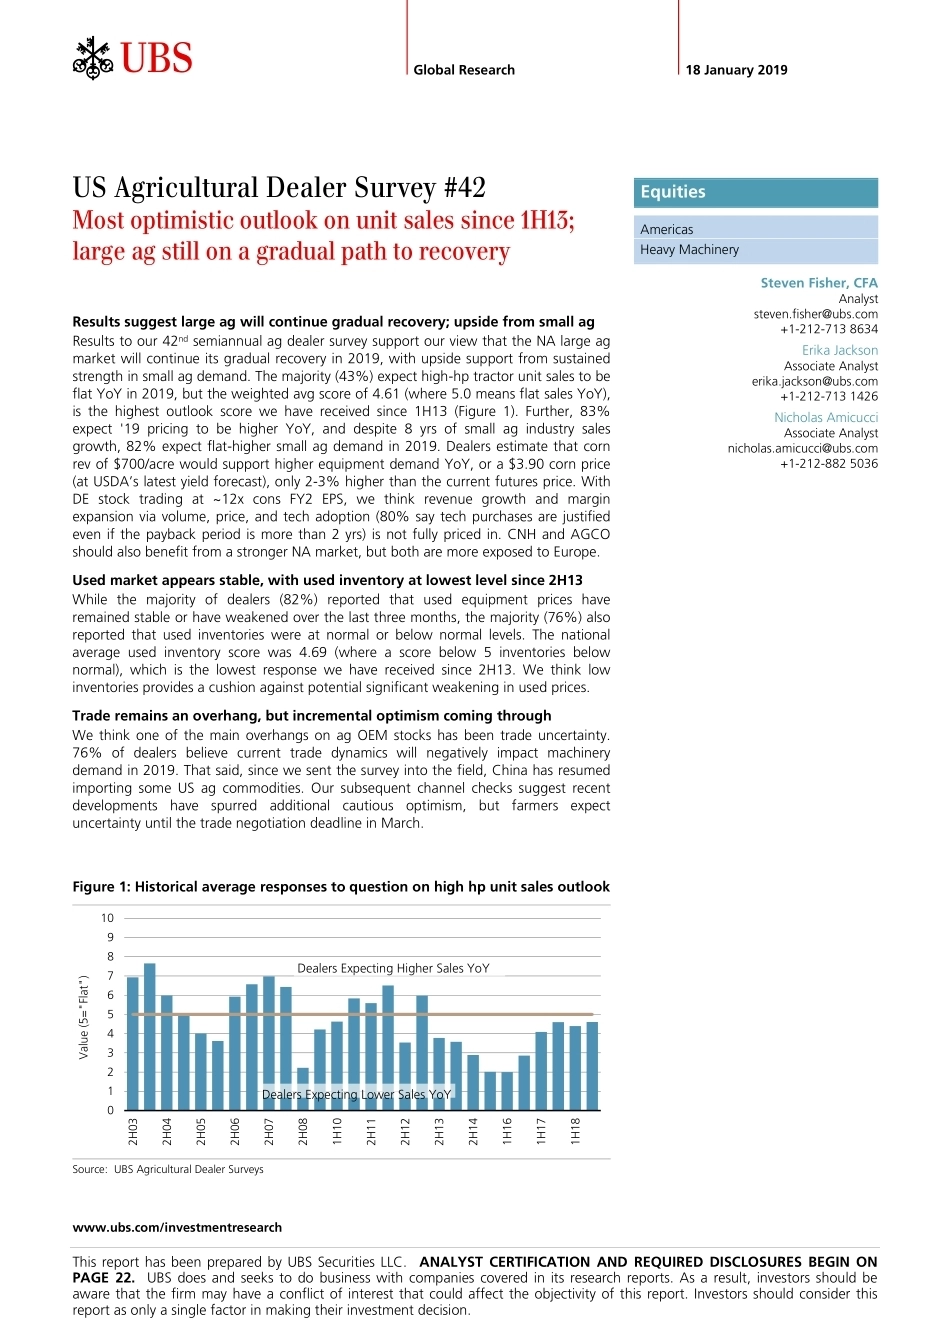
www.ubs.com/investmentresearch This report has been prepared by UBS Securities LLC. ANALYST CERTIFICATION AND REQUIRED DISCLOSURES BEGIN ON PAGE 22. UBS does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Global Research 18 January 2019 US Agricultural Dealer Survey #42 Most optimistic outlook on unit sales since 1H13; large ag still on a gradual path to recovery Results suggest large ag will continue gradual recovery; upside from small ag Results to our 42nd semiannual ag dealer survey support our view that the NA large ag market will continue its gradual recovery in 2019, with upside support from sustained strength in small ag demand. The majority (43%) expect high-hp tractor unit sales to be flat YoY in 2019, but the weighted avg score of 4.61 (where 5.0 means flat sales YoY), is the highest outlook score we have received since 1H13 (Figure 1). Further, 83% expect '19 pricing to be higher YoY, and despite 8 yrs of small ag industry sales growth, 82% expect flat-higher small ag demand in 2019. Dealers estimate that corn rev of $700/acre would support higher equipment demand YoY, or a $3.90 corn price (at USDA’s latest yield forecast), only 2-3% higher than the current futures price. With DE stock trading at ~12x cons FY2 EPS, we think revenue growth and margin expansion via volume, price, and tech adoption (80% say tech purchases are justified even if the payback period is more than 2 yrs) is not fully priced in. CNH and AGCO should also benefit from a stronger NA market, but both are more exposed to Europe. Used market appears stable, with used inventory at lowest level since 2H13 While the majority of dealers (82%) reported that used equipment prices have remained stable or have weakened over the last three months, the majority (76%) also reported that used inventories were at normal or below normal levels. The national average used inventory score was 4.69 (where a score below 5 inventories below normal), which is the lowest response we have received since 2H13. We think low inventories provides a cushion against potential significant weakening in used prices. Trade remains an overhang, but incremental optimism coming through We think one of the main overhangs on ag OEM stocks has been trade uncertainty. 76% of dealers believe current trade dynamics will negatively impact machinery demand in 2019. That said, since we sent the survey into the field, China has resumed importing some US ag commodities. Our subsequent channel checks suggest recent developments have spurred additional cautious optimism, but farmers expect uncertainty until the trade negotiation deadline in March. Figure 1: Historical average responses to question on high hp unit sales outlook Source: UBS Agricultural Dealer Surveys 0123456789102H032H042H052H062H072H081H102H112H122H132H141H161H171H18Value (5="Flat") Dealers Expecting Higher Sales YoY Dealers Expecting Lower Sales YoY Equities Americas Heavy Machinery Steven Fisher, CFA Analyst steven.fisher@ubs.com +1-212-713 8634 Erika Jackson Associate Analyst erika.jackson@ubs.com +1-212-713 1426 Nicholas Amicucci Associate Analyst nicholas.amicucci@ubs.com +1-212-882 5036 US Agricultural Dealer Survey #42 18 January 2019 2 Contents Executive Summary .......................................................................... 3 Topic 1: 2019 demand outlook ........................................................ 5 High-horsepower tractors (140hp+) – flat to down ...................................... 5 Low-horsepower tractors (under 140hp) – flat to up .................................... 6 Combines – flat to down ............................................................................. 7 Combine early order programs are flattish ................................................... 8 Moderate risk of cancellations ..................................................................... 9 Pricing expected to be higher in 2019 ........................................................ 10 Topic 2: Farmer fundamentals / demand drivers ......................... 11 Customer business confidence is weaker than last year ............................. 11 Customers not motivated to replace equipment at current grain prices ...... 12 2% and 16% higher corn and soybean prices needed to support higher equipment demand ................................................................................... 13 Current trade dynamics expected to have a negative impact on equipment demand in 2019 ........................................................................................ 15 Farmers would justify technology purchases even if payback period is longer than 2 years ....................................................................................




发表评论取消回复