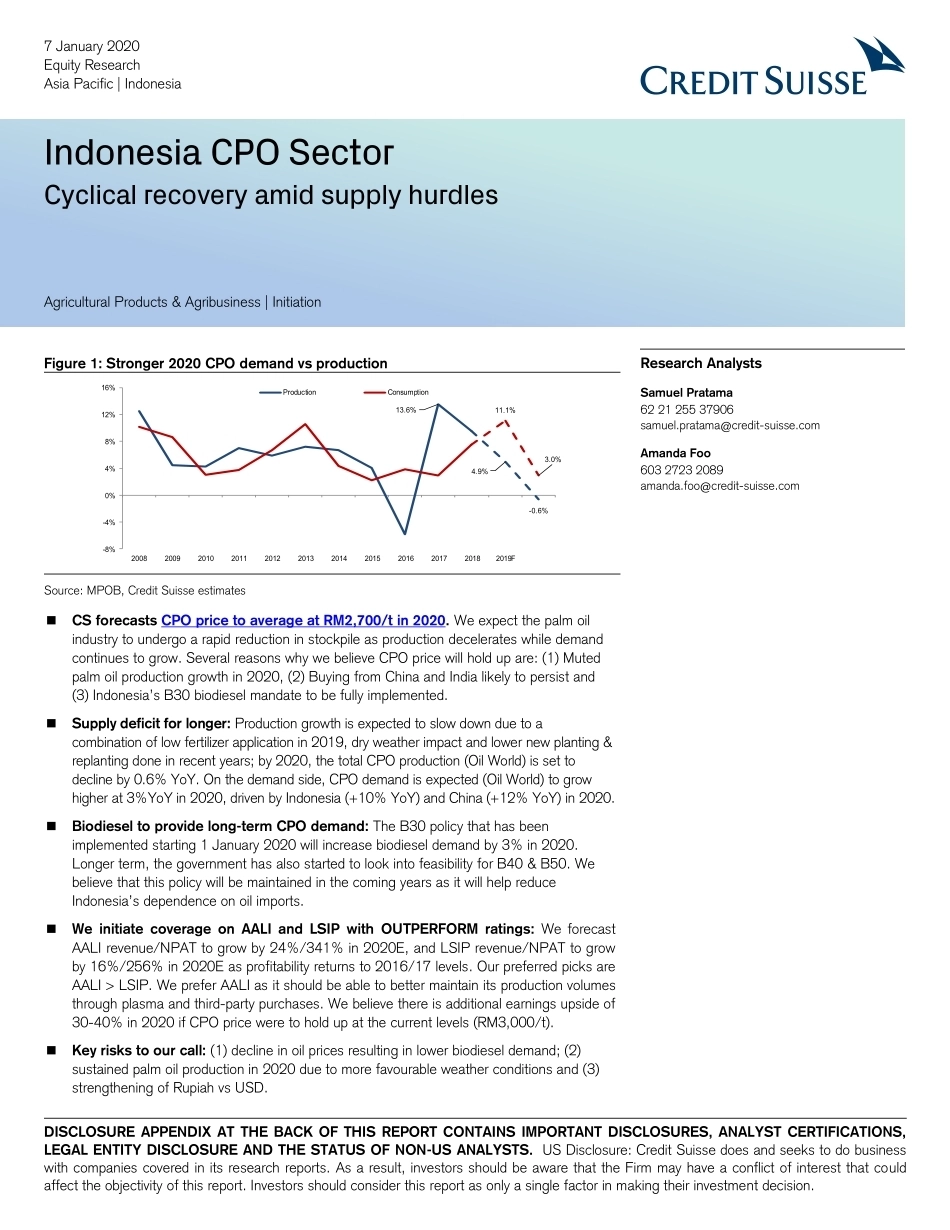
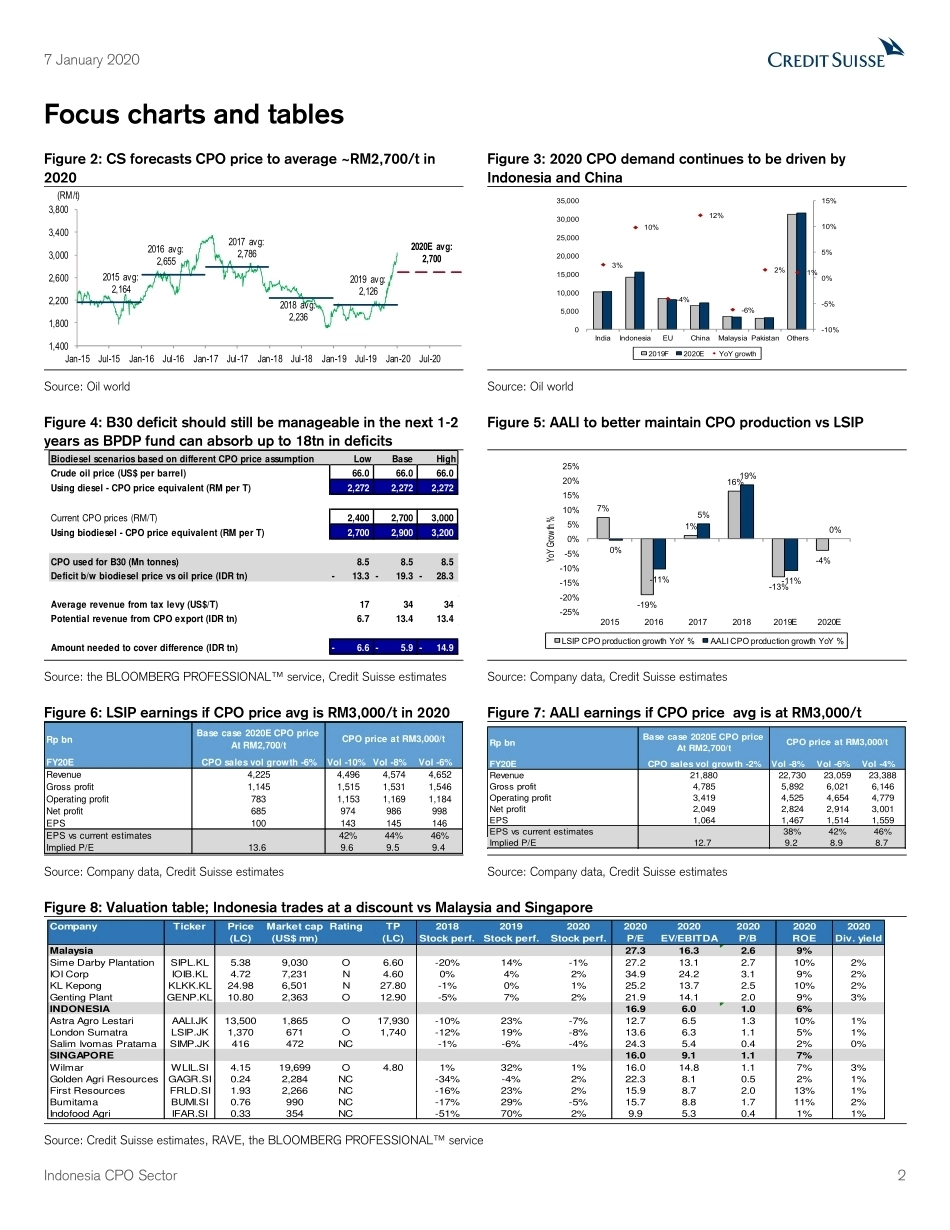
Indonesia CPO Sector Cyclical recovery amid supply hurdles Agricultural Products & Agribusiness | Initiation Figure 1: Stronger 2020 CPO demand vs production Source: MPOB, Credit Suisse estimates ■ CS forecasts CPO price to average at RM2,700/t in 2020. We expect the palm oil industry to undergo a rapid reduction in stockpile as production decelerates while demand continues to grow. Several reasons why we believe CPO price will hold up are: (1) Muted palm oil production growth in 2020, (2) Buying from China and India likely to persist and (3) Indonesia’s B30 biodiesel mandate to be fully implemented. ■ Supply deficit for longer: Production growth is expected to slow down due to a combination of low fertilizer application in 2019, dry weather impact and lower new planting & replanting done in recent years; by 2020, the total CPO production (Oil World) is set to decline by 0.6% YoY. On the demand side, CPO demand is expected (Oil World) to grow higher at 3%YoY in 2020, driven by Indonesia (+10% YoY) and China (+12% YoY) in 2020. ■ Biodiesel to provide long-term CPO demand: The B30 policy that has been implemented starting 1 January 2020 will increase biodiesel demand by 3% in 2020. Longer term, the government has also started to look into feasibility for B40 & B50. We believe that this policy will be maintained in the coming years as it will help reduce Indonesia’s dependence on oil imports. ■ We initiate coverage on AALI and LSIP with OUTPERFORM ratings: We forecast AALI revenue/NPAT to grow by 24%/341% in 2020E, and LSIP revenue/NPAT to grow by 16%/256% in 2020E as profitability returns to 2016/17 levels. Our preferred picks are AALI > LSIP. We prefer AALI as it should be able to better maintain its production volumes through plasma and third-party purchases. We believe there is additional earnings upside of 30-40% in 2020 if CPO price were to hold up at the current levels (RM3,000/t). ■ Key risks to our call: (1) decline in oil prices resulting in lower biodiesel demand; (2) sustained palm oil production in 2020 due to more favourable weather conditions and (3) strengthening of Rupiah vs USD. 13.6%4.9%-0.6%11.1%3.0%-8%-4%0%4%8%12%16%200820092010201120122013201420152016201720182019FProductionConsumption7 January 2020 Equity Research Asia Pacific | Indonesia DISCLOSURE APPENDIX AT THE BACK OF THIS REPORT CONTAINS IMPORTANT DISCLOSURES, ANALYST CERTIFICATIONS, LEGAL ENTITY DISCLOSURE AND THE STATUS OF NON-US ANALYSTS. US Disclosure: Credit Suisse does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the Firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Research Analysts Samuel Pratama 62 21 255 37906 samuel.pratama@credit-suisse.com Amanda Foo 603 2723 2089 amanda.foo@credit-suisse.com 7 January 2020 Indonesia CPO Sector 2 Focus charts and tables Figure 2: CS forecasts CPO price to average ~RM2,700/t in 2020 Figure 3: 2020 CPO demand continues to be driven by Indonesia and China Source: Oil world Source: Oil world Figure 4: B30 deficit should still be manageable in the next 1-2 years as BPDP fund can absorb up to 18tn in deficits Figure 5: AALI to better maintain CPO production vs LSIP Source: the BLOOMBERG PROFESSIONAL™ service, Credit Suisse estimates Source: Company data, Credit Suisse estimates Figure 6: LSIP earnings if CPO price avg is RM3,000/t in 2020 Figure 7: AALI earnings if CPO price avg is at RM3,000/t Source: Company data, Credit Suisse estimates Source: Company data, Credit Suisse estimates Figure 8: Valuation table; Indonesia trades at a discount vs Malaysia and Singapore Source: Credit Suisse estimates, RAVE, the BLOOMBERG PROFESSIONAL™ service 2020E avg:2,7002015 avg:2,1642016 avg:2,6552017 avg:2,7862018 avg:2,2362019 avg:2,1261,4001,8002,2002,6003,0003,4003,800Jan-15Jul-15Jan-16Jul-16Jan-17Jul-17Jan-18Jul-18Jan-19Jul-19Jan-20Jul-20(RM/t)3%10%-4%12%-6%2%1%-10%-5%0%5%10%15%05,00010,00015,00020,00025,00030,00035,000IndiaIndonesiaEUChinaMalaysia PakistanOthers2019F2020EYoY growthBiodiesel scenarios based on different CPO price assumptionLowBaseHighCrude oil price (US$ per barrel)66.0 66.0 66.0 Using diesel - CPO price equivalent (RM per T)2,272 2,272 2,272 Current CPO prices (RM/T)2,400 2,700 3,000 Using biodiesel - CPO price equivalent (RM per T) 2,700 2,900 3,200 CPO used for B30 (Mn tonnes)8.5 8.5 8.5 Deficit b/w biodiesel price vs oil price (IDR tn)13.3- 19.3- 28.3- Average revenue from tax levy (US$/T)17 34 34 Potential revenue from CPO export (IDR tn)6.7 13.4 13.4 Amount needed to cover difference (IDR tn)6.6- 5.9- 14.9- 7%-19%1%16%-13%-4%0%-11%5%19%-11%0%-25%-20%-15%-10%-5%0%5%10%15%20%25%20152016201720182019E2020EYoY Growth %LSIP CPO production growth YoY %AALI CPO production growth YoY %Rp bnBase case 2020E CPO price At RM2,700/tFY20ECPO sales vol growth -6%Vol -10% Vol -8%Vol -6%Reven...




发表评论取消回复