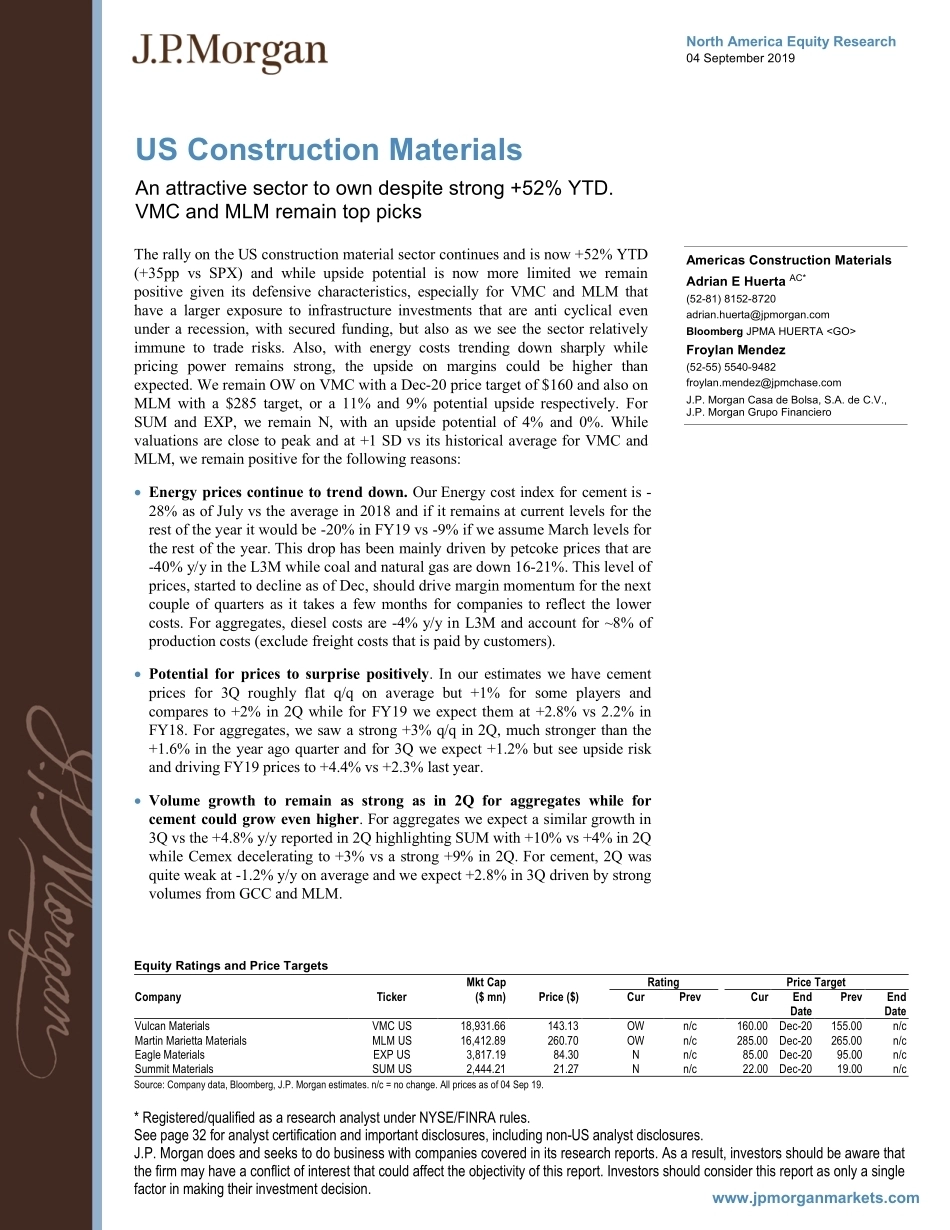
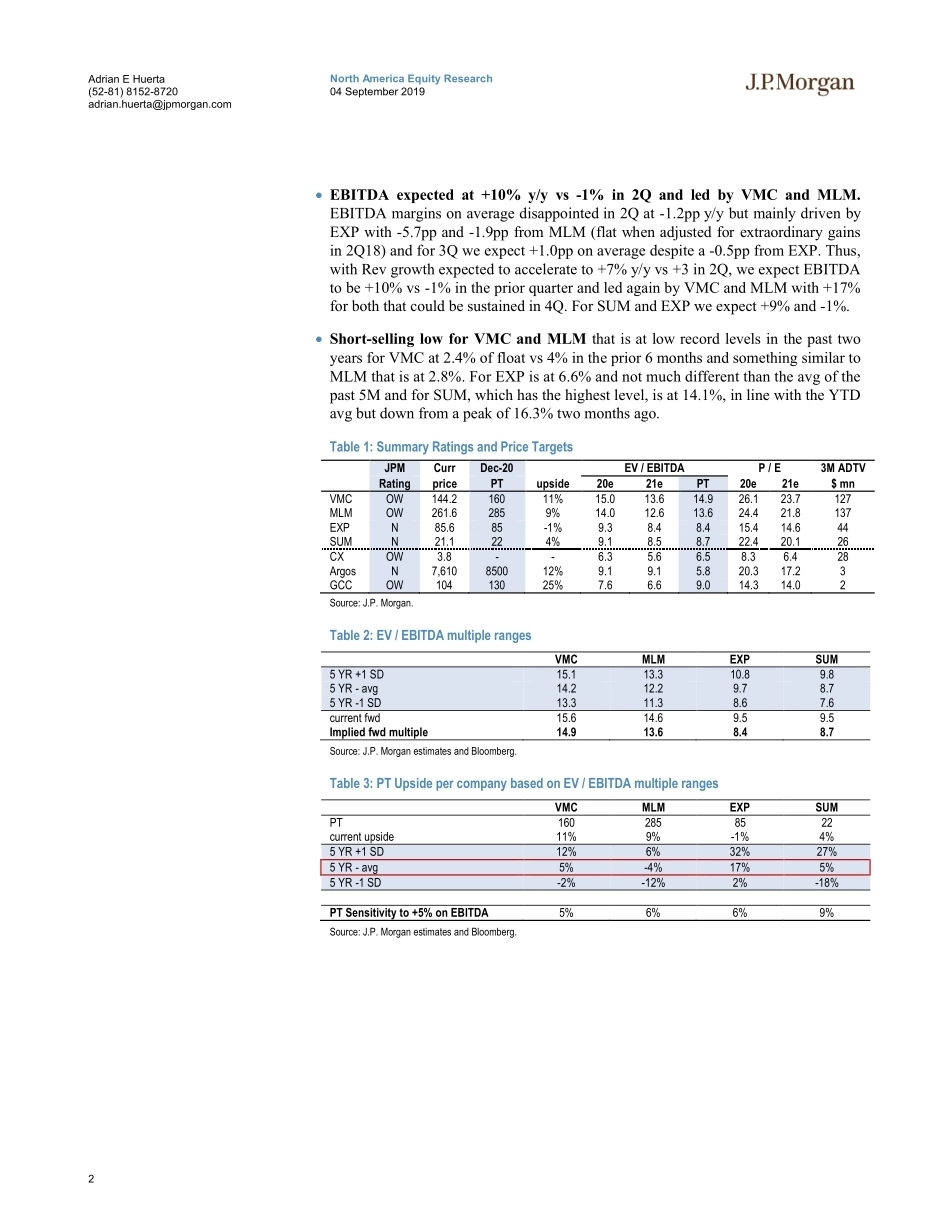
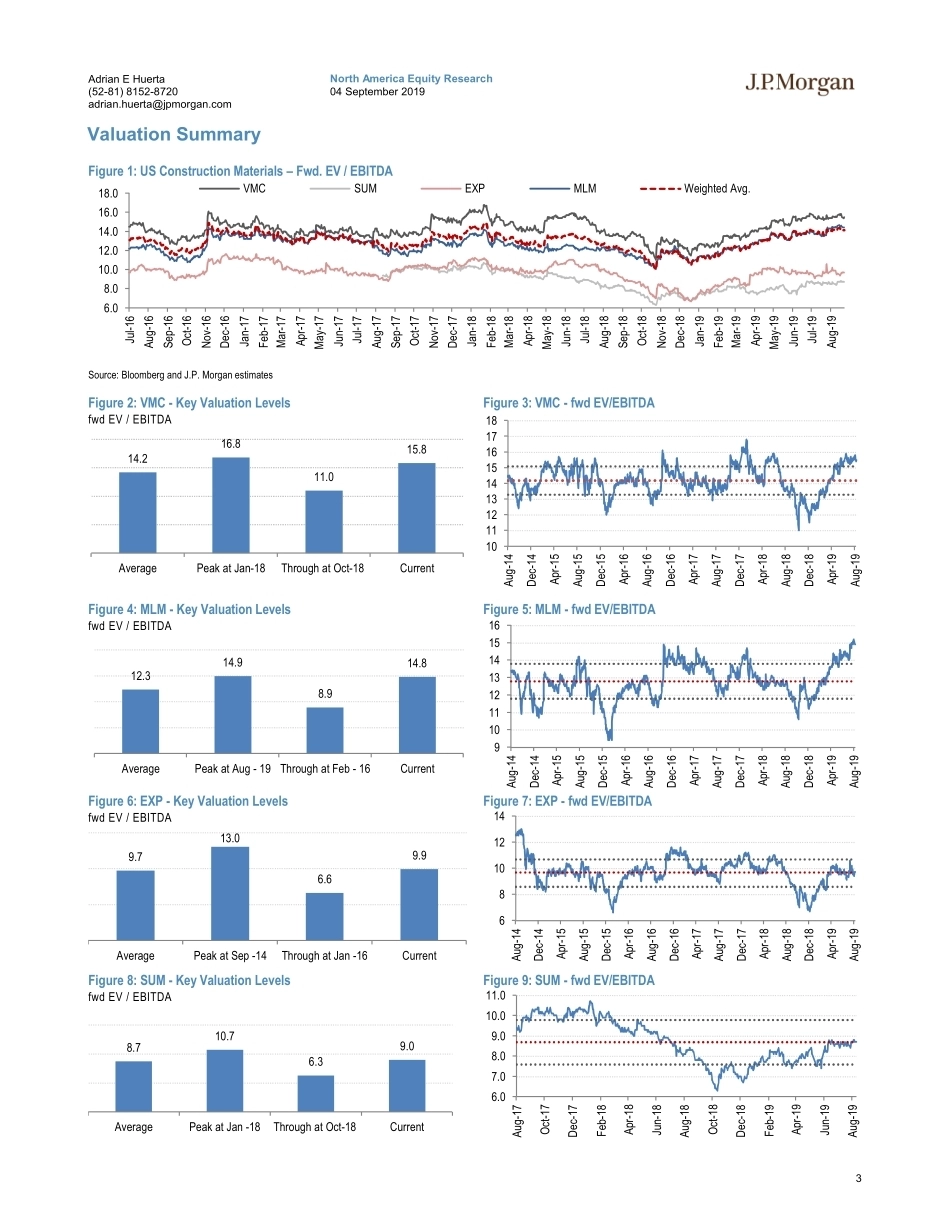
www.jpmorganmarkets.comNorth America Equity Research04 September 2019Equity Ratings and Price TargetsMkt CapRatingPrice TargetCompanyTicker($ mn)Price ($)CurPrevCurEnd DatePrevEnd DateVulcan MaterialsVMC US18,931.66143.13OWn/c160.00Dec-20155.00n/cMartin Marietta MaterialsMLM US16,412.89260.70OWn/c285.00Dec-20265.00n/cEagle MaterialsEXP US3,817.1984.30Nn/c85.00Dec-2095.00n/cSummit MaterialsSUM US2,444.2121.27Nn/c22.00Dec-2019.00n/cSource: Company data, Bloomberg, J.P. Morgan estimates. n/c = no change. All prices as of 04 Sep 19.US Construction MaterialsAn attractive sector to own despite strong +52% YTD. VMC and MLM remain top picks Americas Construction MaterialsAdrian E Huerta AC*(52-81) 8152-8720adrian.huerta@jpmorgan.comBloomberg JPMA HUERTA Froylan Mendez(52-55) 5540-9482froylan.mendez@jpmchase.comJ.P. Morgan Casa de Bolsa, S.A. de C.V., J.P. Morgan Grupo Financiero* Registered/qualified as a research analyst under NYSE/FINRA rules.See page 32 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.The rally on the US construction material sector continues and is now +52% YTD (+35pp vs SPX) and while upside potential is now more limited we remain positive given its defensive characteristics, especially for VMC and MLM that have a larger exposure to infrastructure investments that are anti cyclical even under a recession, with secured funding, but also as we see the sector relatively immune to trade risks. Also, with energy costs trending down sharply while pricing power remains strong, the upside on margins could be higher than expected. We remain OW on VMC with a Dec-20 price target of $160 and also on MLM with a $285 target, or a 11% and 9% potential upside respectively. For SUM and EXP, we remain N, with an upside potential of 4% and 0%. While valuations are close to peak and at +1 SD vs its historical average for VMC and MLM, we remain positive for the following reasons: Energy prices continue to trend down. Our Energy cost index for cement is -28% as of July vs the average in 2018 and if it remains at current levels for the rest of the year it would be -20% in FY19 vs -9% if we assume March levels for the rest of the year. This drop has been mainly driven by petcoke prices that are -40% y/y in the L3M while coal and natural gas are down 16-21%. This level of prices, started to decline as of Dec, should drive margin momentum for the next couple of quarters as it takes a few months for companies to reflect the lower costs. For aggregates, diesel costs are -4% y/y in L3M and account for ~8% of production costs (exclude freight costs that is paid by customers). Potential for prices to surprise positively. In our estimates we have cement prices for 3Q roughly flat q/q on average but +1% for some players and compares to +2% in 2Q while for FY19 we expect them at +2.8% vs 2.2% in FY18. For aggregates, we saw a strong +3% q/q in 2Q, much stronger than the +1.6% in the year ago quarter and for 3Q we expect +1.2% but see upside riskand driving FY19 prices to +4.4% vs +2.3% last year. Volume growth to remain as strong as in 2Q for aggregates while for cement could grow even higher. For aggregates we expect a similar growth in 3Q vs the +4.8% y/y reported in 2Q highlighting SUM with +10% vs +4% in 2Q while Cemex decelerating to +3% vs a strong +9% in 2Q. For cement, 2Q was quite weak at -1.2% y/y on average and we expect +2.8% in 3Q driven by strong volumes from GCC and MLM.2North America Equity Research04 September 2019Adrian E Huerta(52-81) 8152-8720adrian.huerta@jpmorgan.com EBITDA expected at +10% y/y vs -1% in 2Q and led by VMC and MLM. EBITDA margins on average disappointed in 2Q at -1.2pp y/y but mainly driven by EXP with -5.7pp and -1.9pp from MLM (flat when adjusted for extraordinary gains in 2Q18) and for 3Q we expect +1.0pp on average despite a -0.5pp from EXP. Thus, with Rev growth expected to accelerate to +7% y/y vs +3 in 2Q, we expect EBITDA to be +10% vs -1% in the prior quarter and led again by VMC and MLM with +17% for both that could be sustained in 4Q. For SUM and EXP we expect +9% and -1%. Short-selling low for VMC and MLM that is at low record levels in the past two years for VMC at 2.4% of float vs 4% in the prior 6 months and something similar to MLM that is at 2.8%. For EXP is at 6.6% and not much different than the avg of the past 5M and for SUM, which has the highest level, is at 14.1%, in line with the YTD avg but down from a peak of 16.3% two months ago.Table 1: Summary Ratings and Price TargetsJPMCurrDec-20EV / EBITDAP / E3M ADTVRatingpricePTupside20e21ePT20e21e$ mnVMC OW144.216011%15.013.614.926.123.7127MLM OW261.62859%...




发表评论取消回复