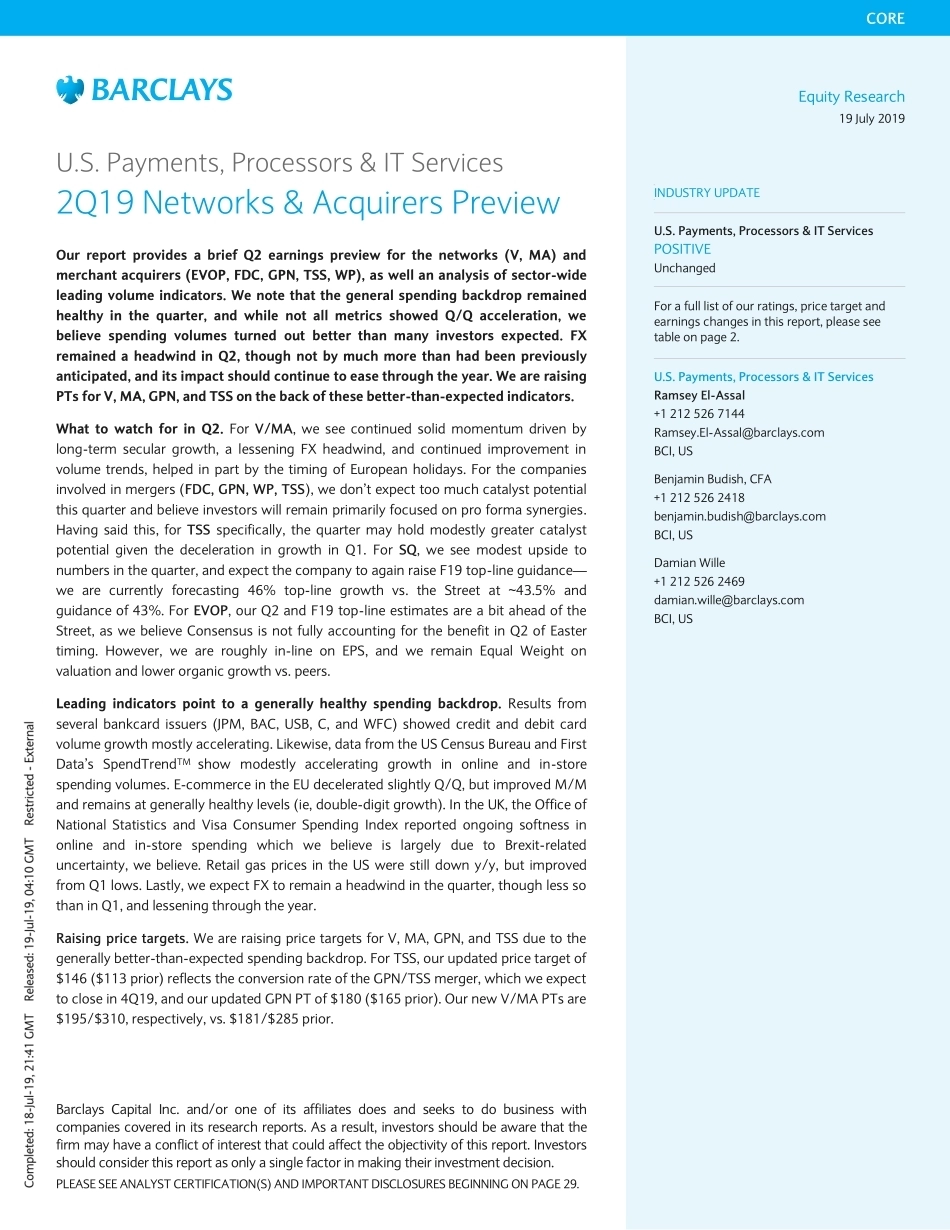
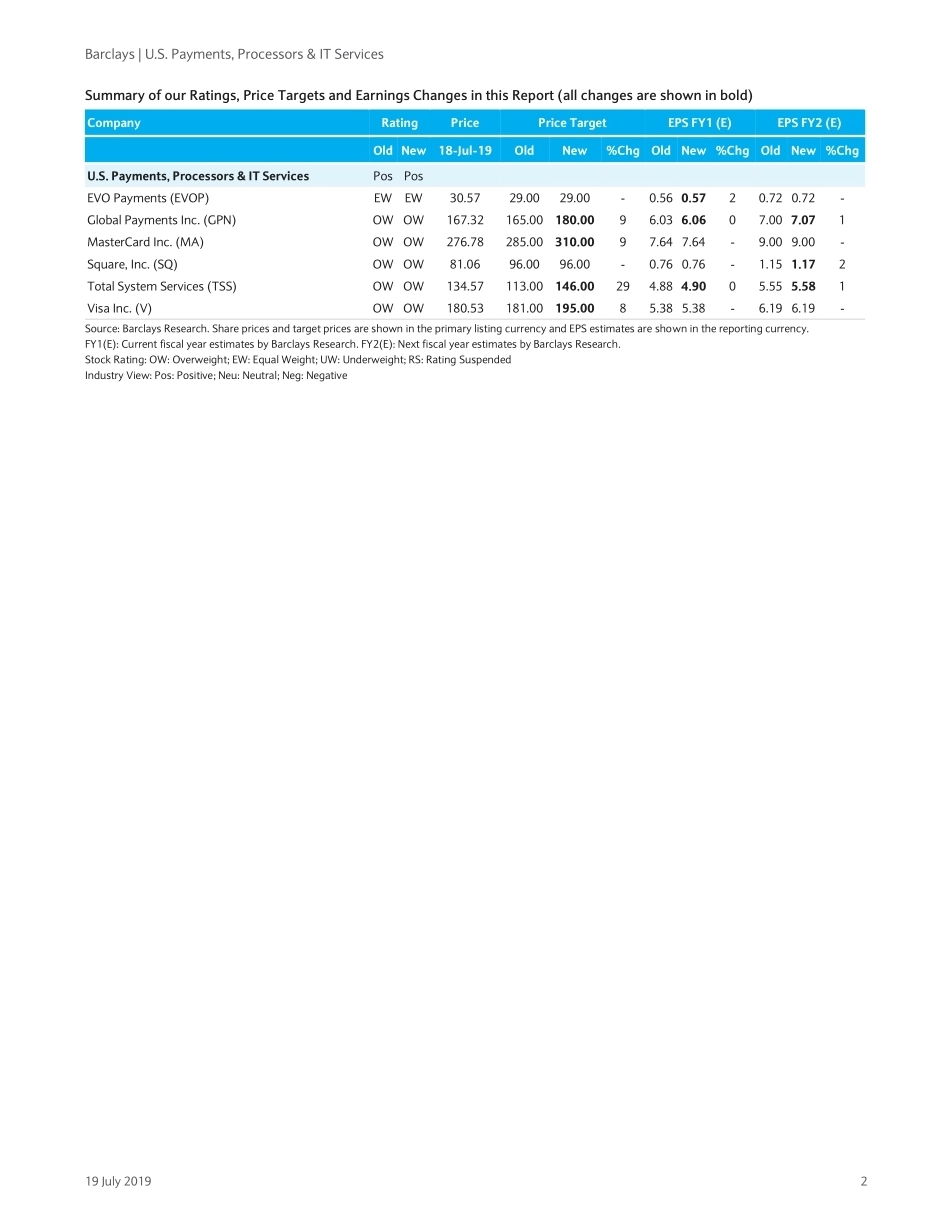
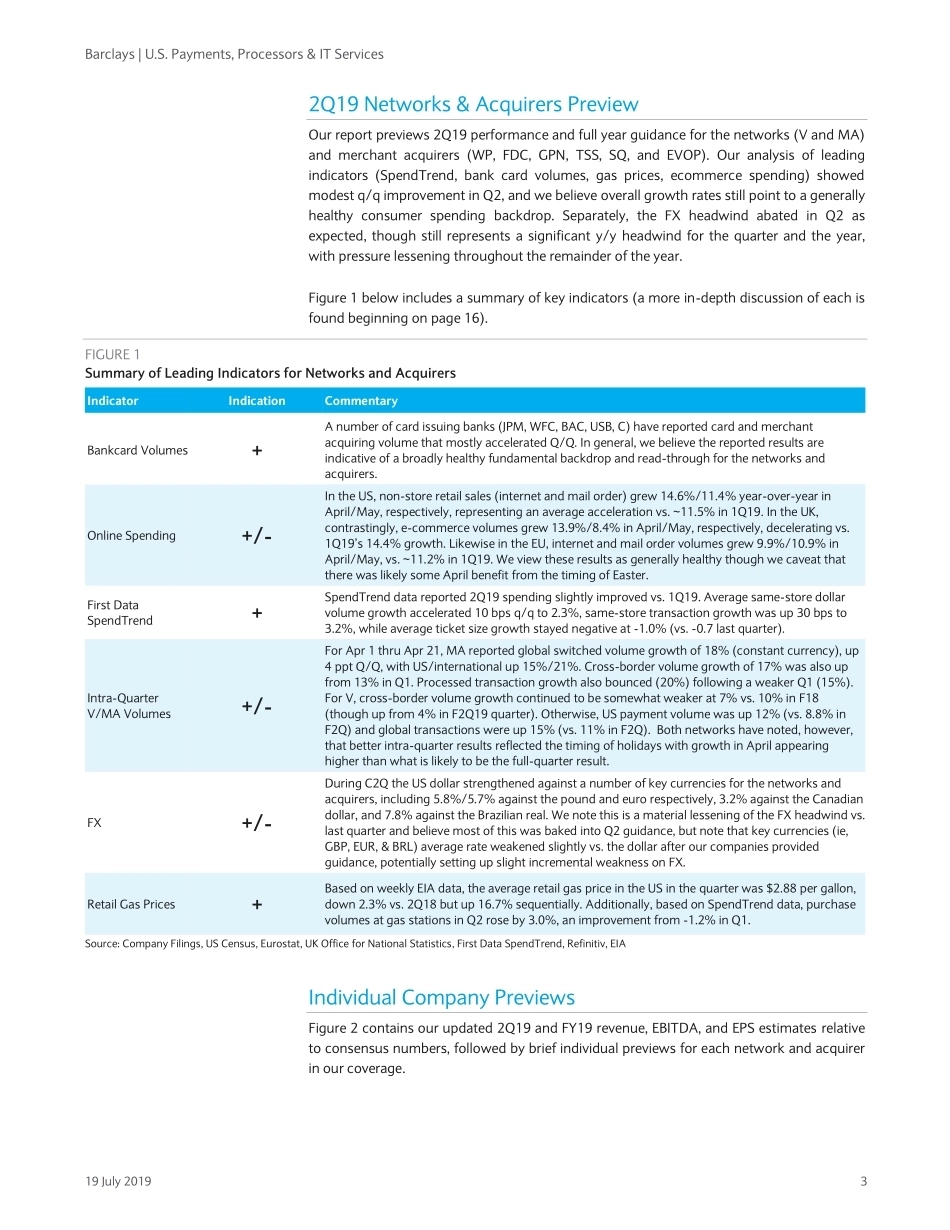
Equity Research 19 July 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 29. Restricted - Internal U.S. Payments, Processors & IT Services 2Q19 Networks & Acquirers Preview Our report provides a brief Q2 earnings preview for the networks (V, MA) and merchant acquirers (EVOP, FDC, GPN, TSS, WP), as well an analysis of sector-wide leading volume indicators. We note that the general spending backdrop remained healthy in the quarter, and while not all metrics showed Q/Q acceleration, we believe spending volumes turned out better than many investors expected. FX remained a headwind in Q2, though not by much more than had been previously anticipated, and its impact should continue to ease through the year. We are raising PTs for V, MA, GPN, and TSS on the back of these better-than-expected indicators. What to watch for in Q2. For V/MA, we see continued solid momentum driven by long-term secular growth, a lessening FX headwind, and continued improvement in volume trends, helped in part by the timing of European holidays. For the companies involved in mergers (FDC, GPN, WP, TSS), we don’t expect too much catalyst potential this quarter and believe investors will remain primarily focused on pro forma synergies. Having said this, for TSS specifically, the quarter may hold modestly greater catalyst potential given the deceleration in growth in Q1. For SQ, we see modest upside to numbers in the quarter, and expect the company to again raise F19 top-line guidance—we are currently forecasting 46% top-line growth vs. the Street at ~43.5% and guidance of 43%. For EVOP, our Q2 and F19 top-line estimates are a bit ahead of the Street, as we believe Consensus is not fully accounting for the benefit in Q2 of Easter timing. However, we are roughly in-line on EPS, and we remain Equal Weight on valuation and lower organic growth vs. peers. Leading indicators point to a generally healthy spending backdrop. Results from several bankcard issuers (JPM, BAC, USB, C, and WFC) showed credit and debit card volume growth mostly accelerating. Likewise, data from the US Census Bureau and First Data’s SpendTrendTM show modestly accelerating growth in online and in-store spending volumes. E-commerce in the EU decelerated slightly Q/Q, but improved M/M and remains at generally healthy levels (ie, double-digit growth). In the UK, the Office of National Statistics and Visa Consumer Spending Index reported ongoing softness in online and in-store spending which we believe is largely due to Brexit-related uncertainty, we believe. Retail gas prices in the US were still down y/y, but improved from Q1 lows. Lastly, we expect FX to remain a headwind in the quarter, though less so than in Q1, and lessening through the year. Raising price targets. We are raising price targets for V, MA, GPN, and TSS due to the generally better-than-expected spending backdrop. For TSS, our updated price target of $146 ($113 prior) reflects the conversion rate of the GPN/TSS merger, which we expect to close in 4Q19, and our updated GPN PT of $180 ($165 prior). Our new V/MA PTs are $195/$310, respectively, vs. $181/$285 prior. INDUSTRY UPDATE U.S. Payments, Processors & IT Services POSITIVE Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. Payments, Processors & IT Services Ramsey El-Assal +1 212 526 7144 Ramsey.El-Assal@barclays.com BCI, US Benjamin Budish, CFA +1 212 526 2418 benjamin.budish@barclays.com BCI, US Damian Wille +1 212 526 2469 damian.wille@barclays.com BCI, US Barclays | U.S. Payments, Processors & IT Services 19 July 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 18-Jul-19 Old New %Chg Old New %Chg Old New %Chg U.S. Payments, Processors & IT Services Pos Pos EVO Payments (EVOP) EW EW 30.57 29.00 29.00 - 0.56 0.57 2 0.72 0.72 - Global Payments Inc. (GPN) OW OW 167.32 165.00 180.00 9 6.03 6.06 0 7.00 7.07 1 MasterCard Inc. (MA) OW OW 276.78 285.00 310.00 9 7.64 7.64 - 9.00 9.00 - Square, Inc. (SQ) OW OW 81.06 96.00 96.00 - 0.76 0.76 - 1.15 1.17 2 Total System Services (TSS) OW OW 134.57 113.00 146.00 29 4.88 4.90 0 5.55 5.58 1 Visa Inc. (V) OW OW 180.53 181.00 195.00 8 5.38 5.38 - 6.19 6.19 - Source: Barclays Research. Share prices and target prices are shown in the primary listing currency and EPS estimates are shown in the reporting currency. FY1(E): Current fiscal year estimates by Barclays Research. FY2(E): Next fiscal year estimates by Barclays Research. ...




发表评论取消回复