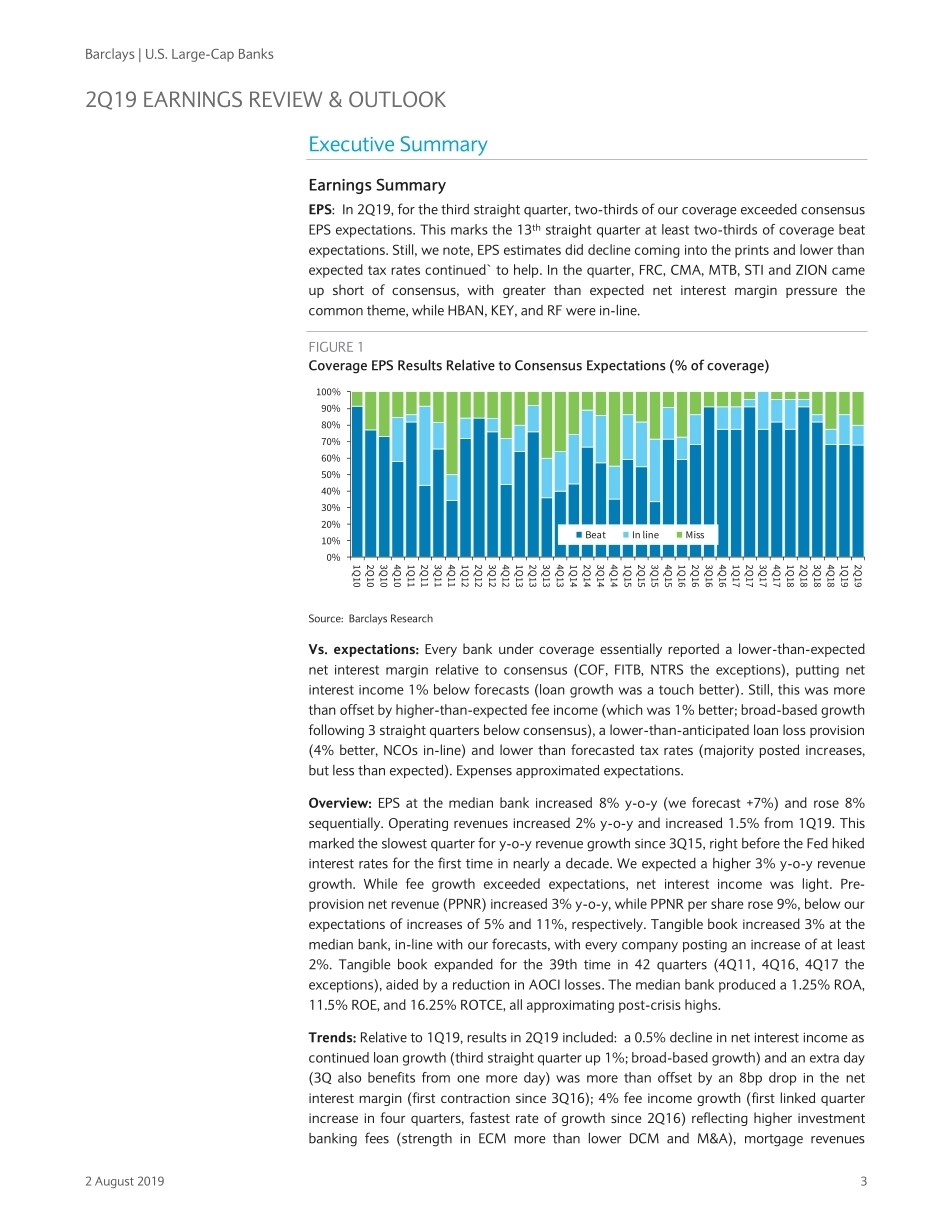
Equity Research 2 August 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 51. Restricted - Internal U.S. Large-Cap Banks 2Q19 EPS Review: A NIMble Quarter EPS continues to exceed expectations. In 2Q19, for the third straight quarter, two-thirds of our coverage exceeded consensus EPS expectations. This marks the 13th straight quarter at least two-thirds of coverage beat expectations. Still, every bank under coverage essentially reported a lower-than-expected net interest margin relative to consensus (COF, FITB, NTRS the exceptions), putting net interest income 1% below forecasts (loan growth was a touch better). Still, this was more than offset by higher-than-expected fee income (which was 1% better; broad-based growth following three straight quarters below consensus), a lower-than-anticipated loan loss provision (4% better, NCOs in-line) and lower than forecast tax rates (majority posted increases, but less than expected). Expenses approximated expectations. The median bank produced a 1.25% ROA, 11.5% ROE, and 16.25% ROTCE, all approximating post-crisis highs. In the near term, balance sheet growth, share repurchase, cost controls and benign asset quality should help to mitigate net interest margin pressure. The median bank has seen its 2019 consensus EPS estimate decline 2% since the start of the year, while 2020 has fallen 4% amid a change in interest rate expectations. For 3Q19, relative to 2Q19, we expect stable to modestly lower net interest income reflecting continued loan growth (though seasonal headwinds), lower net interest margins (pressured reinvestment rates, though deposit costs beginning to turn), and one more day; varied fee income trends (mortgage and asset/wealth management higher, investment banking fees seasonally lower, trading revenues seeing easing y-o-y comps); controlled expenses (branch closures, tech-related efficiency improvements); relatively benign asset quality metrics (though NPA, NCO and reserve/loan ratios all bottoming out); a higher tax rate (up ~70bps); and a reduced share count (-2% as CCAR 2019 cycle begins; would mark the largest post crisis quarterly decline). While interest rate expectations have shifted dramatically since the start of the year and the economy is slowing (and could slow further amid trade-induced uncertainties), at current valuations, we continue to be constructive on the group. Our thesis at the beginning of the year, which we believe still generally holds, was predicated on six tenets, which include: 1) continued EPS and book value growth (which we still expect, even if the Fed cuts further), 2) a continuation of active capital management (all-in yield in excess of 11%, higher of any major industry group), 3) we believe we are approaching ‘regulatory finalization’ (SCB expected in the near future, Volcker rule change likely in the early fall), 4) we expect technology and economies of scale to increasingly be a differentiator for the largest bank (efficiency ratios for our coverage have improved on a y-o-y basis for 21 straight quarters), 5) should our economic base case not pan out, we believe the group is more defensive than investors appreciate (this applies to both the dynamic economic and interest rate outlooks), and 6) we find valuations attractive, even if we are in the late cycle (P/E relative to the S&P 500 at 17-year low despite a much improved risk/return profile). INDUSTRY UPDATE U.S. Large-Cap Banks POSITIVE Unchanged U.S. Large-Cap Banks Jason M. Goldberg, CFA +1 212 526 8580 jason.goldberg@barclays.com BCI, US Inna Blyakher +1 212 526 3904 inna.blyakher@barclays.com BCI, US Matthew Kesselhaut +1 212 526 0181 matthew.kesselhaut@barclays.com BCI, US Eugene Koysman +1 212 526 0971 Eugene.Koysman@barclays.com BCI, US Brian Morton, CFA +1 212 526 2163 brian.morton@barclays.com BCI, US Barclays | U.S. Large-Cap Banks 2 August 2019 2 NOTES TO THE READER This report contains our macro thoughts following the 2Q19 earnings season. We have previously published real-time company notes with our company specific conclusions. Summaries of those reports can be found starting on page 20; links to the full reports below. ALLY - 2Q19 EPS Review: Racing Towards its 2019 Goals (7/18/19) BAC - 2Q19 EPS Review: Cost Controls Should Help to Buffer Rate Pressures (7/17/19) BBT - 2Q19 EPS Review: 2019 Outlook Intact Despite Lower Rates (7/18/19) BK – 2Q19 EPS Review: Cost Controls, Buyback to Mitigate Further NII Redux (7/17/19) C - 2Q19 EPS Review: Focused on ROTCE Targets, Additional Levers if Needed (7/15/19) CFG - 2Q19 EPS Review: Beat on Fees as NIM is Press...




发表评论取消回复