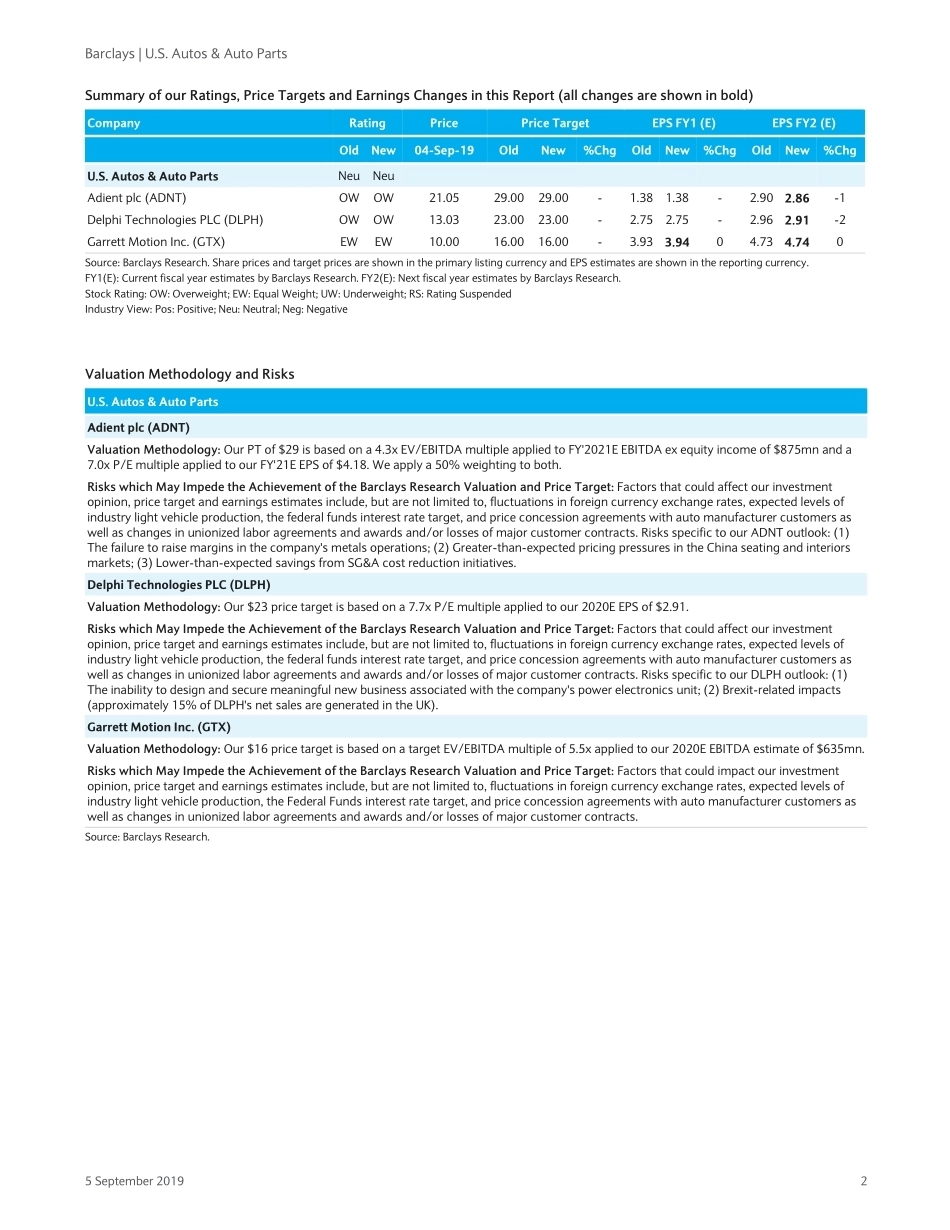
Equity Research 5 September 2019 FOCUS Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 25. Restricted - External U.S. Autos & Auto Parts Late cycle auto part LBOs are possible LBOs could provide a floor to valuations. Investors have begun to take note after the announcement of two deals this year (Magnetti Marelli and Tower) seems to belie common wisdom that it’s too late in the cycle for ‘take private’ transactions. Using a back of the envelope LBO framework, we see the greatest potential in AXL. Late cycle auto parts deal history is less bad then investors think. Auto parts don’t meet many of the common criteria for LBOs and public investors (and we think PE sponsors) point to late cycle deals from the mid-2000s as proof that auto parts LBOs won’t work. But two the of deals (Dana and Tower) appear to have eventually attractive IRRs even in the face of the Great Recession, and another set of transactions (the rollup of metal forming into HHI and Metaldyne) was highly successful. Some key success factors that emerge include a) buy cheap (of course), b) think about platforms to buy even cheaper later, and c) have follow-on funds available for bolt-on/debt buyback. First-cut screen for companies to evaluate further. Using a screen of a) equity market cap <$3bn and b) stock price under 50% of one year high, yields 4 companies to examine in more depth: AXL, DLPH, GTX and ADNT. AXL cash flows make it the most promising candidate. We examine AXL, DLPH, ADNT and GTX for potential returns – both in a base case as is, base case with asset sales, and a downside recession/recovery scenario. To examine the LBO, we created ‘back of the envelope’ LBO models for each supplier. •AXL may be the best all-around candidate for a take–private transaction,largely due to its strong cash flow generation (which is still strong despiterecent missteps). Returns could be enhanced further by selling parts of theMetaldyne business it acquired, even if for less than what was originally paid.•Conversely, weak cash flows at DLPH make it less attractive as an ‘as is’ target– although if a quick sale of its electronics businesses could be done, IRRwould become attractive (even with a low exit multiple of 3.0x on the remaining ICE business). •ADNT may offer attractive returns, but high leverage on consolidated EBITDAmakes a transaction less likely. Our analysis also highlights the drag from thecash burn at SS&M – which means value would be enhanced even if ADNThad to pay a new owner (say $300mn) to take over parts of SS&M.•GTX’s strong cash flow generation (which also supports higher initialleverage) could make it an interesting target, even with multiple derating dueto concerns about ICE longevity. Although with a focused portfolio, we do notsee the potential for asset sales and its spinoff lockup extends until April 2020.INDUSTRY UPDATE U.S. Autos & Auto Parts NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. Autos & Auto Parts Brian A. Johnson +1 212 526 5627 brian.a.johnson@barclays.com BCI, US Steven Hempel, CFA +1 312 609 7260 steven.hempel@barclays.com BCI, US Jason Stuhldreher +1 312 609 8183 Jason.Stuhldreher@barclays.com BCI, US Barclays | U.S. Autos & Auto Parts 5 September 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 04-Sep-19 Old New %Chg Old New %Chg Old New %Chg U.S. Autos & Auto Parts Neu Neu Adient plc (ADNT) OW OW 21.05 29.00 29.00 - 1.38 1.38 - 2.90 2.86 -1 Delphi Technologies PLC (DLPH) OW OW 13.03 23.00 23.00 - 2.75 2.75 - 2.96 2.91 -2 Garrett Motion Inc. (GTX) EW EW 10.00 16.00 16.00 - 3.93 3.94 0 4.73 4.74 0 Source: Barclays Research. Share prices and target prices are shown in the primary listing currency and EPS estimates are shown in the reporting currency. FY1(E): Current fiscal year estimates by Barclays Research. FY2(E): Next fiscal year estimates by Barclays Research. Stock Rating: OW: Overweight; EW: Equal Weight; UW: Underweight; RS: Rating Suspended Industry View: Pos: Positive; Neu: Neutral; Neg: Negative Valuation Methodology and Risks U.S. Autos & Auto Parts Adient plc (ADNT) Valuation Methodology: Our PT of $29 is based on a 4.3x EV/EBITDA multiple applied to FY'2021E EBITDA ex equity income of $875mn and a 7.0x P/E multiple applied to our FY'21E EPS of $4.18. We apply a 50% weighting to both. Risks which May Impede the Achievement of the Barclays Research Valuation and Price Target: Factors that could aff...




发表评论取消回复