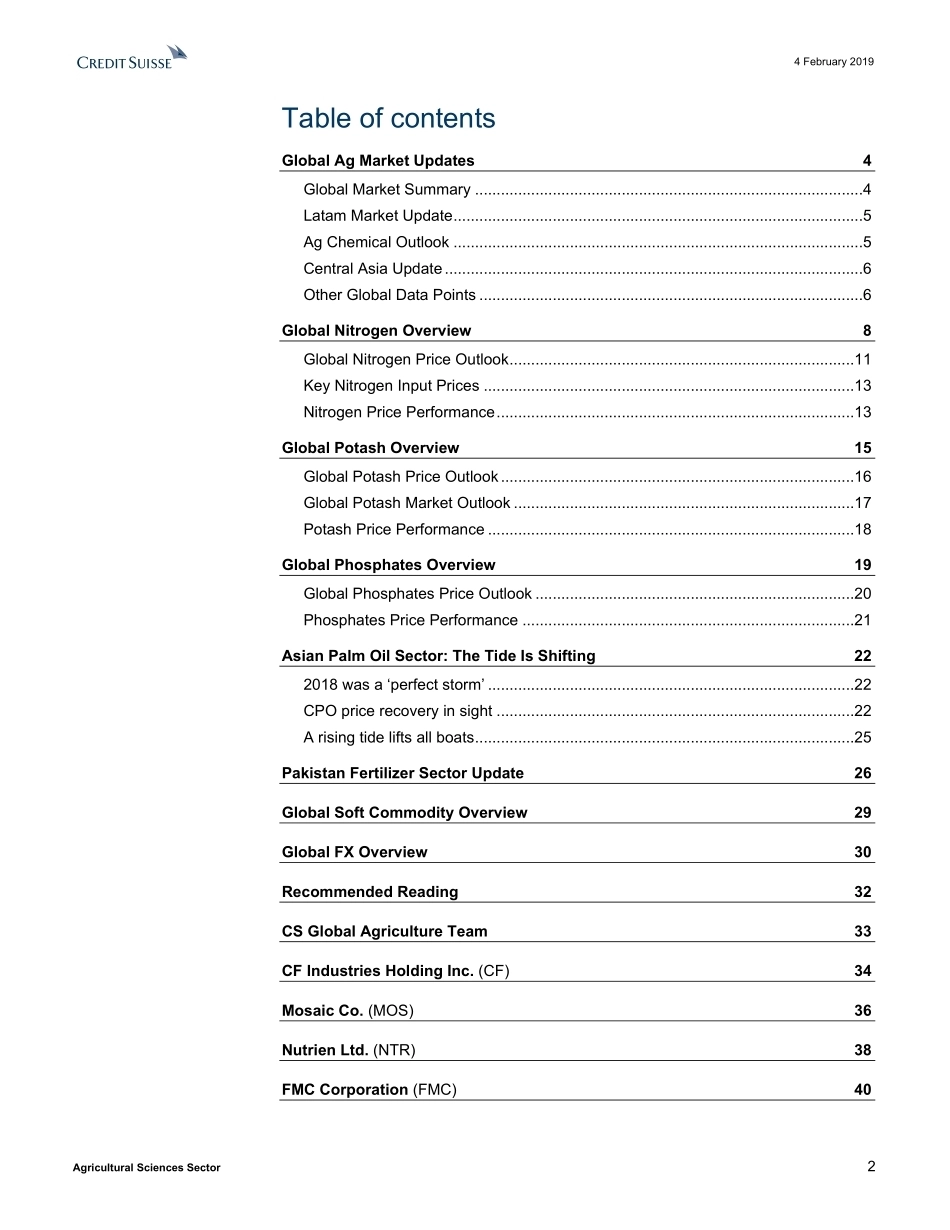
DISCLOSURE APPENDIX AT THE BACK OF THIS REPORT CONTAINS IMPORTANT DISCLOSURES, ANALYST CERTIFICATIONS, LEGAL ENTITY DISCLOSURE AND THE STATUS OF NON-US ANALYSTS. US Disclosure: Credit Suisse does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the Firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. 4 February 2019Americas/United StatesEquity ResearchFertilizers Agricultural Sciences Sector QUARTERLYResearch AnalystsChristopher S. Parkinson212 538 6286christopher.parkinson@credit-suisse.comChris Counihan44 20 7883 7618chris.counihan@credit-suisse.comVictor Saragiotto55 11 3701 6303victor.saragiotto@credit-suisse.comAmanda Foo603 2723 2089amanda.foo@credit-suisse.comFahd Niaz, CFA65 6212 3035fahd.niaz@credit-suisse.comGraeme Welds212 538 8463graeme.m.welds@credit-suisse.comIan Miller55 11 3701 6336ian.miller@credit-suisse.comKieran de Brun212 538 3440kieran.debrun@credit-suisse.comHarris Fein212 538 3064harris.fein@credit-suisse.comStable Ag Macro, but Still a Crowded Space■'19 Outlook Healthy on Probable Trade Resolution, FMC Top Ag Pick: After multiple years of our "L-shaped recovery" call on the ag macro, we're modestly more constructive in '19 due to: (i) healthy coarse grain / oil seed demand, (ii) specialty crop growth, (iii) upside optionality from a potential US / China trade resolution, and (iv) a favorable election cycle backdrop (India, Argentina, etc.). In our view, corn and soy prices will likely push towards the upper end of CSe LT ranges of $3.70-$4.20 and $8.50-$10.00, respectively. Given the high degree of volatility likely to persist in soft commodity markets, we recommend being selective in stock selection, stressing FMC / Corteva (DWDP) are the best ways to play the ag macro.■US / China Trade Optionality Drives Cautious Optimism: It's difficult to predict the outcome of US/China trade negotiations, but we believe the risk (from here) is to the upside. There have been positive signs such as China granting new trait approvals, but tensions between the two nations clearly remain elevated in light of ongoing legal actions. We believe there are clear incentives for both parties to reach a deal. The US is well positioned to "help" China reach its E10 goal, while restoring / growing Chinese grain demand would be a boon for a key component of the Trump support base. ■Plenty of Supply Availability in Global Ferts, Potash Is Best Balanced: Within ferts, we retain our view all 3 macro fertilizers will remain supply-driven, w/ potash preserving the best 1H19 S/D balance. The nitrogen S/D remains at risk (vs. expectations) given: (i) ample new supply (FSU, ME & Africa), and (ii) moderating 4th quartile input costs. We view gas availability improvements in EE, T&T and Central Asia and / or any shift in rhetoric on Iranian sanctions as key supply risks. CF and NTR are arguably reflecting some of this risk, but we still view upside as limited (for now). Phosphate prices continue to decline in the Americas / Asia, which investors are shrugging off, citing lower inputs. We anticipate ample new supply (MENA, etc.) to meet stable '19 demand, posing slight downside risk to bullish expectations despite lower raws. Expect only slight declines in Chinese exports as more efficient producers ramp to offset environmental closures. ■CPC Outlook Is Producer Dependent–Asian / Latam Volume Growth: We believe global CPC markets will only muster 1-2% growth in '19, which is underscored by a mostly-healthy Asia, solid Latam and stable US. European growth will likely be fairly muted, given weak crop economics and a challenging local regulatory environment (glyphosate, chlorpyrifos, neonicotinoids, etc.) – new product launches / EE exposure are integral to Euro growth. On the cost front, AI inflation appears to be easing, but input headwinds will likely still be prevalent in 1H19, a theme across the sector. ■New Estimates: MOS ('19 EPS $2.25 TP $30), NTR ('19 EPS $3.60, TP $55), CF ('19 EPS $2.71, new TP $46), FMC ('19 EPS $5.80, TP $114).4 February 2019Agricultural Sciences Sector2Table of contentsGlobal Ag Market Updates4Global Market Summary ..........................................................................................4Latam Market Update...............................................................................................5Ag Chemical Outlook ...............................................................................................5Central Asia Update.................................................................................................6Other Global Data Points .........................................................................................6Global Nitrogen Overview8Global Nitrogen Price Outlook................................................................................11Key ...





发表评论取消回复