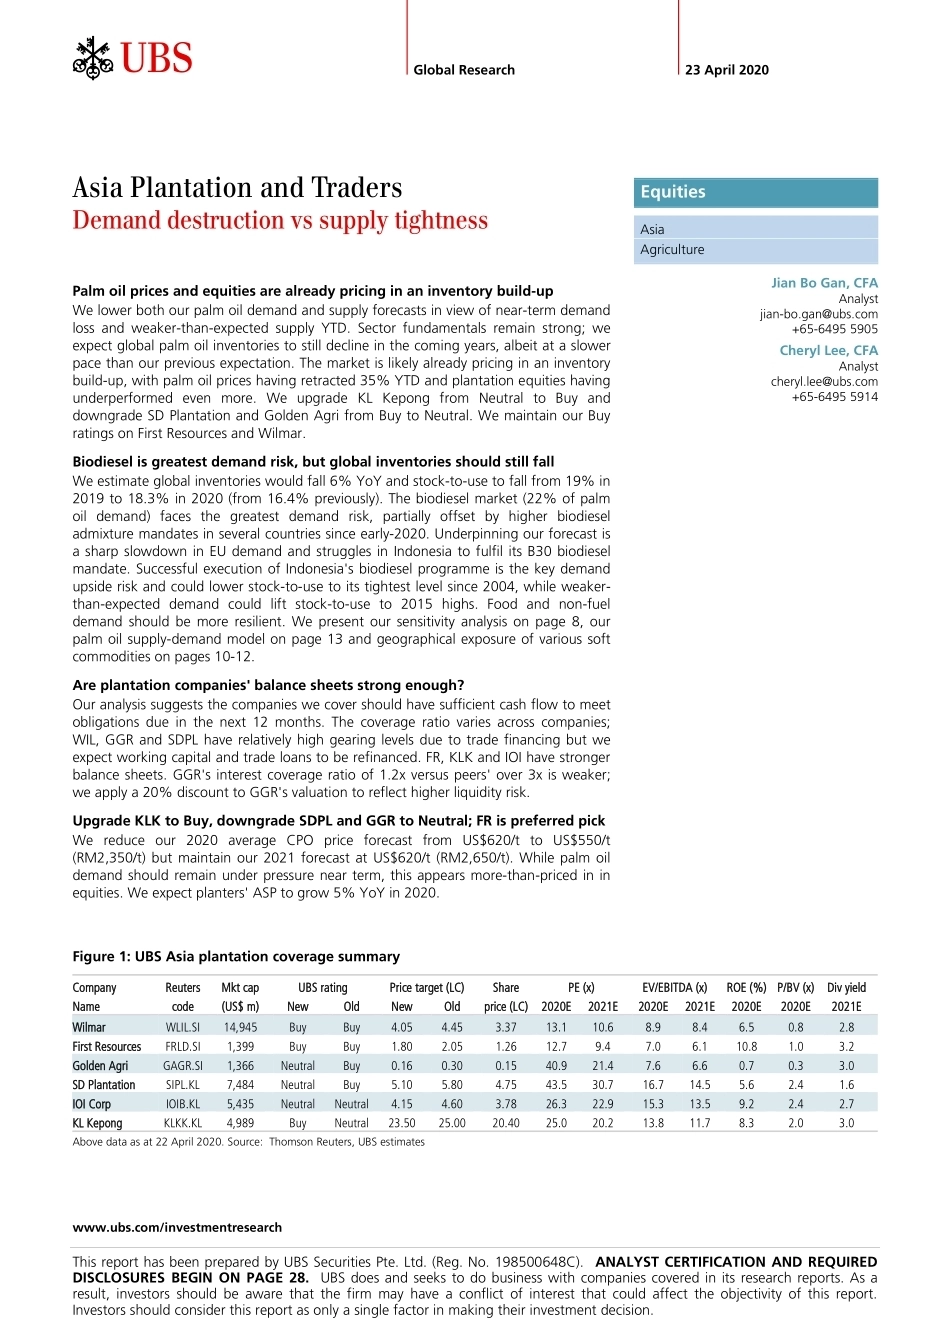
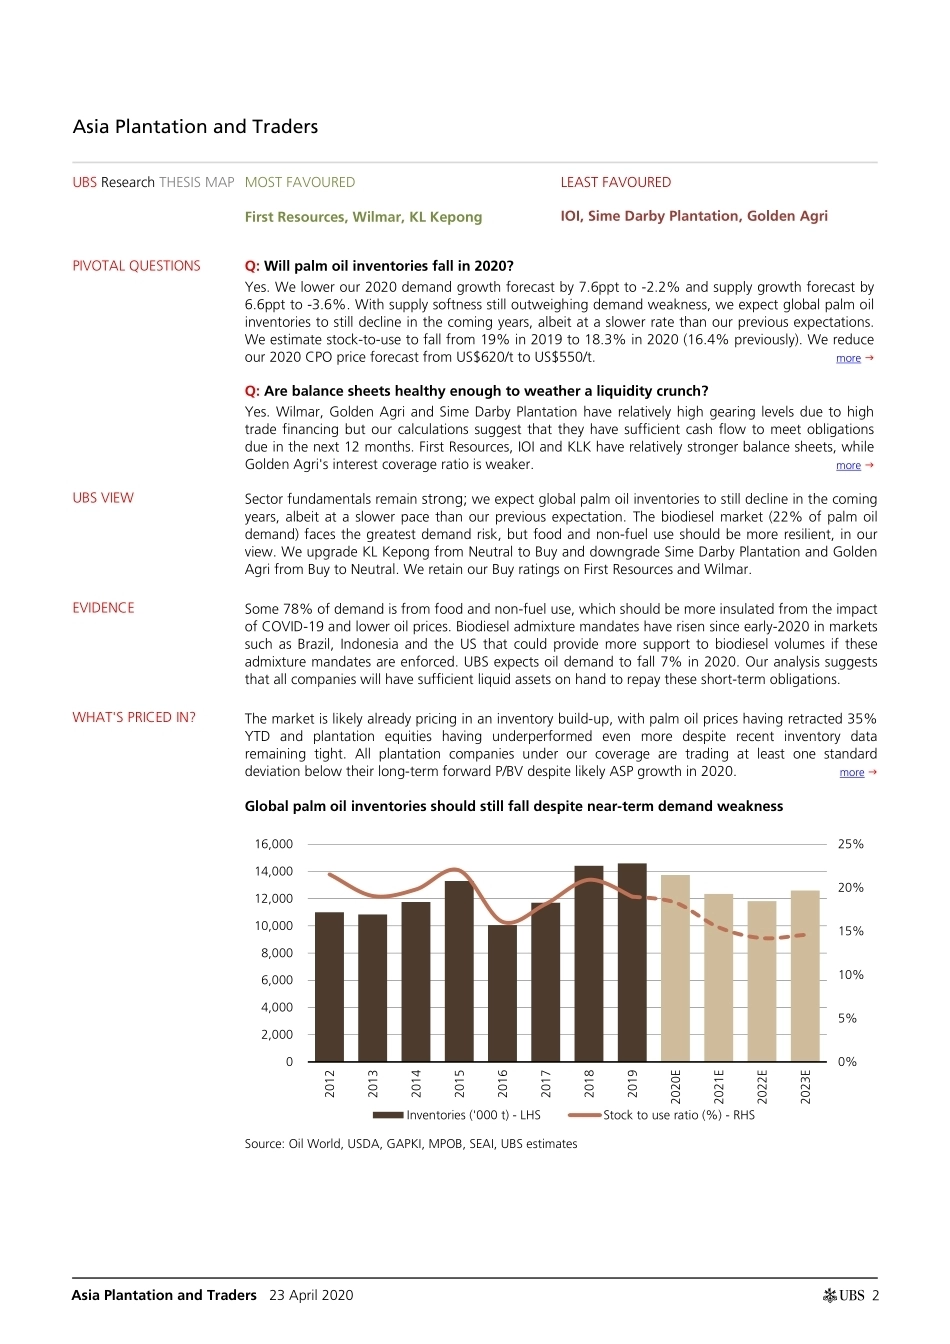
www.ubs.com/investmentresearch This report has been prepared by UBS Securities Pte. Ltd. (Reg. No. 198500648C). ANALYST CERTIFICATION AND REQUIRED DISCLOSURES BEGIN ON PAGE 28. UBS does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Global Research 23 April 2020 Asia Plantation and Traders Demand destruction vs supply tightness Palm oil prices and equities are already pricing in an inventory build-up We lower both our palm oil demand and supply forecasts in view of near-term demand loss and weaker-than-expected supply YTD. Sector fundamentals remain strong; we expect global palm oil inventories to still decline in the coming years, albeit at a slower pace than our previous expectation. The market is likely already pricing in an inventory build-up, with palm oil prices having retracted 35% YTD and plantation equities having underperformed even more. We upgrade KL Kepong from Neutral to Buy and downgrade SD Plantation and Golden Agri from Buy to Neutral. We maintain our Buy ratings on First Resources and Wilmar. Biodiesel is greatest demand risk, but global inventories should still fall We estimate global inventories would fall 6% YoY and stock-to-use to fall from 19% in 2019 to 18.3% in 2020 (from 16.4% previously). The biodiesel market (22% of palm oil demand) faces the greatest demand risk, partially offset by higher biodiesel admixture mandates in several countries since early-2020. Underpinning our forecast is a sharp slowdown in EU demand and struggles in Indonesia to fulfil its B30 biodiesel mandate. Successful execution of Indonesia's biodiesel programme is the key demand upside risk and could lower stock-to-use to its tightest level since 2004, while weaker-than-expected demand could lift stock-to-use to 2015 highs. Food and non-fuel demand should be more resilient. We present our sensitivity analysis on page 8, our palm oil supply-demand model on page 13 and geographical exposure of various soft commodities on pages 10-12. Are plantation companies' balance sheets strong enough? Our analysis suggests the companies we cover should have sufficient cash flow to meet obligations due in the next 12 months. The coverage ratio varies across companies; WIL, GGR and SDPL have relatively high gearing levels due to trade financing but we expect working capital and trade loans to be refinanced. FR, KLK and IOI have stronger balance sheets. GGR's interest coverage ratio of 1.2x versus peers' over 3x is weaker; we apply a 20% discount to GGR's valuation to reflect higher liquidity risk. Upgrade KLK to Buy, downgrade SDPL and GGR to Neutral; FR is preferred pick We reduce our 2020 average CPO price forecast from US$620/t to US$550/t (RM2,350/t) but maintain our 2021 forecast at US$620/t (RM2,650/t). While palm oil demand should remain under pressure near term, this appears more-than-priced in in equities. We expect planters' ASP to grow 5% YoY in 2020. Figure 1: UBS Asia plantation coverage summary Company Reuters Mkt cap UBS rating Price target (LC) Share PE (x) EV/EBITDA (x) ROE (%) P/BV (x) Div yield Name code (US$ m) New Old New Old price (LC) 2020E 2021E 2020E 2021E 2020E 2020E 2021E Wilmar WLIL.SI 14,945 Buy Buy 4.05 4.45 3.37 13.1 10.6 8.9 8.4 6.5 0.8 2.8 First Resources FRLD.SI 1,399 Buy Buy 1.80 2.05 1.26 12.7 9.4 7.0 6.1 10.8 1.0 3.2 Golden Agri GAGR.SI 1,366 Neutral Buy 0.16 0.30 0.15 40.9 21.4 7.6 6.6 0.7 0.3 3.0 SD Plantation SIPL.KL 7,484 Neutral Buy 5.10 5.80 4.75 43.5 30.7 16.7 14.5 5.6 2.4 1.6 IOI Corp IOIB.KL 5,435 Neutral Neutral 4.15 4.60 3.78 26.3 22.9 15.3 13.5 9.2 2.4 2.7 KL Kepong KLKK.KL 4,989 Buy Neutral 23.50 25.00 20.40 25.0 20.2 13.8 11.7 8.3 2.0 3.0 Above data as at 22 April 2020. Source: Thomson Reuters, UBS estimates Equities Asia Agriculture Jian Bo Gan, CFA Analyst jian-bo.gan@ubs.com +65-6495 5905 Cheryl Lee, CFA Analyst cheryl.lee@ubs.com +65-6495 5914 Asia Plantation and Traders 23 April 2020 2 Asia Plantation and Traders UBS Research THESIS MAP MOST FAVOURED LEAST FAVOURED First Resources, Wilmar, KL Kepong IOI, Sime Darby Plantation, Golden Agri PIVOTAL QUESTIONS Q: Will palm oil inventories fall in 2020? Yes. We lower our 2020 demand growth forecast by 7.6ppt to -2.2% and supply growth forecast by 6.6ppt to -3.6%. With supply softness still outweighing demand weakness, we expect global palm oil inventories to still decline in the coming years, albeit at a slower rate than our previous expectations. We estimate stock-to-use to fall from 19% in 2019 to 18.3% in 2020 (16.4% previously). We reduce our 2020 CPO price forecast from US$620/t to US$550/t. more Q: Are balance sheets healthy enough to weather a liquidity crunch? Yes. Wilmar, Golden Agri and Sime Darby Plantation have relatively high gearing levels due to h...




发表评论取消回复