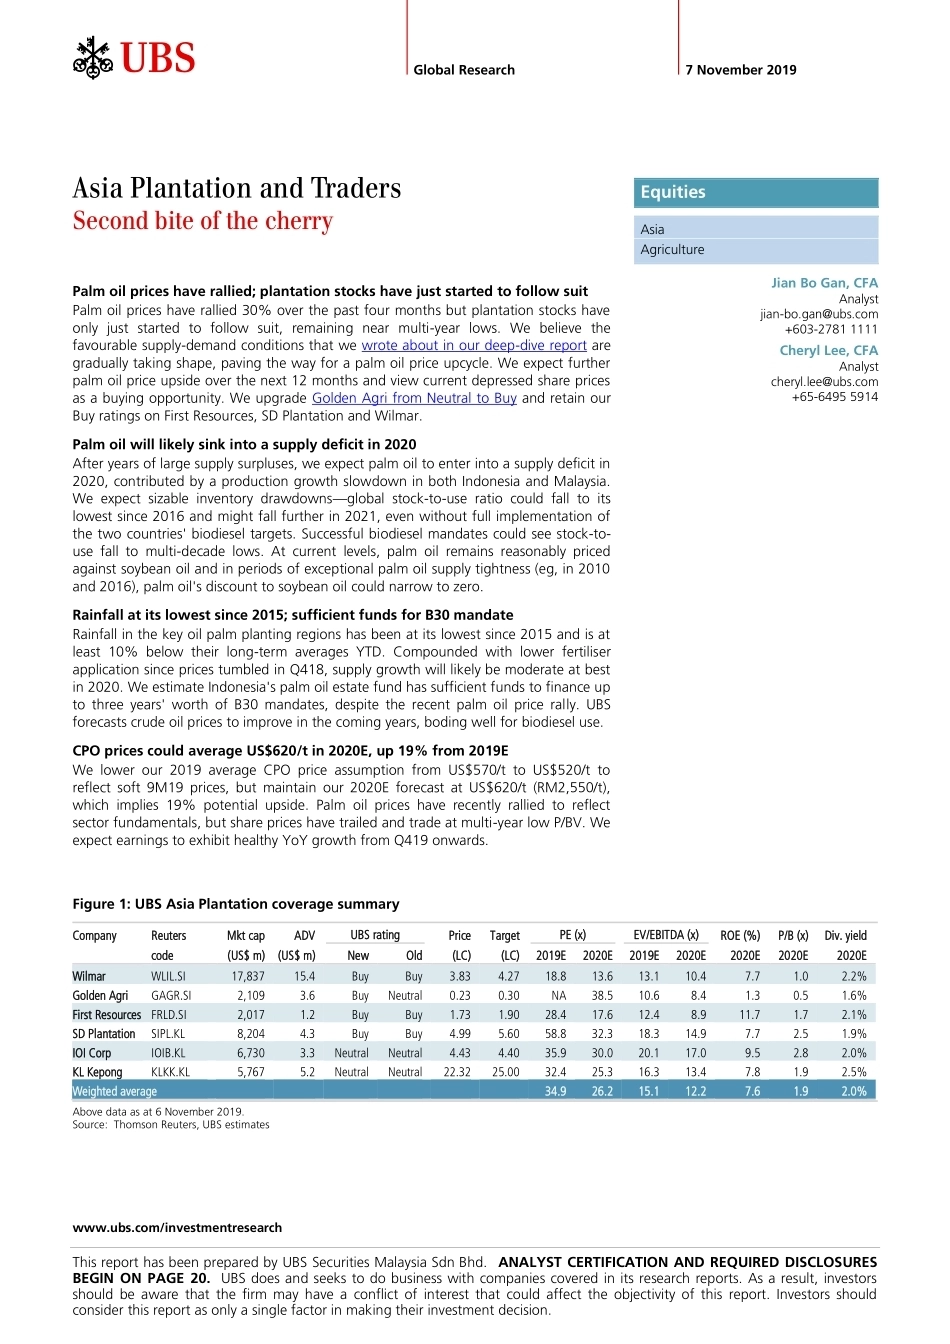
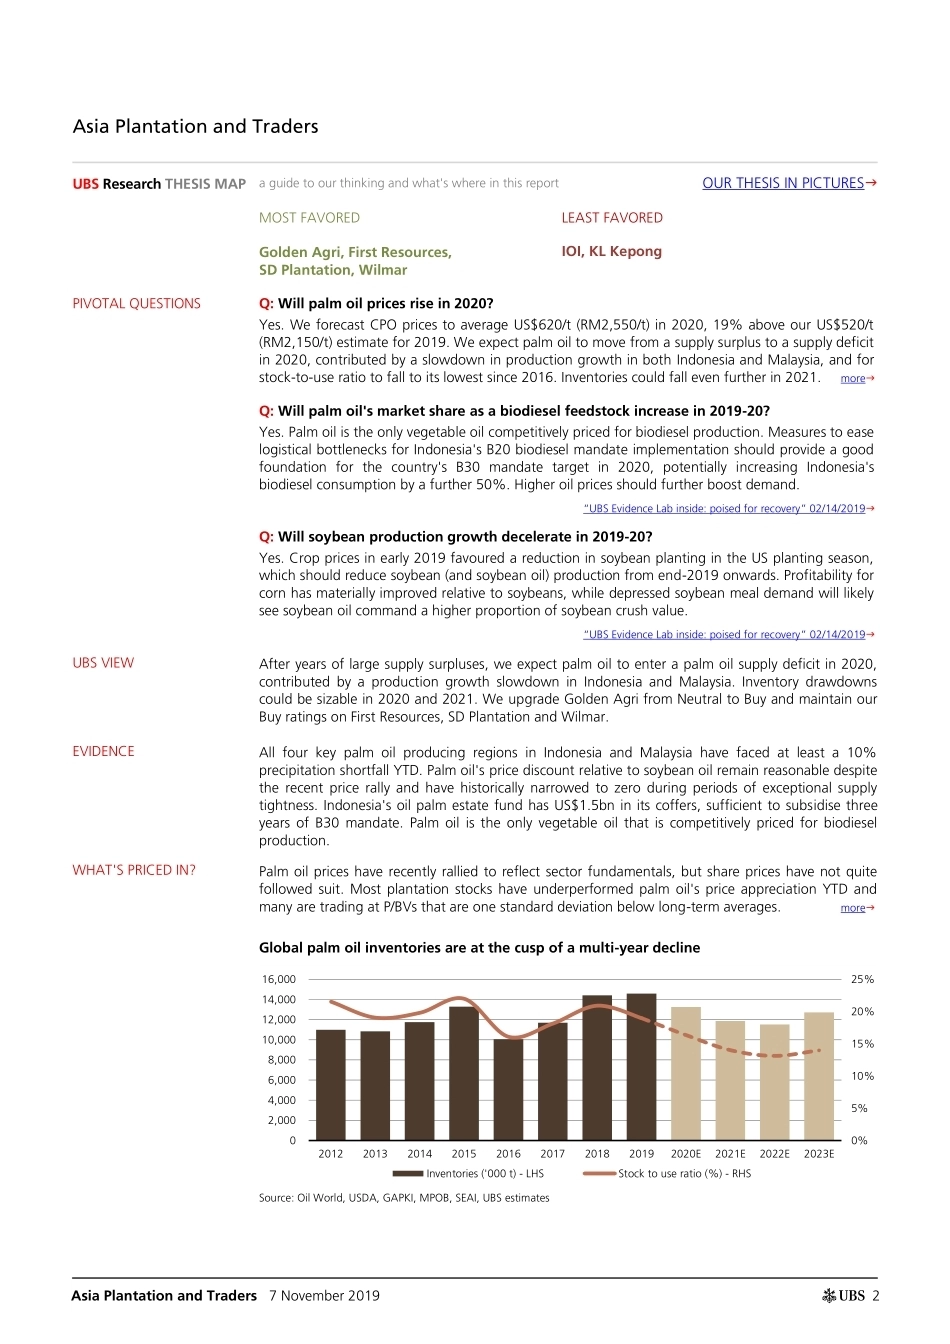
www.ubs.com/investmentresearch This report has been prepared by UBS Securities Malaysia Sdn Bhd. ANALYST CERTIFICATION AND REQUIRED DISCLOSURES BEGIN ON PAGE 20. UBS does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Global Research 7 November 2019 Asia Plantation and Traders Second bite of the cherry Palm oil prices have rallied; plantation stocks have just started to follow suit Palm oil prices have rallied 30% over the past four months but plantation stocks have only just started to follow suit, remaining near multi-year lows. We believe the favourable supply-demand conditions that we wrote about in our deep-dive report are gradually taking shape, paving the way for a palm oil price upcycle. We expect further palm oil price upside over the next 12 months and view current depressed share prices as a buying opportunity. We upgrade Golden Agri from Neutral to Buy and retain our Buy ratings on First Resources, SD Plantation and Wilmar. Palm oil will likely sink into a supply deficit in 2020 After years of large supply surpluses, we expect palm oil to enter into a supply deficit in 2020, contributed by a production growth slowdown in both Indonesia and Malaysia. We expect sizable inventory drawdowns—global stock-to-use ratio could fall to its lowest since 2016 and might fall further in 2021, even without full implementation of the two countries' biodiesel targets. Successful biodiesel mandates could see stock-to-use fall to multi-decade lows. At current levels, palm oil remains reasonably priced against soybean oil and in periods of exceptional palm oil supply tightness (eg, in 2010 and 2016), palm oil's discount to soybean oil could narrow to zero. Rainfall at its lowest since 2015; sufficient funds for B30 mandate Rainfall in the key oil palm planting regions has been at its lowest since 2015 and is at least 10% below their long-term averages YTD. Compounded with lower fertiliser application since prices tumbled in Q418, supply growth will likely be moderate at best in 2020. We estimate Indonesia's palm oil estate fund has sufficient funds to finance up to three years' worth of B30 mandates, despite the recent palm oil price rally. UBS forecasts crude oil prices to improve in the coming years, boding well for biodiesel use. CPO prices could average US$620/t in 2020E, up 19% from 2019E We lower our 2019 average CPO price assumption from US$570/t to US$520/t to reflect soft 9M19 prices, but maintain our 2020E forecast at US$620/t (RM2,550/t), which implies 19% potential upside. Palm oil prices have recently rallied to reflect sector fundamentals, but share prices have trailed and trade at multi-year low P/BV. We expect earnings to exhibit healthy YoY growth from Q419 onwards. Figure 1: UBS Asia Plantation coverage summary Company Reuters Mkt cap ADV UBS rating Price Target PE (x) EV/EBITDA (x) ROE (%) P/B (x) Div. yield code (US$ m) (US$ m) New Old (LC) (LC) 2019E 2020E 2019E 2020E 2020E 2020E 2020E Wilmar WLIL.SI 17,837 15.4 Buy Buy 3.83 4.27 18.8 13.6 13.1 10.4 7.7 1.0 2.2% Golden Agri GAGR.SI 2,109 3.6 Buy Neutral 0.23 0.30 NA 38.5 10.6 8.4 1.3 0.5 1.6% First Resources FRLD.SI 2,017 1.2 Buy Buy 1.73 1.90 28.4 17.6 12.4 8.9 11.7 1.7 2.1% SD Plantation SIPL.KL 8,204 4.3 Buy Buy 4.99 5.60 58.8 32.3 18.3 14.9 7.7 2.5 1.9% IOI Corp IOIB.KL 6,730 3.3 Neutral Neutral 4.43 4.40 35.9 30.0 20.1 17.0 9.5 2.8 2.0% KL Kepong KLKK.KL 5,767 5.2 Neutral Neutral 22.32 25.00 32.4 25.3 16.3 13.4 7.8 1.9 2.5% Weighted average 34.9 26.2 15.1 12.2 7.6 1.9 2.0% Above data as at 6 November 2019. Source: Thomson Reuters, UBS estimates Equities Asia Agriculture Jian Bo Gan, CFA Analyst jian-bo.gan@ubs.com +603-2781 1111Cheryl Lee, CFA Analyst cheryl.lee@ubs.com +65-6495 5914 Asia Plantation and Traders 7 November 2019 2 Asia Plantation and Traders P2 UBS Research THESIS MAP a guide to our thinking and what's where in this report OUR THESIS IN PICTURES MOST FAVORED LEAST FAVORED Golden Agri, First Resources, SD Plantation, Wilmar IOI, KL Kepong PIVOTAL QUESTIONS Q: Will palm oil prices rise in 2020? Yes. We forecast CPO prices to average US$620/t (RM2,550/t) in 2020, 19% above our US$520/t (RM2,150/t) estimate for 2019. We expect palm oil to move from a supply surplus to a supply deficit in 2020, contributed by a slowdown in production growth in both Indonesia and Malaysia, and for stock-to-use ratio to fall to its lowest since 2016. Inventories could fall even further in 2021. more Q: Will palm oil's market share as a biodiesel feedstock increase in 2019-20? Yes. Palm oil is the only vegetable oil competitively priced for biodiesel production. Measures to ease logistical bottlenecks for Indonesia's B20 biodiesel mandate implementation should provide a good foundation ...




发表评论取消回复