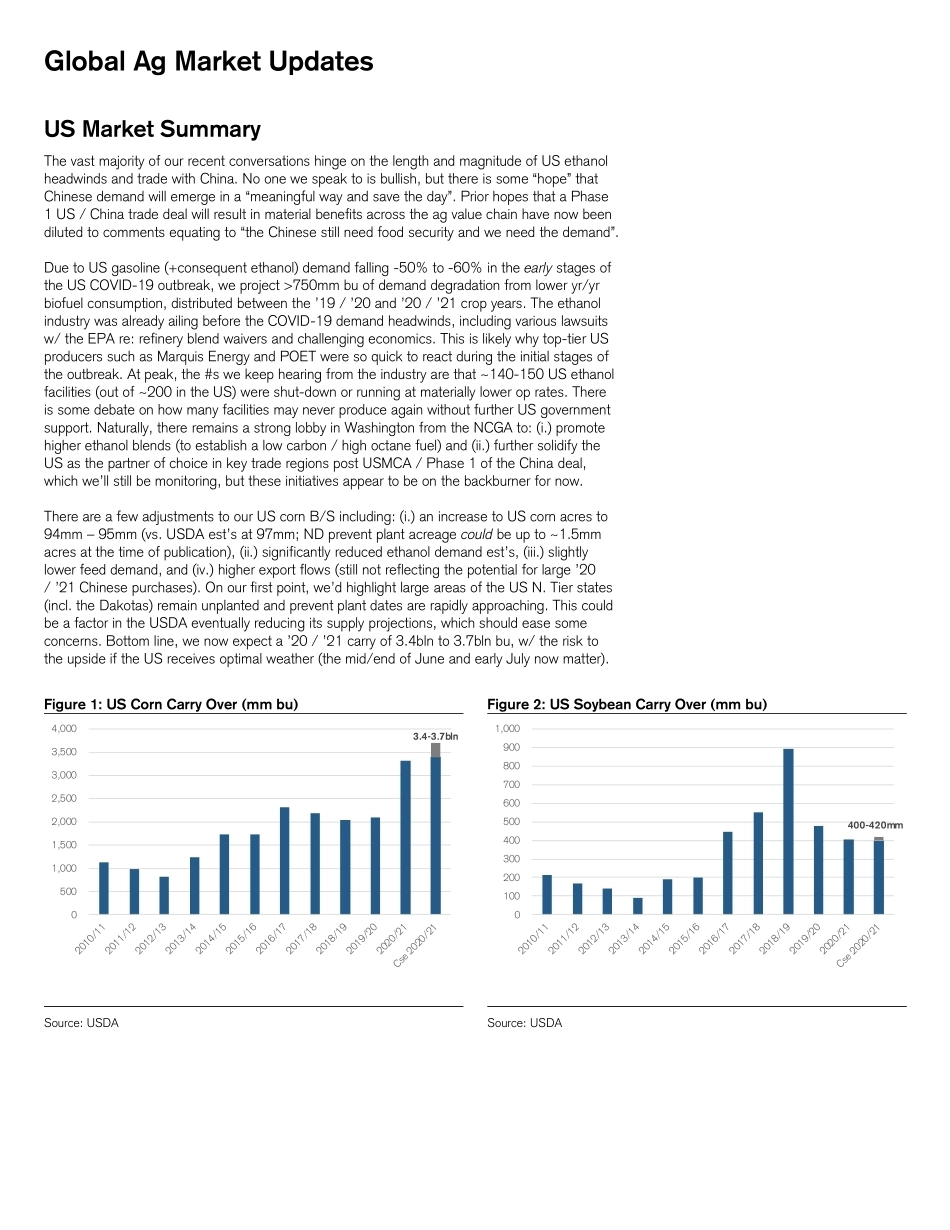
Agricultural Sciences Sector Biofuel Headwinds Negating the Defensibility of the Ag Sector, But Fert Cost Curves Should Eventually Re-Connect vs. Low Expectations Fertilizers | Sector Review More to Global Ag Story than US Corn – Though Aid is Necessary: The vast majority of investors don’t want to “touch” ag due to ’21 corn acre risk, but we stress that’s ignoring > 90% of the equation. We retain significant concerns re: (i.) biofuel demand (US corn, SE Asia Palm Oil, Brazilian sugar), (ii.) further China / US political hostility (lack of trade flows, RMB depreciation), (iii.) 2H seed price competition (esp. Retail channel), (iv.) ongoing US uncertainty for ’21 given carry concerns (biofuels, feed, etc.), and (v.) EM FX volatility. As much as that’s a lot to keep one up at night, we note: (i.) all three macro fertilizers are fairly close to their respective global cost curves (N is below parity, P is close & K slightly above), (ii.) the initial ~$19bln of farmer aid is an incredible safety net (esp. as many farmers’ crop inventories are “under water”), (iii.) ’21 global input demand should still grow off of a lower base (despite lingering crop inventory headwinds), (iv.) CPC demand is still poised to be healthy in certain regions / crops, and (v.) China replenishing inventories of corn and / or soy could be the positive catalyst the industry desperately needs on the global demand front. Breaking Down the ~$19bln of US Ag Aid – More is Needed, But It’s a Start: While the US ethanol industry was under pressure prior to a COVID-19 world (+consequent effect on gasoline demand), industry consumption of corn was still comfortably >5bln bu p.a. It’s now clear all COVID-19 headwinds on corn demand could result in +/- 1bln bu of demand degradation, or +/- 5-7% of the upcoming crop (i.e. – new supply); these effects will likely be felt in both the ‘19/’20 and ‘20/’21 crop yrs. For the new crop season there is still a risk of a >3.5bln bu carry (>75% higher vs. normal expectations), so there is still a core demand issue heading into ’21. That said, of the $19bln slated for US ag aid, ~$3.9bln is slated for “row crops”, which provides a valuable safety net. Bottom line, the ag community will still face an inventory issue into ’21 (w/ the only solutions being a weather event, increases in Chinese demand or materially lower ’21 corn acres), but the worst case scenario appears to be off the table (widespread insolvencies, etc.) due to swift policy actions. That said, most of our contacts still suggest there is an underlying demand issue that still requires solving. India CPC is Potentially About to “Upgrade”, But Higher Costs an Issue: The Indian Ministry of Agriculture released a draft regulatory framework banning the import, distribution, manufacture and use of 27 pesticides, citing health risks to human and animal life, and bans in other countries. Companies have ~45 days to respond with comments and challenges. While the outcome is still uncertain (as alternative products are more expensive), this could eventually present tailwinds for some multinational manufacturers w/ replacement products. FMC Still the Core Ag Long, CF / MOS Retain Favorable Risk/Reward Ratios: Sorry to bore everyone, but FMC remains our top pick of the space. Three catalysts to monitor in the 2H are: (i.) FMC’s ability to recapture FX headwinds via price (Latam, Asia, etc.), (ii.) the outlook for other coarse grains / soy / F&V (to offset cotton headwinds), (iii.) success of the SAP implementation, and (iv.) further deals on the fungicide front (purchases, IP swaps). In ferts, we expect volatility to continue throughout US summer fill, but we believe cost curve support will be incrementally evident in the coming months, which should improve sentiment. 27 May 2020 Equity Research Americas | United States DISCLOSURE APPENDIX AT THE BACK OF THIS REPORT CONTAINS IMPORTANT DISCLOSURES, ANALYST CERTIFICATIONS, LEGAL ENTITY DISCLOSURE AND THE STATUS OF NON-US ANALYSTS. US Disclosure: Credit Suisse does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the Firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Research Analysts Christopher S. Parkinson 212 538 6286 christopher.parkinson@credit-suisse.com Kieran de Brun 212 538 3440 kieran.debrun@credit-suisse.com Harris Fein 212 538 3064 harris.fein@credit-suisse.com Global Ag Market Updates US Market Summary The vast majority of our recent conversations hinge on the length and magnitude of US ethanol headwinds and trade with China. No one we speak to is bullish, but there is some “hope” that Chinese demand will emerge in a “meaningful way and save the day”. Prior hopes that a Phase 1 US / China trade deal will result in material benefits across the ag value chain have now been diluted to comments equating to...




发表评论取消回复