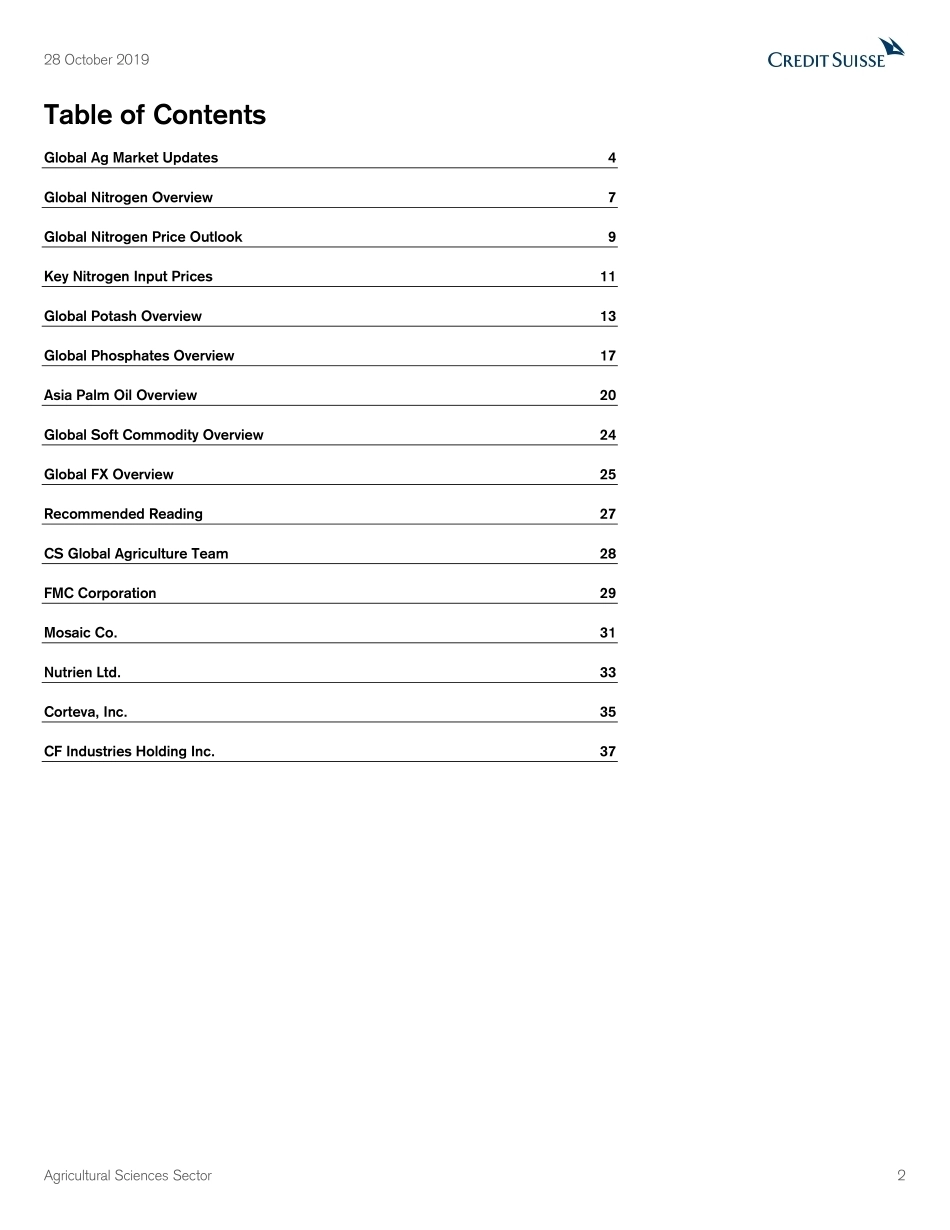
Agricultural Sciences SectorStill Need to be Selective as #s Need to Come Down Considerably; Prefer CPC to Ferts into YE; Searching for N-P-K Cost Curve SupportFertilizers | Sector Review ■Still Search for Direction – Trade, Weather and S/D Factors All in Play: The global ag complex continues to search for direction given a plethora of catalysts, including (i.) an eventual US / China trade resolution (up to ~$25bln of incremental agricultural trade), (ii.) the “final” tally of the US crop and subsequent effect on the 2020 outlook, (iii.) changes to global renewable mandates (US moves to benefit E15, RenovaBio in Brazil, etc.), (iv.) the eventual “reversal” of ASF, and (v.) the effect of new N-P-K supplies (what’s hit the global market in ’19 vs. what’s “left” for ’20 and beyond). We maintain our thesis that investors need to be selective within the ag space, citing our beliefs that (i.) ‘20 fert consensus #s need to fall materially, (ii.) N-P-K markets will remain supply / cost-curve driven (i.e. – even modest increases in N-P-K demand will fail to materially move prices), and (iii.) developed market ag communities still face several hurdles (credit, broad trade uncertainty, etc.) and increasing competition from Latam. Overall investor sentiment leans cautiously optimistic.■Risk to US Production Est’s is to the Downside, But Don’t Expect Timely Updates: Following a slew of channel checks, it is clear that both harvest rates and yields will fall short of USDA expectations, but we don’t expect any meaningful changes for the time being. It’s worth flagging even Senator Grassley (R-IA) is raising concerns re: the USDA’s forecasts and methodologies in DC, so farmer complaints are not being overlooked. While we do not subscribe to the ultra bull view on corn (~95mm in ’20, >$4.50/bu prices, etc.), based on our work there is enough substance to underwrite corn production ~5-7% below the USDA, which in turn drives the stock:use ratio down to the ≤10% range. The CS US corn B/S reflects ~88.5mm acres of corn (-1% yr/yr) w/ yields in ~162bu/ac, while our US soy B/S reflects ~76mm acres (-14% yr/yr) w/ yields in the ~46bu/ac range. Our price deck now reflects $3.80-4.30/bu / $9-10/bu for new crop corn / soy, respectively.■Potash Markets Stabilizing; China Contract and ‘20 Demand are Now Key: Recent supply curtailment announcements entail roughly ~3mmt of potash production on a global basis (5 announcements). It’s too optimistic to give “full credit” for the headline # (a bullish signal), but we do believe there is enough substance to believe potash markets will stabilize at slightly lower lows and the “worst case scenario” for ‘20 is now off of the table. The India contract ($280/t through March ‘20) is slightly better than expected, while expectations for the China contract have fallen to -$20/t (CSe $270/t in late 1Q as port inventories are still elevated); FSU producers will likely be the first movers for the China contract vs. Canpotex.■Not Bullish on US Seed Pricing, But Fears are Overblown: Following several channel checks on US seed price cards (CTVA has >40 price cards, while Bayer posted 14), we do not believe “panic” is warranted. The three primary conclusions we have are (i.) discounting methodology composition for major seed producers is changing post mergers (Bayer Plus, etc.), (ii.) gross price per unit is generally flattish for US corn / down MSD for soy (Stine is being very aggressive in soy), and (iii.) demand for E3 is healthy, but supply is short year 1. ■New 2020 Est’s and PTs: FMC ($6.70, new TP $102), (MOS ($1.35, new TP $26), CTVA ($1.60, new TP $30), NTR ($2.90, new TP $55), CF ($2.50, new TP $43). 28 October 2019Equity ResearchAmericas | United StatesDISCLOSURE APPENDIX AT THE BACK OF THIS REPORT CONTAINS IMPORTANT DISCLOSURES, ANALYST CERTIFICATIONS, LEGAL ENTITY DISCLOSURE AND THE STATUS OF NON-US ANALYSTS. US Disclosure: Credit Suisse does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the Firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Research AnalystsChristopher S. Parkinson212 538 6286christopher.parkinson@credit-suisse.comChris Counihan44 20 7883 7618chris.counihan@credit-suisse.comVictor Saragiotto55 11 3701 6303victor.saragiotto@credit-suisse.comAmanda Foo603 2723 2089amanda.foo@credit-suisse.comGerald Wong, CFA65 6212 3037gerald.wong@credit-suisse.comLucas Beaumont212 325 2458lucas.beaumont@credit-suisse.comKieran de Brun212 538 3440kieran.debrun@credit-suisse.comHarris Fein212 538 3064harris.fein@credit-suisse.com28 October 2019Agricultural Sciences Sector2Table of ContentsGlobal Ag Market Updates4Global Nitrogen Overview7Global Nitrogen Price Outlook9Key Nitrogen Input Prices11Global Potash Overview13Global Phosphates Overview17Asia Palm Oil Overview20Global Soft Commodity Over...




发表评论取消回复