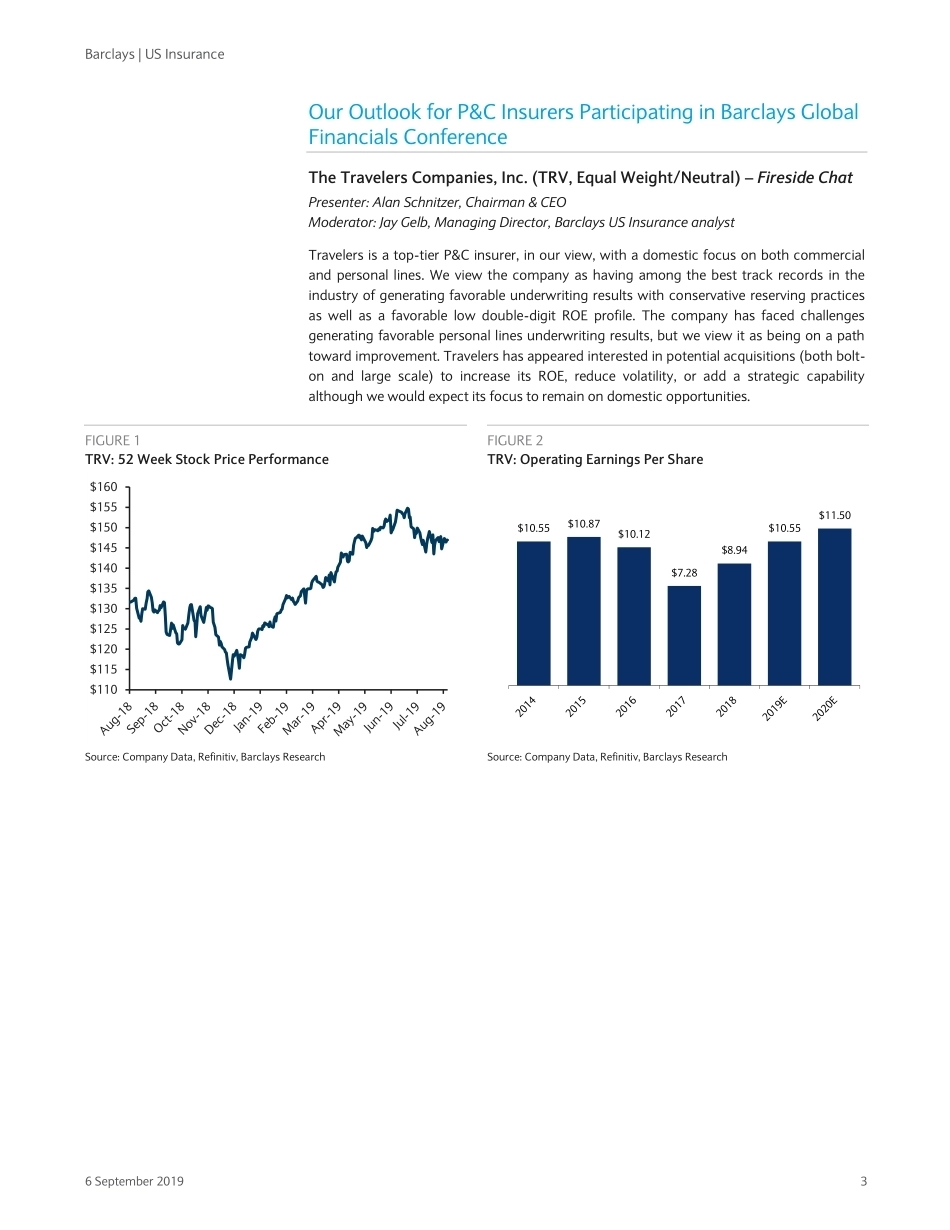
Equity Research 6 September 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 21. Restricted - Internal US Insurance Barclays Financials Conference Preview: P&C vs. Life Insurance Insurance industry presenters at the upcoming Barclays Global Financial Services conference on September 9-11 include bellwether companies TRV, EQH, HIG, LNC, ACGL, ALL, AIG, UNM. The format of these sessions with insurer executives will mostly be fireside chats which means we expect to gain plenty of insight. Overall, we expect a more constructive outlook for the P&C insurers and life insurers based on emerging industry trends. P&C insurers have been benefiting from improving commercial P&C and reinsurance pricing, strong underwriting margins, and substantial excess capital being returned to shareholders. Hurricane Dorian is not expected to result in large-scale (more than $5bn) insured losses meaning insurers’ profits should remain strong in 3Q. The main issue that concerns us for P&C stocks is whether insurers’ results can still exceed investors’ expectations, or whether valuations already fully reflect the good news. We think P&C valuations have largely taken into account the current favorable environment, but we’re inclined to let the winners run. Another factor to keep in mind is perhaps less upside to recurring investment income as a result of the recent plunge in interest rates. On the other hand, the Life insurers face a multitude of headwinds largely related to the steep drop in interest rates along with a flat yield curve that is expected to place additional downward pressure on investment spreads and overall earnings. Bellwether life insurer valuations have compressed to ~7x 2020E P/E reflecting investors’ general lack of interest in the sector (especially relative to P&C insurance), concerns about the drag on earnings and returns from low rates, and lingering concerns about potential losses from legacy long-term care exposure. At these low valuation levels, perhaps financial buyers will become focused on extracting value in the life insurance industry. P&C Insurer Highlights: TRV should be able to capture price increases, generate attractive ROE and consistently return excess capital. AIG has delivered favorable results in 1H 19, and we expect this trend to continue along with increased efficiency opportunities. ALL has significantly improved its Allstate-brand auto insurance results and appears re-focused on growth as well as bolt-on acquisitions. HIG’s P&C results should generate favorable results, and group benefits is an increasingly large part of its business. ACGL should generate the vast majority of its earnings from mortgage insurance, with upside potential from P&C insurance. Life Insurer Highlights: LNC is expected to maintain a constructive stance on EPS growth and share buybacks. EQH has targeted annual operating EPS growth of 5%-7% as well as a mid-teens ROE by 2020, which appear achievable. UNM has delivered strong results in its core business, and investors are expected to carefully monitor any exit opportunities that might be available for its legacy long-term care exposure. INDUSTRY UPDATE U.S. Insurance/Life NEUTRAL Unchanged U.S. Insurance/Non-Life NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. Insurance/Non-Life Jay Gelb, CFA +1 212 526 1561 jay.gelb@barclays.com BCI, US U.S. Consumer Finance Mark C. DeVries +1 212 526 9484 mark.devries@barclays.com BCI, US Barclays | US Insurance 6 September 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 05-Sep-19 Old New %Chg Old New %Chg Old New %Chg U.S. Insurance/Life Neu Neu U.S. Insurance/Non-Life Neu Neu Source: Barclays Research. Share prices and target prices are shown in the primary listing currency and EPS estimates are shown in the reporting currency. FY1(E): Current fiscal year estimates by Barclays Research. FY2(E): Next fiscal year estimates by Barclays Research. Stock Rating: OW: Overweight; EW: Equal Weight; UW: Underweight; RS: Rating Suspended Industry View: Pos: Positive; Neu: Neutral; Neg: Negative Barclays | US Insurance 6 September 2019 3 Our Outlook for P&C Insurers Participating in Barclays Global Financials Conference The Travelers Companies, Inc. (TRV, Equal Weight/Neutral) – Fireside Chat Presenter: Alan Schnitzer, Chairman & CEO Moderator: Jay Gelb, Managing Director, Barclays US Insurance analyst Travelers is a top-tier P&C i...




发表评论取消回复