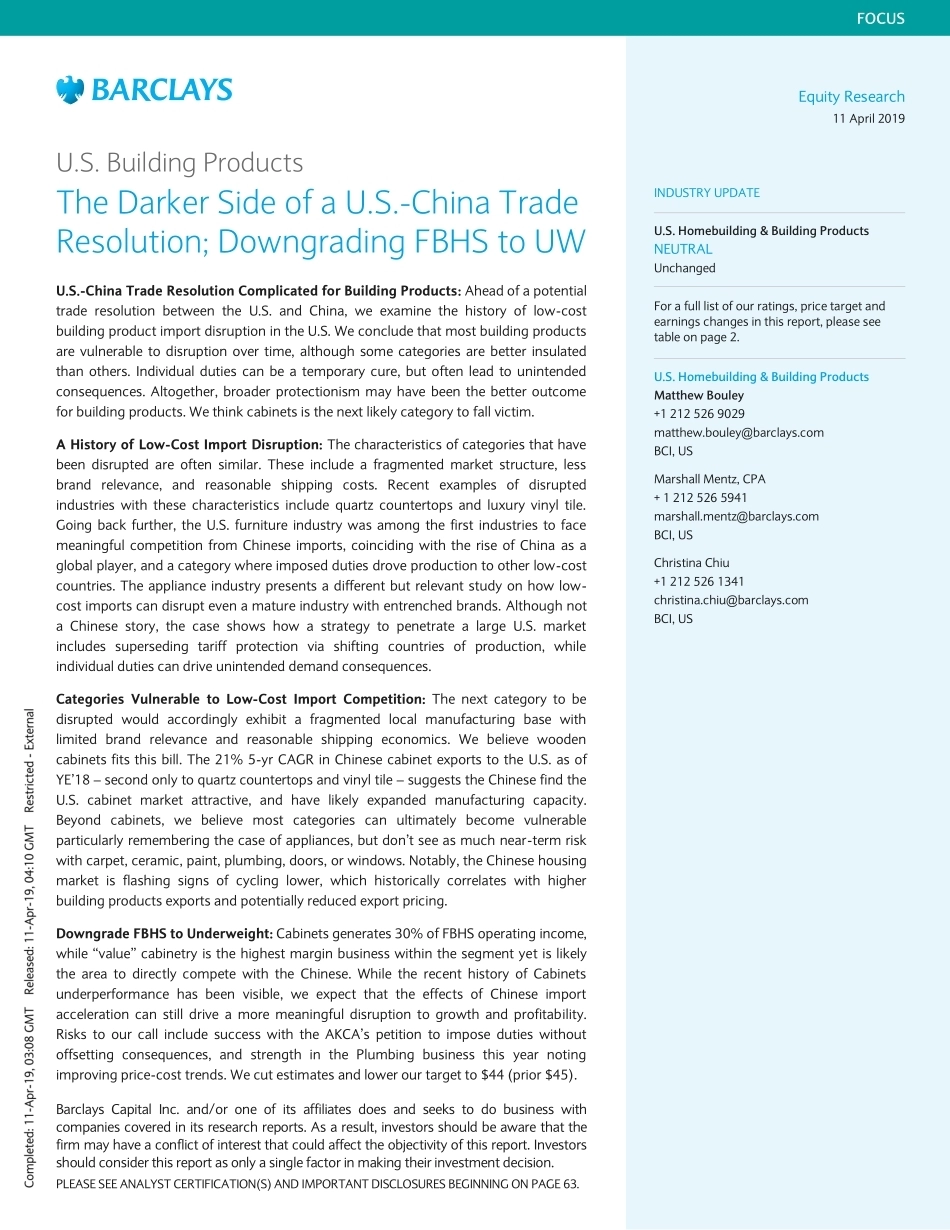
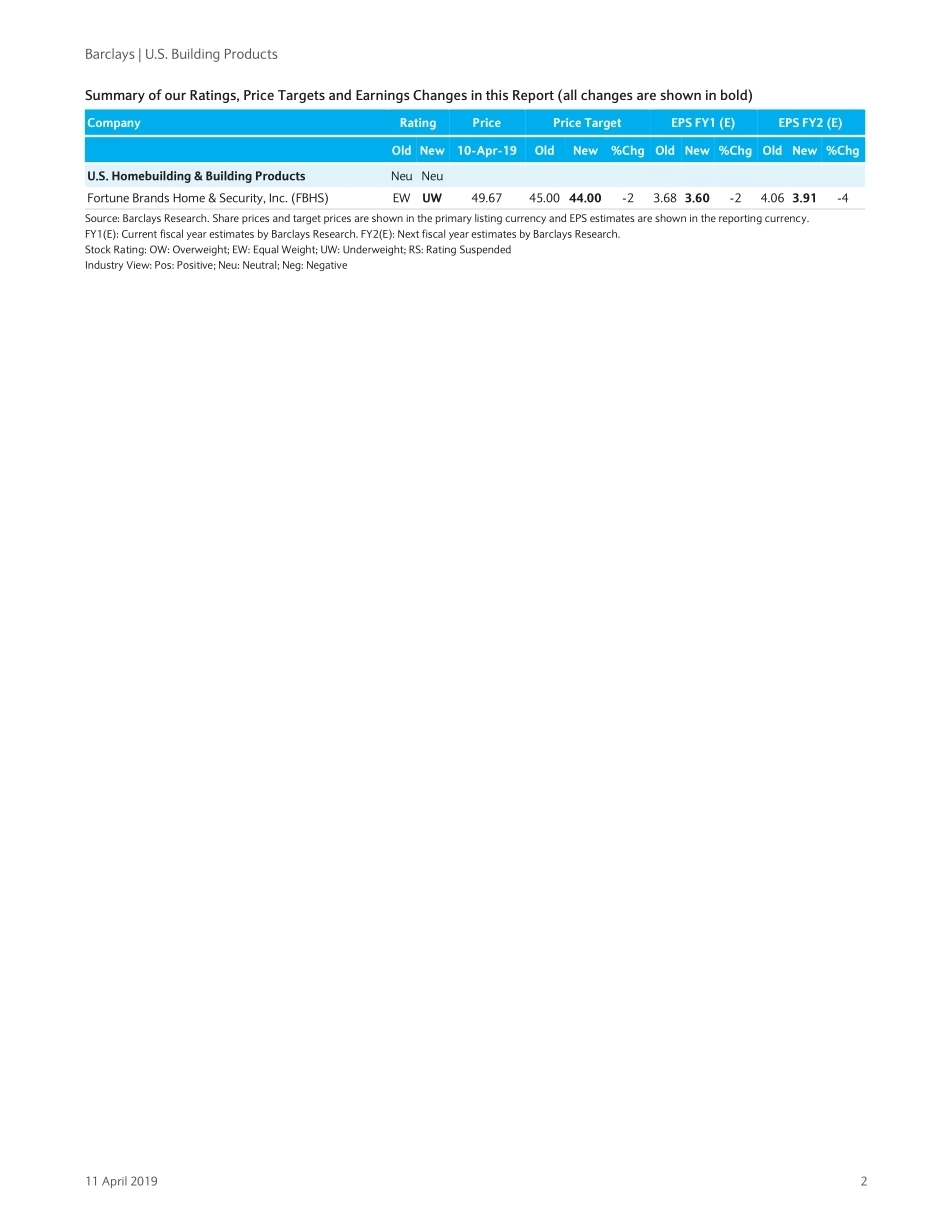
Equity Research 11 April 2019 FOCUS Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 63. Restricted - Internal U.S. Building Products The Darker Side of a U.S.-China Trade Resolution; Downgrading FBHS to UW U.S.-China Trade Resolution Complicated for Building Products: Ahead of a potential trade resolution between the U.S. and China, we examine the history of low-cost building product import disruption in the U.S. We conclude that most building products are vulnerable to disruption over time, although some categories are better insulated than others. Individual duties can be a temporary cure, but often lead to unintended consequences. Altogether, broader protectionism may have been the better outcome for building products. We think cabinets is the next likely category to fall victim. A History of Low-Cost Import Disruption: The characteristics of categories that have been disrupted are often similar. These include a fragmented market structure, less brand relevance, and reasonable shipping costs. Recent examples of disrupted industries with these characteristics include quartz countertops and luxury vinyl tile. Going back further, the U.S. furniture industry was among the first industries to face meaningful competition from Chinese imports, coinciding with the rise of China as a global player, and a category where imposed duties drove production to other low-cost countries. The appliance industry presents a different but relevant study on how low-cost imports can disrupt even a mature industry with entrenched brands. Although not a Chinese story, the case shows how a strategy to penetrate a large U.S. market includes superseding tariff protection via shifting countries of production, while individual duties can drive unintended demand consequences. Categories Vulnerable to Low-Cost Import Competition: The next category to be disrupted would accordingly exhibit a fragmented local manufacturing base with limited brand relevance and reasonable shipping economics. We believe wooden cabinets fits this bill. The 21% 5-yr CAGR in Chinese cabinet exports to the U.S. as of YE’18 – second only to quartz countertops and vinyl tile – suggests the Chinese find the U.S. cabinet market attractive, and have likely expanded manufacturing capacity. Beyond cabinets, we believe most categories can ultimately become vulnerable particularly remembering the case of appliances, but don’t see as much near-term risk with carpet, ceramic, paint, plumbing, doors, or windows. Notably, the Chinese housing market is flashing signs of cycling lower, which historically correlates with higher building products exports and potentially reduced export pricing. Downgrade FBHS to Underweight: Cabinets generates 30% of FBHS operating income, while “value” cabinetry is the highest margin business within the segment yet is likely the area to directly compete with the Chinese. While the recent history of Cabinets underperformance has been visible, we expect that the effects of Chinese import acceleration can still drive a more meaningful disruption to growth and profitability. Risks to our call include success with the AKCA’s petition to impose duties without offsetting consequences, and strength in the Plumbing business this year noting improving price-cost trends. We cut estimates and lower our target to $44 (prior $45). INDUSTRY UPDATE U.S. Homebuilding & Building Products NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. Homebuilding & Building Products Matthew Bouley +1 212 526 9029 matthew.bouley@barclays.com BCI, US Marshall Mentz, CPA + 1 212 526 5941 marshall.mentz@barclays.com BCI, US Christina Chiu +1 212 526 1341 christina.chiu@barclays.com BCI, US 【讯库】扫码免费领取更多[研究报告]、[短视频运营资料]、[职场资源]、[专业课程]【 扫 码 领 取 】Barclays | U.S. Building Products 11 April 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 10-Apr-19 Old New %Chg Old New %Chg Old New %Chg U.S. Homebuilding & Building Products Neu Neu Fortune Brands Home & Security, Inc. (FBHS) EW UW 49.67 45.00 44.00 -2 3.68 3.60 -2 4.06 3.91 -4 Source: Barclays Research. Share prices and target prices are shown in the primary listing currency and EPS estimates are shown in the reporting currency. FY1(E): Current fiscal year estimates by Barclays Research. FY2(E): Next fiscal year estimates by Barclays Research. Stock Rating: OW: Overweight; EW: Equal Weight; UW: Underweight; RS: Rating Suspended Industry Vie...




发表评论取消回复