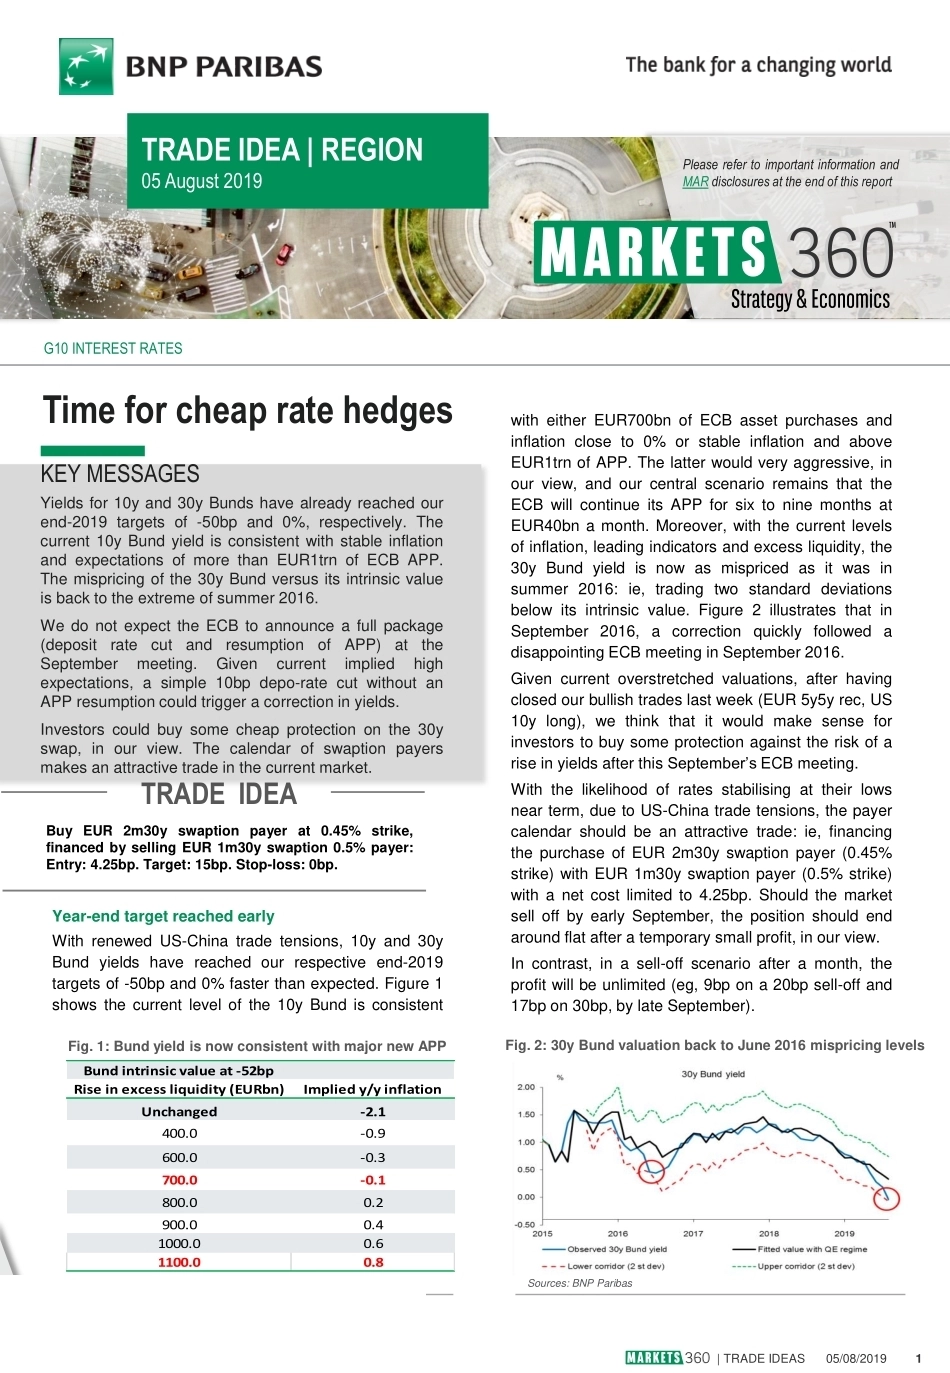
Fig. 2: 30y Bund valuation back to June 2016 mispricing levels Fig. 1: Bund yield is now consistent with major new APP Sources: BNP Paribas Sources: BNP Paribas. | TRADE IDEAS 05/08/2019 1 TRADE IDEA | REGION 05 August 2019 Please refer to important information and MAR disclosures at the end of this report TRADE IDEA KEY MESSAGES Yields for 10y and 30y Bunds have already reached our end-2019 targets of -50bp and 0%, respectively. The current 10y Bund yield is consistent with stable inflation and expectations of more than EUR1trn of ECB APP. The mispricing of the 30y Bund versus its intrinsic value is back to the extreme of summer 2016. We do not expect the ECB to announce a full package (deposit rate cut and resumption of APP) at the September meeting. Given current implied high expectations, a simple 10bp depo-rate cut without an APP resumption could trigger a correction in yields. Investors could buy some cheap protection on the 30y swap, in our view. The calendar of swaption payers makes an attractive trade in the current market. with either EUR700bn of ECB asset purchases and inflation close to 0% or stable inflation and above EUR1trn of APP. The latter would very aggressive, in our view, and our central scenario remains that the ECB will continue its APP for six to nine months at EUR40bn a month. Moreover, with the current levels of inflation, leading indicators and excess liquidity, the 30y Bund yield is now as mispriced as it was in summer 2016: ie, trading two standard deviations below its intrinsic value. Figure 2 illustrates that in September 2016, a correction quickly followed a disappointing ECB meeting in September 2016. Given current overstretched valuations, after having closed our bullish trades last week (EUR 5y5y rec, US 10y long), we think that it would make sense for investors to buy some protection against the risk of a rise in yields after this September’s ECB meeting. With the likelihood of rates stabilising at their lows near term, due to US-China trade tensions, the payer calendar should be an attractive trade: ie, financing the purchase of EUR 2m30y swaption payer (0.45% strike) with EUR 1m30y swaption payer (0.5% strike) with a net cost limited to 4.25bp. Should the market sell off by early September, the position should end around flat after a temporary small profit, in our view. In contrast, in a sell-off scenario after a month, the profit will be unlimited (eg, 9bp on a 20bp sell-off and 17bp on 30bp, by late September). Time for cheap rate hedges Buy EUR 2m30y swaption payer at 0.45% strike, financed by selling EUR 1m30y swaption 0.5% payer: Entry: 4.25bp. Target: 15bp. Stop-loss: 0bp. G10 INTEREST RATES Year-end target reached early With renewed US-China trade tensions, 10y and 30y Bund yields have reached our respective end-2019 targets of -50bp and 0% faster than expected. Figure 1 shows the current level of the 10y Bund is consistent Bund intrinsic value at -52bpRise in excess liquidity (EURbn)Implied y/y inflationUnchanged-2.1400.0-0.9600.0-0.3700.0-0.1800.00.2900.00.41000.00.61100.00.8 Legal Notice This document has been written by our Strategist and Economist teams within the BNP Paribas group of companies (collectively “BNPP”); it does not purport to be an exhaustive analysis, and may be subject to conflicts of interest resulting from their interaction with sales and trading which could affect the objectivity of this report. This document is non-independent research for the purpose of the UK Financial Conduct Authority rules. For the purposes of the recast Markets in Financial Instruments Directive (2014/65/EU) (MiFID II), non-independent research constitutes a marketing communication. This document is not investment research for the purposes of MiFID II. It has not been prepared in accordance with legal requirements designed to provide the independence of investment research, and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The content in this document/communication may also contain “Research” as defined under the MiFID II unbundling rules. If the document/communication contains Research, it is intended for those firms who are either in scope of the MiFID II unbundling rules and have signed up to one of the BNPP Global Markets Research packages, or firms that are out of scope of the MiFID II unbundling rules and therefore not required to pay for Research under MiFID II. Please note that it is your firm’s responsibility to ensure that you do not view or use the Research content in this document if your firm has not signed up to one of the BNPP Global Markets Research packages, except where your firm is out of scope of the MiFID II unbundling rules. STEER™ is a trade mark of BNPP. MARKETS 360 is a trade mark of BNP Paribas This document constitutes a marketing communication and has been prepared by BNPP for, and is directed at, (a) Professional Clients and Eligible Counterparties as defined by the recast Markets in Fina...




发表评论取消回复