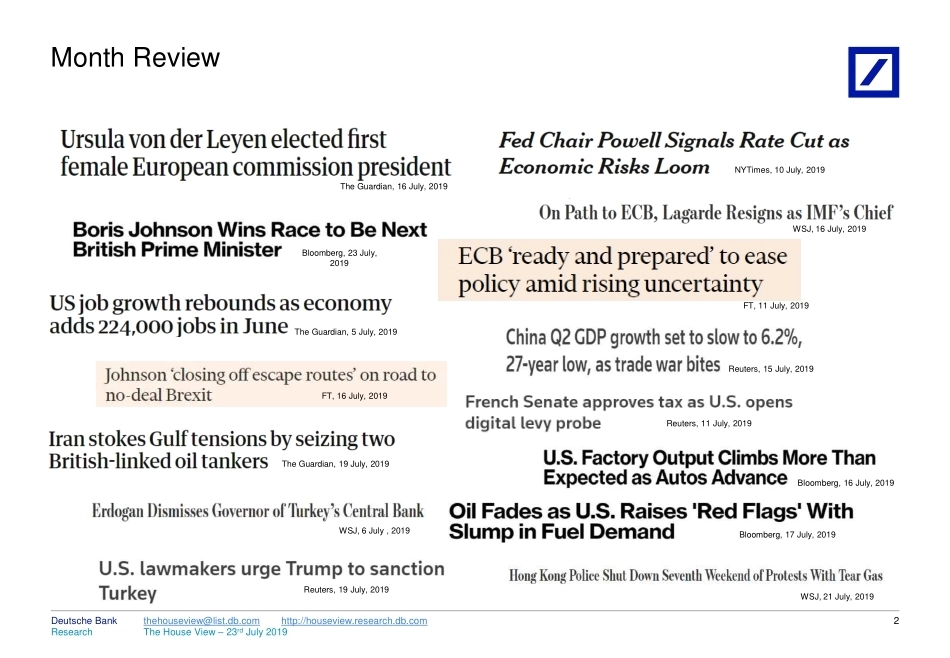
ResearchDeutsche BankThe House View23 July 2019quinn.brody@db.comhimanshu.porwal@db.comjim.reid@db.comDISCLOSURES AND ANALYST CERTIFICATIONS ARE LOCATED IN APPENDIX 1. MCI (P) 066/04/2019Global monetary medicine on the way#PositiveImpactDistributed on: 23/07/2019 17:32:34 GMT7T2se3r0Ot6kwoPa每日免费获取报告1、每日微信群内分享7+最新重磅报告;2、每日分享当日华尔街日报、金融时报;3、每周分享经济学人4、行研报告均为公开版,权利归原作者所有,起点财经仅分发做内部学习。扫一扫二维码关注公号回复:研究报告加入“起点财经”微信群。。 ResearchDeutsche BankThe House View – 23rd July 2019thehouseview@list.db.comhttp://houseview.research.db.com2Month ReviewThe Guardian, 16 July, 2019WSJ, 16 July, 2019NYTimes, 10 July, 2019Reuters, 15 July, 2019The Guardian, 5 July, 2019WSJ, 21 July, 2019FT, 11 July, 2019Bloomberg, 17 July, 2019The Guardian, 19 July, 2019FT, 16 July, 2019WSJ, 6 July , 2019Bloomberg, 16 July, 2019Reuters, 11 July, 2019Reuters, 19 July, 2019Bloomberg, 23 July, 2019ResearchDeutsche BankThe House View – 23rd July 2019thehouseview@list.db.comhttp://houseview.research.db.comThis summer, attention has shifted away from trade wars and politics, back to monetary policy. After a decade of unprecedented policy actions, the world economy still struggles to break free and return to normalcy. In the absence of a plan B, the world’s major central banks are set to engage in simultaneous policy easing yet again, with rate cuts likely in the US, China, and Europe. Asset purchases could be restarted in the euro area before YE as well. In the UK, Brexit is still the driving force, but rate cuts are highly likely, with a return to QE on a hard Brexit (45% probability). The incoming leadership team in Europe complicates matters, but we believe the transition will ultimately prove to be a turning point for Europe. We are highly confident that Christine Lagarde will be a historically successful ECB president at a key juncture. She has a strong track record of consensus-building and pragmatic leadership, surrounding herself with experts and proving to be unafraid of self-criticism and course correction.At the European Commission, Ursula von der Leyen will need to execute on the ambitious suite of reforms that national governments have already endorsed. Both women will face challenges, but the opportunity for an epochal change in European economic policymaking is within reach.In terms of macro fundamentals, the global economy is maintaining momentum in spite of the crosswinds. While trade and manufacturing are under pressure, labour markets in the US and Europe look strong. Ultimately, we expect monetary easing to prolong the current expansion and position for higher equities and steeper yield curves. A major setback in US/China trade talks remains the biggest short-term risk. David Folkerts-Landau, Group Chief Economist3The House View, 23 July 2019Global monetary medicine on the wayThe views in this publication are informed by Deutsche Bank’s Global Strategy Group, which advises management and clients on broad market risks and global economic and financial developments. The views and forecasts of the group, which consists of senior research staff, may occasionally differ from those disseminated by their research colleaguesTable of contentsIntroduction 4-boxes Total returns Macro events calendarMacro update Monetary policy outlook Global outlook Macro update New EU leadership Brexit update Trade war updateMarkets Summary asset views Equities update Rates update FX update Credit update Oil updateForecasts DB ForecastsResearchDeutsche BankThe House View – 23rd July 2019thehouseview@list.db.comhttp://houseview.research.db.com Fed: Three cuts in 2019 (Jul, Sep, and Dec) ECB: 10bps deposit rate cut in September and December, tiering in September, QE a close call BoJ: On hold, no changes in target yields on YCC, possibly well into 2020 BoE: No hike this year, one hike in Aug 2020 PBoC: To cut OMO rates by 10-50bps; Cut RRR once EM: Expect cuts in Russia, South Africa, Turkey, India, Indonesia, Philippines, Vietnam, Brazil, and Chile Global growth is slowing, but still positive – expect 2019 world GDP to grow at 3.2%; central bank policy easing to sustain expansion and limit downside risks US: economic growth slower but above potential – raise full-year 2019 GDP growth forecast by 0.1pp to 2.5%, driven by strong consumption growth Eurozone: Downside risks to already slow growth – some upside risks to Q2 GDP, but caution remains. Expect 2019 GDP growth of 1.1% EM economies are bottoming, but no acceleration in sight – expect 2019 growth at 4.2% Monetary easing: Major central banks are set to engage in simultaneous policy easing this fall to limit slowing growth momentum. Rate cuts likely in the US, Europe and several EM economies Trade war: Some de-escalation recently on US-China trade front, but no signs of a deal as yet. EU auto tariff risk also remains on the table. Truce may be temporary Brexit: Our base case remains a general election this year, but there is increasing uncertainty as to whether this will occur before a...




发表评论取消回复