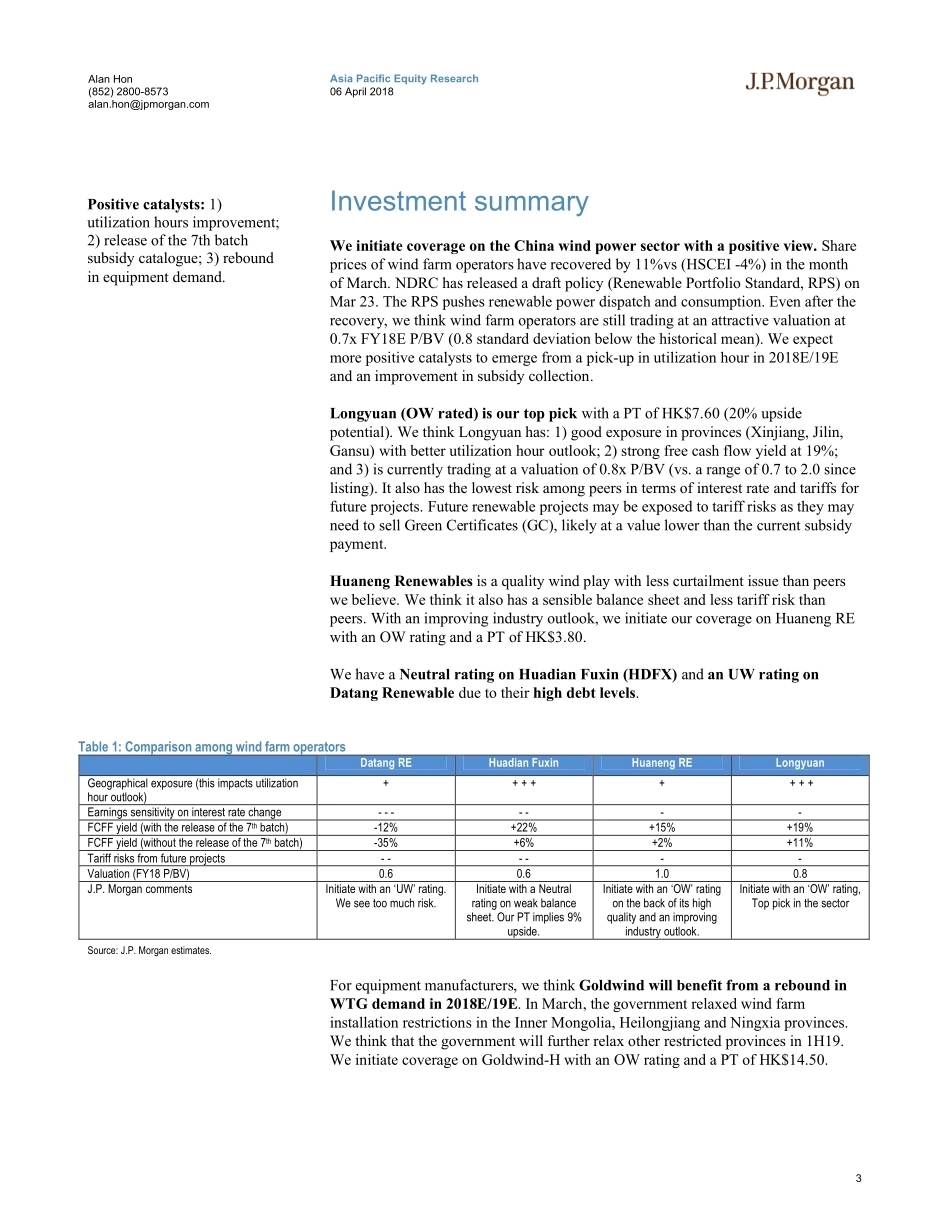
www.jpmorganmarkets.comAsia Pacific Equity Research06 April 2018Equity Ratings and Price TargetsMkt CapPriceRatingPrice TargetCompanyTicker($ mn)CCYPriceCurPrevCurPrevDatang Renewable1798 HK1,093.53HKD1.18UW—1.05—Huadian Fuxin816 HK2,313.85HKD2.16N—2.35—Huaneng Renewables958 HK4,415.68HKD3.28OW—3.80—Longyuan916 HK6,460.73HKD6.31OW—7.60—Xinjiang Goldwind - H2208 HK5,645.41HKD12.46OW—14.50—Source: Company data, Bloomberg, J.P. Morgan estimates. n/c = no change. All prices as of 06 Apr 18.China Wind PowerTailwinds return; initiating coverage [ex A-shares]ChinaUtilities and EnvironmentalAlan Hon AC(852) 2800-8573alan.hon@jpmorgan.comElaine Wu(852) 2800-8575elaine.wu@jpmorgan.comJ.P. Morgan Securities (Asia Pacific) LimitedSee page 91 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.We initiate coverage on the China wind power sector with a positive view.Wind farm operators’ share prices have recovered after NDRC’s publication of a consultation paper on the Renewable Portfolio Standard (RPS) on March 23. RPS will push the grid companies to dispatch more renewable power. Looking ahead, we expect more positive catalysts to emerge from: 1) a rise in utilization hour in 2018E/19E; 2) a collection of overdue subsidies this year; and 3) a rebound in equipment demand. We think valuations are attractive with operators trading at 0.7x 2018E P/BV (~0.8 STD below the historical average.). Our top pick is Longyuan - highly leveraged on utilization hour improvement, with a strong cash flow yield (2018E: 19%) and an attractive valuation at 0.8x 2018E P/BV. We are also positive on Goldwind-H (an equipment maker) on wind-turbine generator (WTG) demand rebound. A rise in utilization hour in 2018E/19E, driven by curtailment (aka grid congestion) improvement. China installed a historically high amount (52GW) of ultra-high voltage (UHV) lines in 2017 (vs. an average of 12GW during 2010-16). This should help dispatch renewable power over a long distance to high demand areas. Together with the new RPS policy, we think grid companies will increase inter-provincial renewable power transfer, alleviating the curtailment issue. Each 1% increase in utilization hour will, on average, improve operators’earnings by 3% we believe. An improved free cash flow from subsidy collection after the release of the 7th batch subsidy catalogue. Wind farm projects need to register with the renewable subsidy catalogue to get payments. Registration results are released in batches. We expect the 7th batch (covering projects commencing operation from Feb-2015 to Mar-2016) to be released in mid-2018. This should improve operators’ free cash flow yield from -4% to +11%. A rebound in equipment demand in 2018E/19E should benefit equipment makers. In March, the government relaxed wind farm installation restrictions in Inner Mongolia, Heilongjiang and Ningxia. We think that the government will further relax other restricted provinces in 1H19. This should lift equipment demand. We initiate coverage on Longyuan and Huaneng RE with OW ratings on an improving industry outlook. We initiate on Goldwind-H with an OW rating on WTG demand rebound. We have Neutral/UW ratings on HDFX/Datang RE on high debt levels. Investment risks: Strong tailwinds could be positive for the whole sector and present upside risk to our ratings and price targets on the stocks we rate N and UW. Other risks: 1) high debt levels vs. rising interest rate/equity issuance risk; 2) tariff risks for future projects; and 3) subsidy uncertainty for later projects.China utilities share price performance(last three months)Source: Bloomberg.-2%0%0%4%11%-10%-5%0%5%10%15%HSCEIIPPWaterWindGasCompleted 06 Apr 2018 11:53 PM HKTDisseminated 07 Apr 2018 12:07 AM HKT2Asia Pacific Equity Research06 April 2018Alan Hon(852) 2800-8573alan.hon@jpmorgan.comTable of ContentsInvestment summary................................................................3Positive #1: A continuous rise in utilization hours in 2018E/19E..............................5Positive #2: Improvement in subsidy delay in 2018E ...............................................7Positive #3: Rebound in equipment demand in 2018E/19E.......................................9Risk #1: Interest rate hike and equity issuance risk.................................................11Risk #2: Future projects may experience tariff risks...............................................12Risk #3: Subsidy collection – projects after Mar-16 ...............................................13Key assumptions and sensitivity analysis...........................16Valuation analysis ..........................................





发表评论取消回复