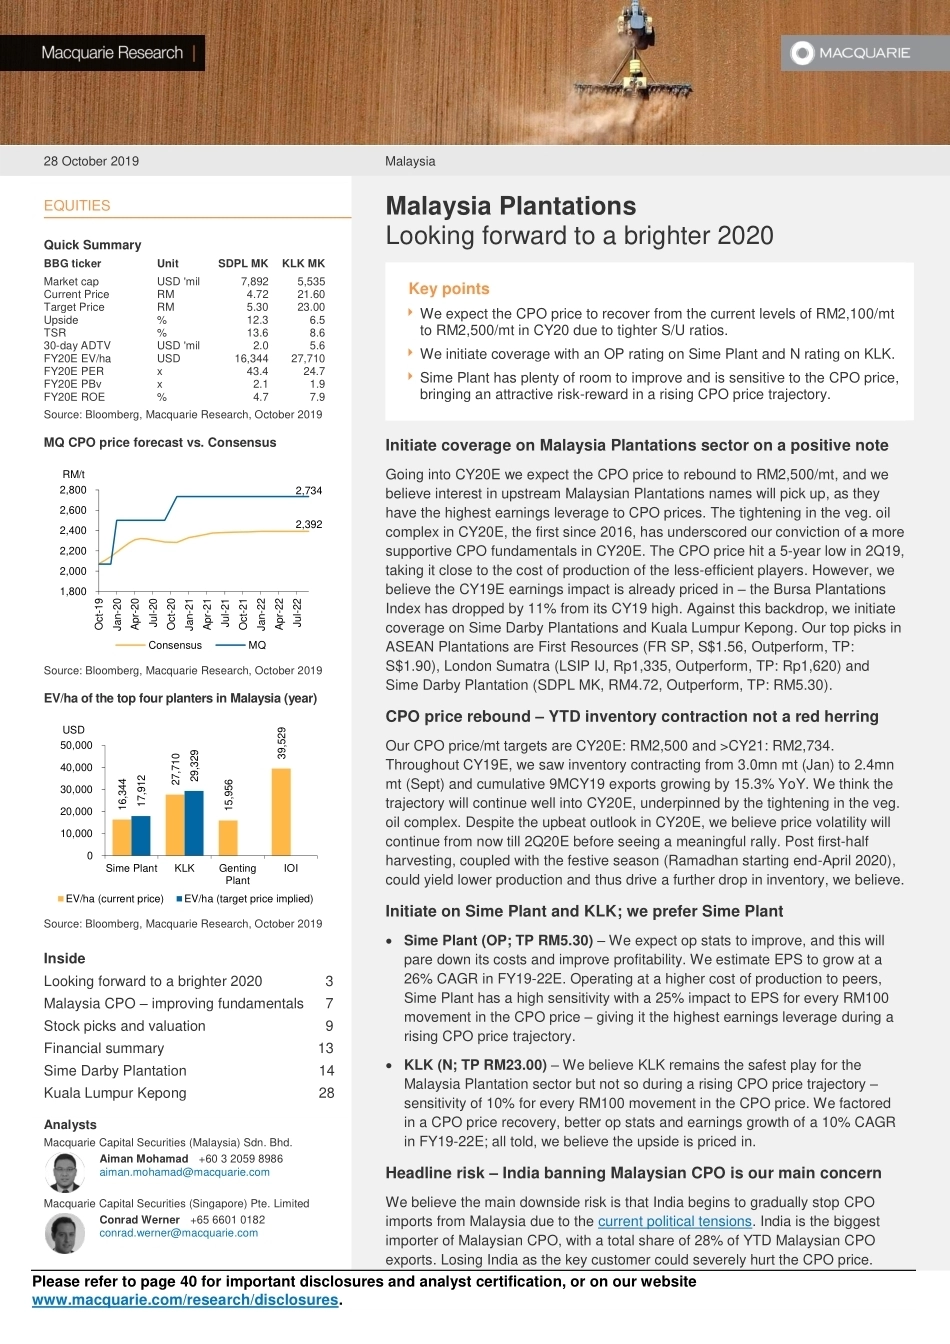
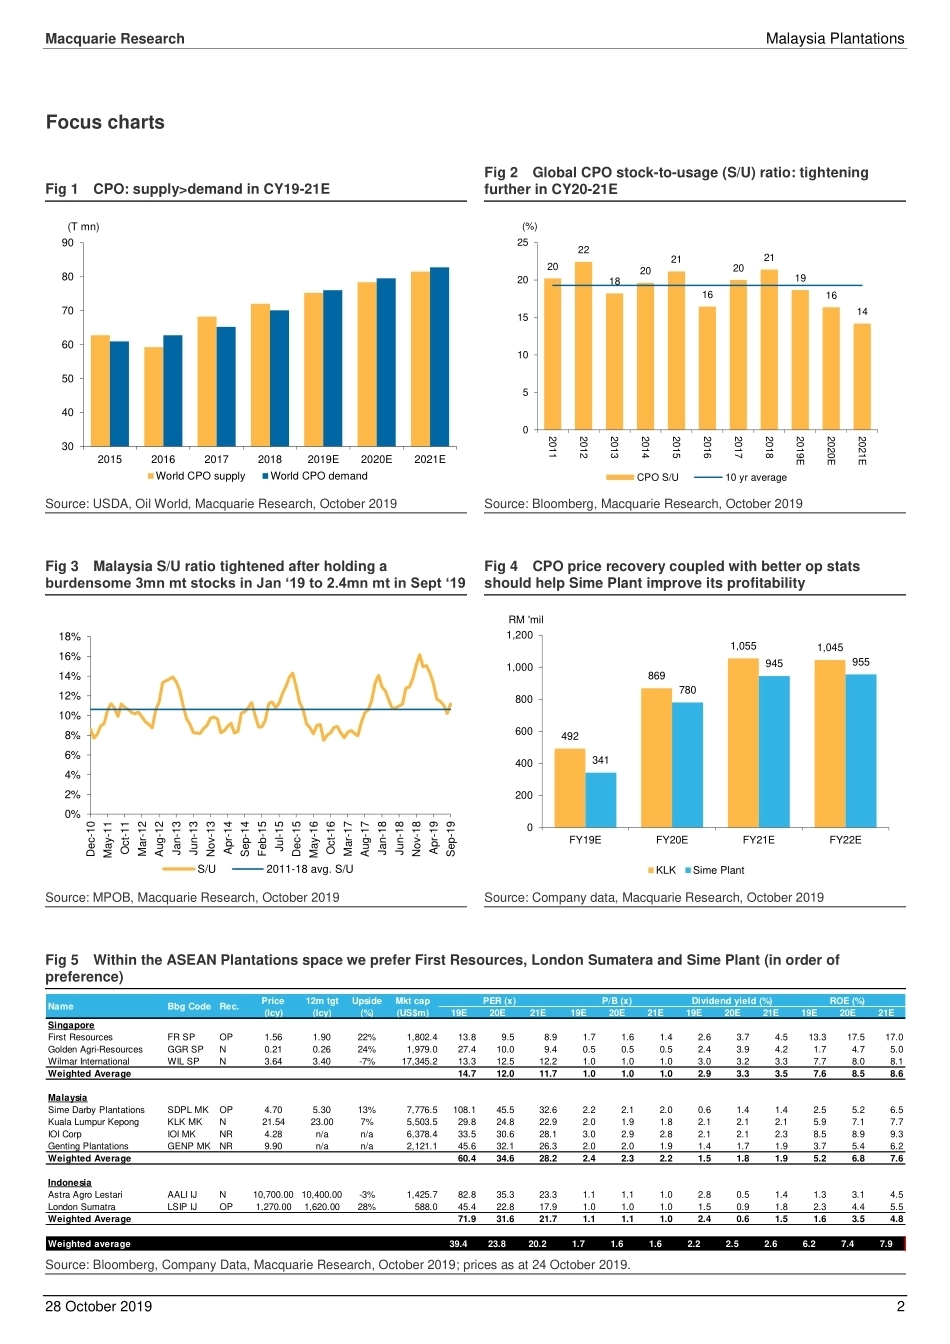
Please refer to page 40 for important disclosures and analyst certification, or on our website www.macquarie.com/research/disclosures. 28 October 2019 Malaysia EQUITIES Quick Summary BBG ticker Unit SDPL MK KLK MK Market cap USD 'mil 7,892 5,535 Current Price RM 4.72 21.60 Target Price RM 5.30 23.00 Upside % 12.3 6.5 TSR % 13.6 8.6 30-day ADTV USD 'mil 2.0 5.6 FY20E EV/ha USD 16,344 27,710 FY20E PER x 43.4 24.7 FY20E PBv x 2.1 1.9 FY20E ROE % 4.7 7.9 Source: Bloomberg, Macquarie Research, October 2019 MQ CPO price forecast vs. Consensus Source: Bloomberg, Macquarie Research, October 2019 EV/ha of the top four planters in Malaysia (year) Source: Bloomberg, Macquarie Research, October 2019 Inside Looking forward to a brighter 2020 3 Malaysia CPO – improving fundamentals 7 Stock picks and valuation 9 Financial summary 13 Sime Darby Plantation 14 Kuala Lumpur Kepong 28 Analysts Macquarie Capital Securities (Malaysia) Sdn. Bhd. Aiman Mohamad +60 3 2059 8986 aiman.mohamad@macquarie.com Macquarie Capital Securities (Singapore) Pte. Limited Conrad Werner +65 6601 0182 conrad.werner@macquarie.com Malaysia Plantations Looking forward to a brighter 2020 Key points We expect the CPO price to recover from the current levels of RM2,100/mt to RM2,500/mt in CY20 due to tighter S/U ratios. We initiate coverage with an OP rating on Sime Plant and N rating on KLK. Sime Plant has plenty of room to improve and is sensitive to the CPO price, bringing an attractive risk-reward in a rising CPO price trajectory. Initiate coverage on Malaysia Plantations sector on a positive note Going into CY20E we expect the CPO price to rebound to RM2,500/mt, and we believe interest in upstream Malaysian Plantations names will pick up, as they have the highest earnings leverage to CPO prices. The tightening in the veg. oil complex in CY20E, the first since 2016, has underscored our conviction of a more supportive CPO fundamentals in CY20E. The CPO price hit a 5-year low in 2Q19, taking it close to the cost of production of the less-efficient players. However, we believe the CY19E earnings impact is already priced in – the Bursa Plantations Index has dropped by 11% from its CY19 high. Against this backdrop, we initiate coverage on Sime Darby Plantations and Kuala Lumpur Kepong. Our top picks in ASEAN Plantations are First Resources (FR SP, S$1.56, Outperform, TP: S$1.90), London Sumatra (LSIP IJ, Rp1,335, Outperform, TP: Rp1,620) and Sime Darby Plantation (SDPL MK, RM4.72, Outperform, TP: RM5.30). CPO price rebound – YTD inventory contraction not a red herring Our CPO price/mt targets are CY20E: RM2,500 and >CY21: RM2,734. Throughout CY19E, we saw inventory contracting from 3.0mn mt (Jan) to 2.4mn mt (Sept) and cumulative 9MCY19 exports growing by 15.3% YoY. We think the trajectory will continue well into CY20E, underpinned by the tightening in the veg. oil complex. Despite the upbeat outlook in CY20E, we believe price volatility will continue from now till 2Q20E before seeing a meaningful rally. Post first-half harvesting, coupled with the festive season (Ramadhan starting end-April 2020), could yield lower production and thus drive a further drop in inventory, we believe. Initiate on Sime Plant and KLK; we prefer Sime Plant Sime Plant (OP; TP RM5.30) – We expect op stats to improve, and this will pare down its costs and improve profitability. We estimate EPS to grow at a 26% CAGR in FY19-22E. Operating at a higher cost of production to peers, Sime Plant has a high sensitivity with a 25% impact to EPS for every RM100 movement in the CPO price – giving it the highest earnings leverage during a rising CPO price trajectory. KLK (N; TP RM23.00) – We believe KLK remains the safest play for the Malaysia Plantation sector but not so during a rising CPO price trajectory – sensitivity of 10% for every RM100 movement in the CPO price. We factored in a CPO price recovery, better op stats and earnings growth of a 10% CAGR in FY19-22E; all told, we believe the upside is priced in. Headline risk – India banning Malaysian CPO is our main concern We believe the main downside risk is that India begins to gradually stop CPO imports from Malaysia due to the current political tensions. India is the biggest importer of Malaysian CPO, with a total share of 28% of YTD Malaysian CPO exports. Losing India as the key customer could severely hurt the CPO price. 2,392 2,734 1,8002,0002,2002,4002,6002,800Oct-19Jan-20Apr-20Jul-20Oct-20Jan-21Apr-21Jul-21Oct-21Jan-22Apr-22Jul-22RM/tConsensusMQ16,344 27,710 15,956 39,529 17,912 29,329 010,00020,00030,00040,00050,000Sime PlantKLKGentingPlantIOIUSDEV/ha (current price)EV/ha (target price implied)Macquarie Research Malaysia Plantations 28 October 2019 2 Focus charts Fig 1 CPO: supply>demand in CY19-21E Fig 2 Global CPO stock-to-usage (S/U) ratio: tightening further in CY20-21E Source: USDA, Oil World, Macquarie Research, October 2019 Source: Bloomberg, Macquarie Research, October 2019 Fig 3 Malaysia S/U ratio tightened af...




发表评论取消回复