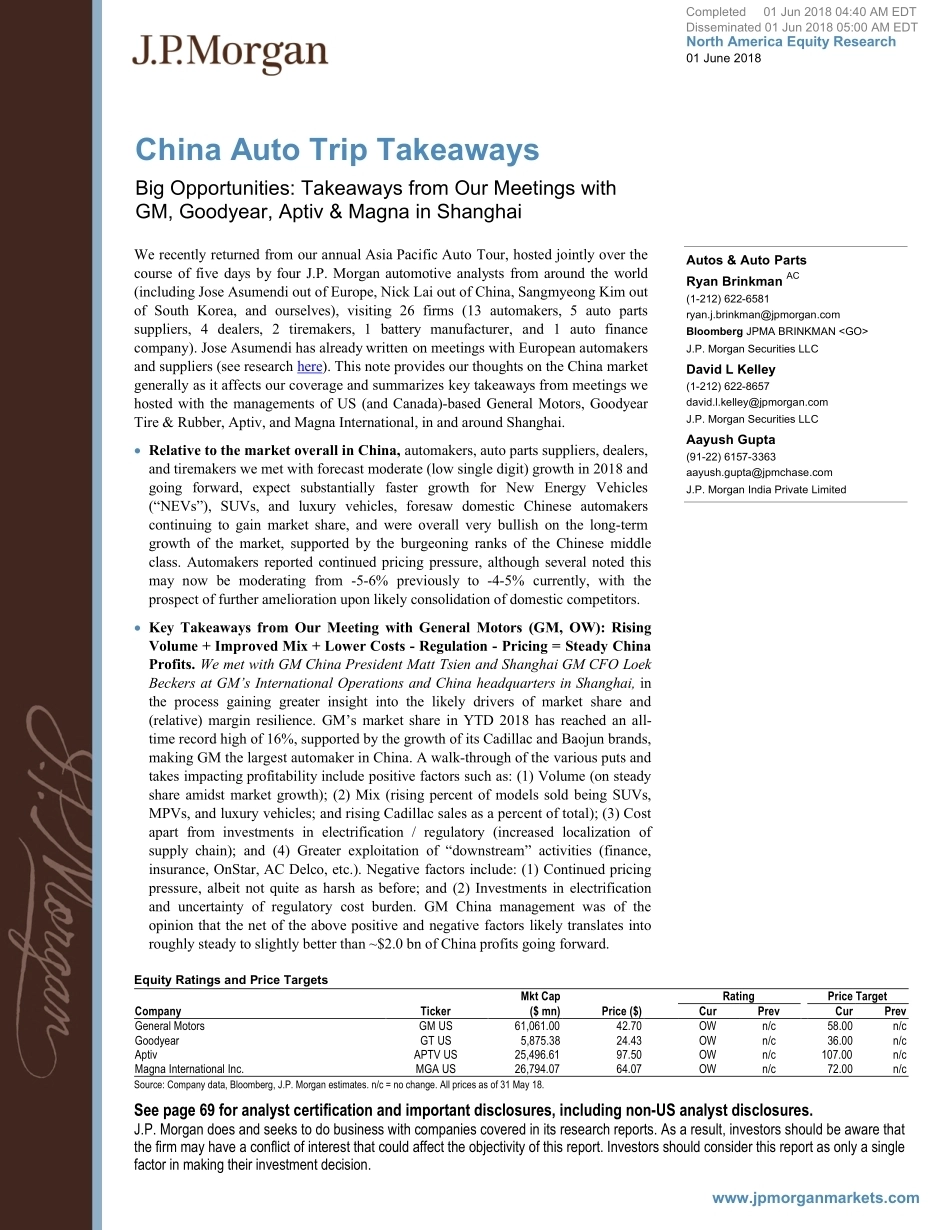
www.jpmorganmarkets.comNorth America Equity Research01 June 2018Equity Ratings and Price TargetsMkt CapRatingPrice TargetCompanyTicker($ mn)Price ($)CurPrevCurPrevGeneral MotorsGM US61,061.0042.70OWn/c58.00n/cGoodyearGT US5,875.3824.43OWn/c36.00n/cAptivAPTV US25,496.6197.50OWn/c107.00n/cMagna International Inc.MGA US26,794.0764.07OWn/c72.00n/cSource: Company data, Bloomberg, J.P. Morgan estimates. n/c = no change. All prices as of 31 May 18.China Auto Trip TakeawaysBig Opportunities: Takeaways from Our Meetings with GM, Goodyear, Aptiv & Magna in ShanghaiAutos & Auto PartsRyan Brinkman AC(1-212) 622-6581ryan.j.brinkman@jpmorgan.comBloomberg JPMA BRINKMAN J.P. Morgan Securities LLCDavid L Kelley(1-212) 622-8657david.l.kelley@jpmorgan.comJ.P. Morgan Securities LLCAayush Gupta(91-22) 6157-3363aayush.gupta@jpmchase.comJ.P. Morgan India Private LimitedSee page 69 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.We recently returned from our annual Asia Pacific Auto Tour, hosted jointly over the course of five days by four J.P. Morgan automotive analysts from around the world (including Jose Asumendi out of Europe, Nick Lai out of China, Sangmyeong Kim out of South Korea, and ourselves), visiting 26 firms (13 automakers, 5 auto parts suppliers, 4 dealers, 2 tiremakers, 1 battery manufacturer, and 1 auto finance company). Jose Asumendi has already written on meetings with European automakers and suppliers (see research here). This note provides our thoughts on the China market generally as it affects our coverage and summarizes key takeaways from meetings we hosted with the managements of US (and Canada)-based General Motors, Goodyear Tire & Rubber, Aptiv, and Magna International, in and around Shanghai.! Relative to the market overall in China, automakers, auto parts suppliers, dealers, and tiremakers we met with forecast moderate (low single digit) growth in 2018 and going forward, expect substantially faster growth for New Energy Vehicles (“NEVs”), SUVs, and luxury vehicles, foresaw domestic Chinese automakers continuing to gain market share, and were overall very bullish on the long-term growth of the market, supported by the burgeoning ranks of the Chinese middle class. Automakers reported continued pricing pressure, although several noted this may now be moderating from -5-6% previously to -4-5% currently, with the prospect of further amelioration upon likely consolidation of domestic competitors. ! Key Takeaways from Our Meeting with General Motors (GM, OW): Rising Volume + Improved Mix + Lower Costs - Regulation - Pricing = Steady China Profits. We met with GM China President Matt Tsien and Shanghai GM CFO Loek Beckers at GM’s International Operations and China headquarters in Shanghai, in the process gaining greater insight into the likely drivers of market share and (relative) margin resilience. GM’s market share in YTD 2018 has reached an all-time record high of 16%, supported by the growth of its Cadillac and Baojun brands, making GM the largest automaker in China. A walk-through of the various puts and takes impacting profitability include positive factors such as: (1) Volume (on steady share amidst market growth); (2) Mix (rising percent of models sold being SUVs, MPVs, and luxury vehicles; and rising Cadillac sales as a percent of total); (3) Cost apart from investments in electrification / regulatory (increased localization of supply chain); and (4) Greater exploitation of “downstream” activities (finance, insurance, OnStar, AC Delco, etc.). Negative factors include: (1) Continued pricing pressure, albeit not quite as harsh as before; and (2) Investments in electrification and uncertainty of regulatory cost burden. GM China management was of the opinion that the net of the above positive and negative factors likely translates into roughly steady to slightly better than ~$2.0 bn of China profits going forward.Completed 01 Jun 2018 04:40 AM EDTDisseminated 01 Jun 2018 05:00 AM EDT2North America Equity Research01 June 2018Ryan Brinkman(1-212) 622-6581ryan.j.brinkman@jpmorgan.com! GM reported on 7 key trends shaping the auto market in China: (1) Consumers are moving toward larger families — this is driving demand for more 3-row SUVs and MPVs, benefitting mix; (2) Consumers are pursuing prestige — this is driving the move toward luxury vehicles, benefitting mix; (3) Consumers have increasing purchasing power — this is driving overall auto sales (especially in Tier 3 / Tier 4 cities) and benefitting mix; (4) Consumers are increasingly connected and digitally empowered —this is driving the increasingly connected nature of vehicles; (5) Consumer...




发表评论取消回复