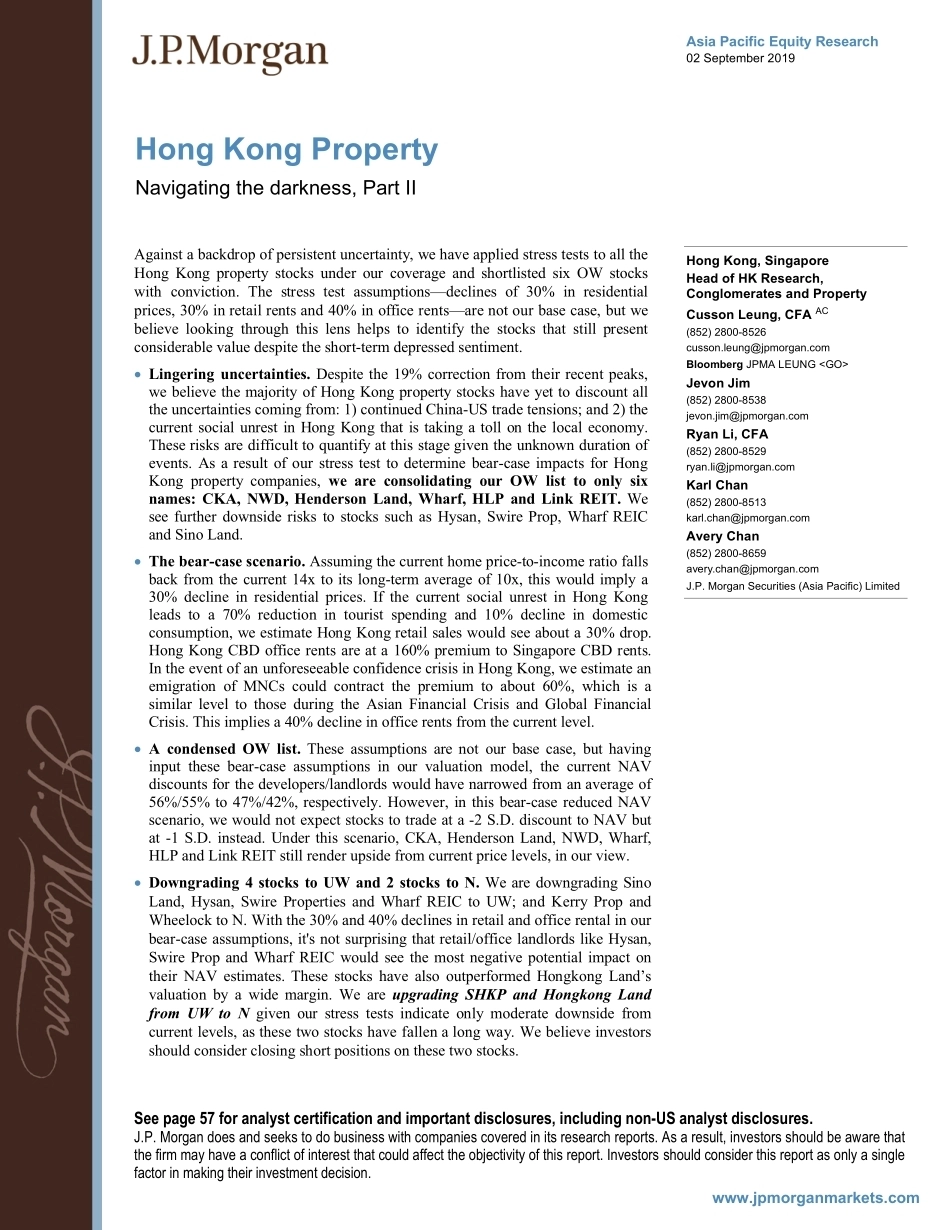
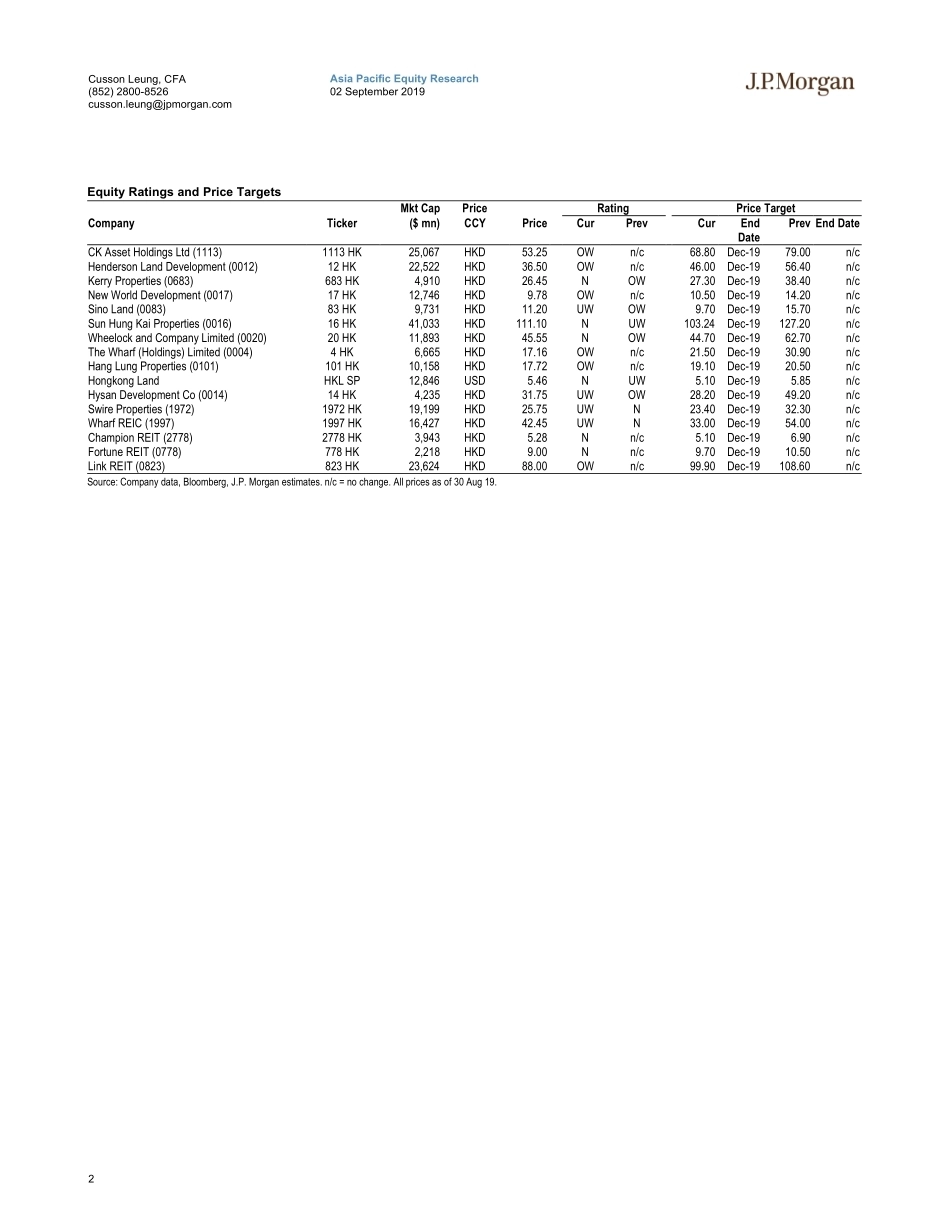
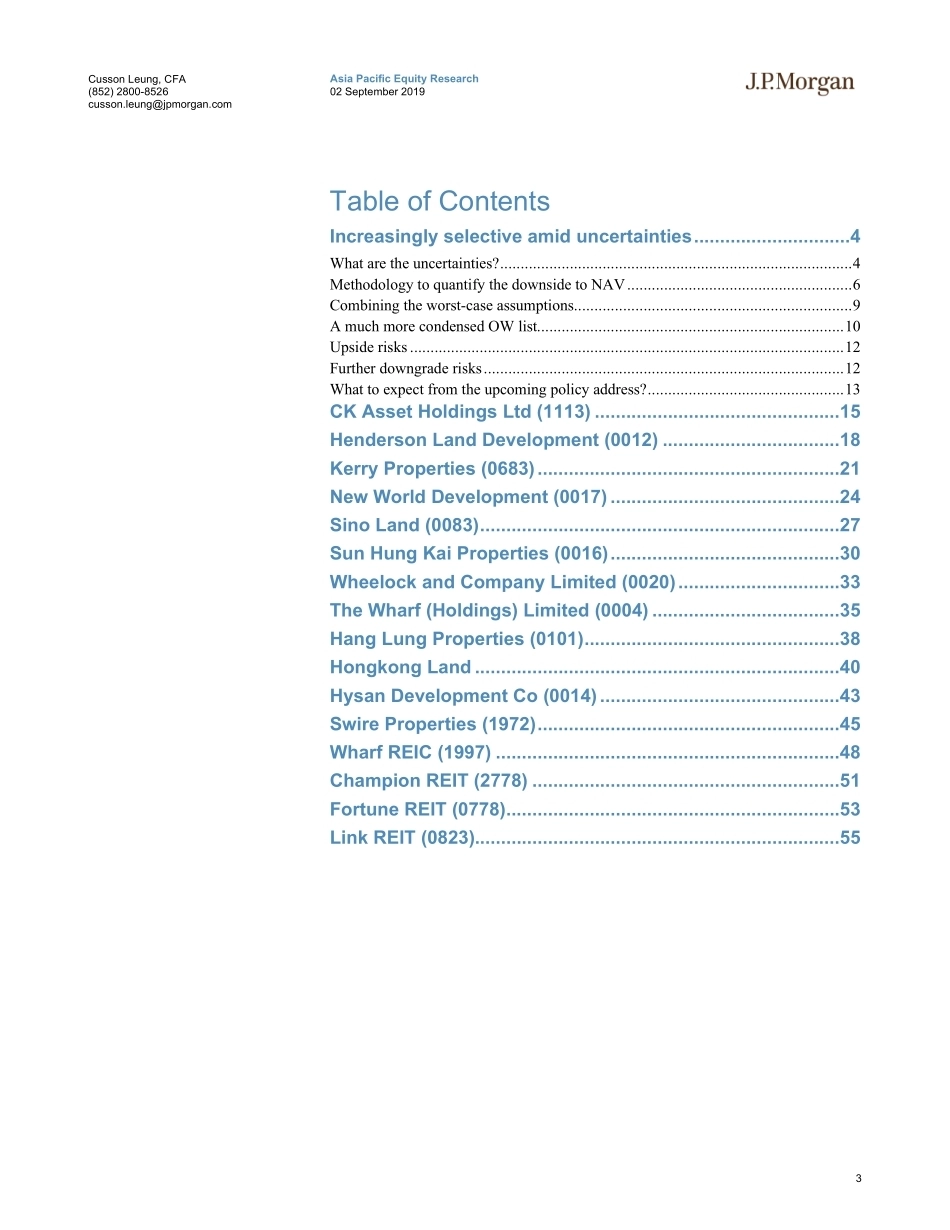
www.jpmorganmarkets.comAsia Pacific Equity Research02 September 2019Hong Kong PropertyNavigating the darkness, Part IIHong Kong, SingaporeHead of HK Research, Conglomerates and PropertyCusson Leung, CFA AC(852) 2800-8526cusson.leung@jpmorgan.comBloomberg JPMA LEUNG Jevon Jim(852) 2800-8538jevon.jim@jpmorgan.comRyan Li, CFA(852) 2800-8529ryan.li@jpmorgan.comKarl Chan(852) 2800-8513karl.chan@jpmorgan.comAvery Chan(852) 2800-8659avery.chan@jpmorgan.comJ.P. Morgan Securities (Asia Pacific) LimitedSee page 57 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.Against a backdrop of persistent uncertainty, we have applied stress tests to all the Hong Kong property stocks under our coverage and shortlisted six OW stocks with conviction. The stress test assumptions—declines of 30% in residential prices, 30% in retail rents and 40% in office rents—are not our base case, but we believe looking through this lens helps to identify the stocks that still present considerable value despite the short-term depressed sentiment. Lingering uncertainties. Despite the 19% correction from their recent peaks, we believe the majority of Hong Kong property stocks have yet to discount all the uncertainties coming from: 1) continued China-US trade tensions; and 2) the current social unrest in Hong Kong that is taking a toll on the local economy. These risks are difficult to quantify at this stage given the unknown duration of events. As a result of our stress test to determine bear-case impacts for Hong Kong property companies, we are consolidating our OW list to only six names: CKA, NWD, Henderson Land, Wharf, HLP and Link REIT. We see further downside risks to stocks such as Hysan, Swire Prop, Wharf REIC and Sino Land. The bear-case scenario. Assuming the current home price-to-income ratio fallsback from the current 14x to its long-term average of 10x, this would imply a 30% decline in residential prices. If the current social unrest in Hong Kong leads to a 70% reduction in tourist spending and 10% decline in domestic consumption, we estimate Hong Kong retail sales would see about a 30% drop. Hong Kong CBD office rents are at a 160% premium to Singapore CBD rents. In the event of an unforeseeable confidence crisis in Hong Kong, we estimate an emigration of MNCs could contract the premium to about 60%, which is a similar level to those during the Asian Financial Crisis and Global Financial Crisis. This implies a 40% decline in office rents from the current level. A condensed OW list. These assumptions are not our base case, but having input these bear-case assumptions in our valuation model, the current NAV discounts for the developers/landlords would have narrowed from an average of 56%/55% to 47%/42%, respectively. However, in this bear-case reduced NAV scenario, we would not expect stocks to trade at a -2 S.D. discount to NAV but at -1 S.D. instead. Under this scenario, CKA, Henderson Land, NWD, Wharf, HLP and Link REIT still render upside from current price levels, in our view. Downgrading 4 stocks to UW and 2 stocks to N. We are downgrading Sino Land, Hysan, Swire Properties and Wharf REIC to UW; and Kerry Prop and Wheelock to N. With the 30% and 40% declines in retail and office rental in our bear-case assumptions, it's not surprising that retail/office landlords like Hysan, Swire Prop and Wharf REIC would see the most negative potential impact on their NAV estimates. These stocks have also outperformed Hongkong Land’s valuation by a wide margin. We are upgrading SHKP and Hongkong Land from UW to N given our stress tests indicate only moderate downside from current levels, as these two stocks have fallen a long way. We believe investors should consider closing short positions on these two stocks.2Asia Pacific Equity Research02 September 2019Cusson Leung, CFA(852) 2800-8526cusson.leung@jpmorgan.comEquity Ratings and Price TargetsMkt CapPriceRatingPrice TargetCompanyTicker($ mn)CCYPriceCurPrevCurEnd DatePrev End DateCK Asset Holdings Ltd (1113)1113 HK25,067HKD53.25OWn/c68.80Dec-1979.00n/cHenderson Land Development (0012)12 HK22,522HKD36.50OWn/c46.00Dec-1956.40n/cKerry Properties (0683)683 HK4,910HKD26.45NOW27.30Dec-1938.40n/cNew World Development (0017)17 HK12,746HKD9.78OWn/c10.50Dec-1914.20n/cSino Land (0083)83 HK9,731HKD11.20UWOW9.70Dec-1915.70n/cSun Hung Kai Properties (0016)16 HK41,033HKD111.10NUW103.24Dec-19127.20n/cWheelock and Company Limited (0020)20 HK11,893HKD45.55NOW44.70Dec-1962.70n/cThe Wharf (Holdings) Limited (0004)4 HK6,665HKD17.16OWn/c21.50Dec-1930.90n/cHang Lung Properties (0101)101 HK10,158HKD17.72OWn/c19.10Dec-1920.50n/cHongkong LandHKL SP12,846US...




发表评论取消回复