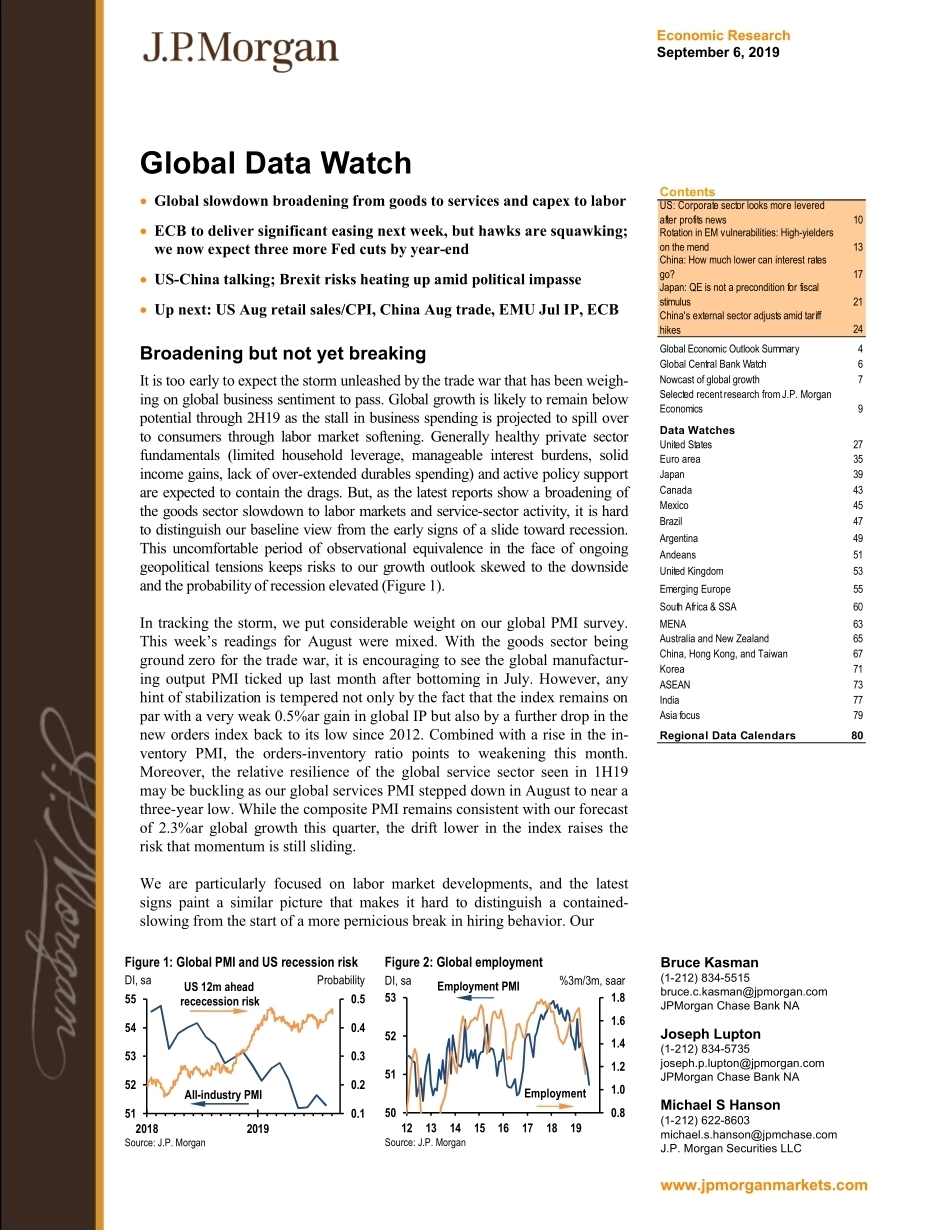
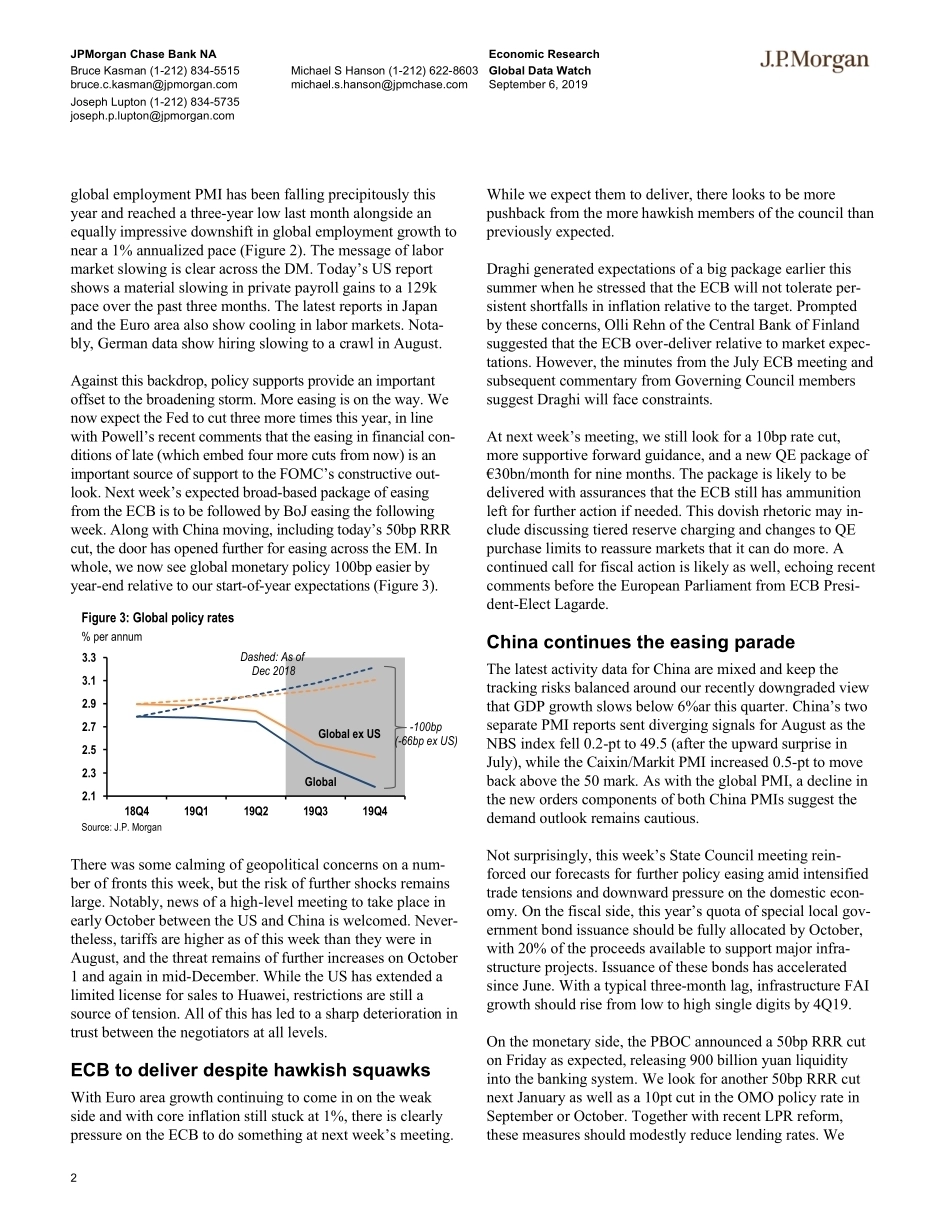
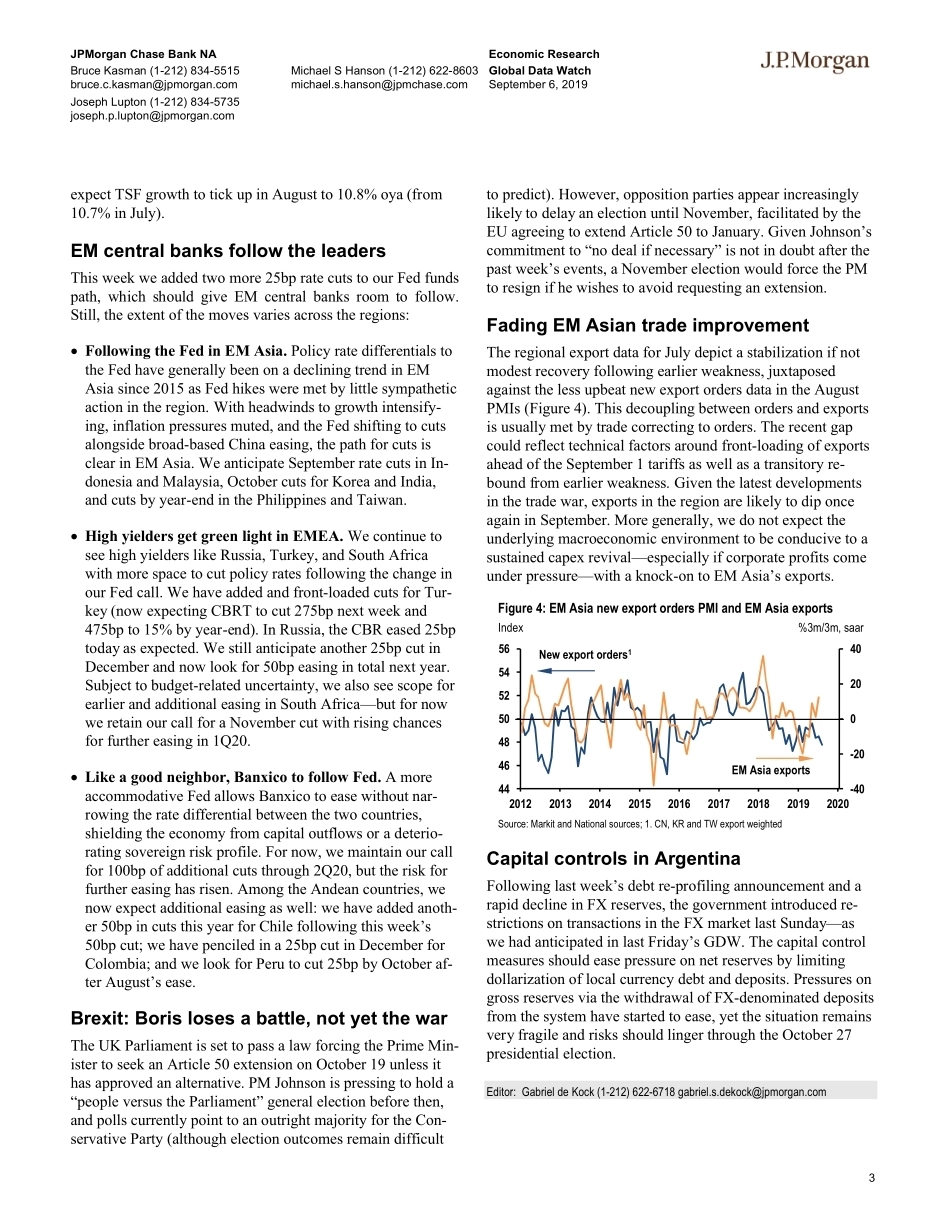
Economic ResearchSeptember 6, 2019Global Data Watch Global slowdown broadening from goods to services and capex to labor ECB to deliver significant easing next week, but hawks are squawking; we now expect three more Fed cuts by year-end US-China talking; Brexit risks heating up amid political impasse Up next: US Aug retail sales/CPI, China Aug trade, EMU Jul IP, ECB Broadening but not yet breakingIt is too early to expect the storm unleashed by the trade war that has been weigh-ing on global business sentiment to pass. Global growth is likely to remain below potential through 2H19 as the stall in business spending is projected to spill over to consumers through labor market softening. Generally healthy private sector fundamentals (limited household leverage, manageable interest burdens, solid income gains, lack of over-extended durables spending) and active policy support are expected to contain the drags. But, as the latest reports show a broadening of the goods sector slowdown to labor markets and service-sector activity, it is hard to distinguish our baseline view from the early signs of a slide toward recession. This uncomfortable period of observational equivalence in the face of ongoing geopolitical tensions keeps risks to our growth outlook skewed to the downside and the probability of recession elevated (Figure 1).In tracking the storm, we put considerable weight on our global PMI survey. This week’s readings for August were mixed. With the goods sector being ground zero for the trade war, it is encouraging to see the global manufactur-ing output PMI ticked up last month after bottoming in July. However, any hint of stabilization is tempered not only by the fact that the index remains on par with a very weak 0.5%ar gain in global IP but also by a further drop in the new orders index back to its low since 2012. Combined with a rise in the in-ventory PMI, the orders-inventory ratio points to weakening this month. Moreover, the relative resilience of the global service sector seen in 1H19 may be buckling as our global services PMI stepped down in August to near a three-year low. While the composite PMI remains consistent with our forecast of 2.3%ar global growth this quarter, the drift lower in the index raises the risk that momentum is still sliding. We are particularly focused on labor market developments, and the latest signs paint a similar picture that makes it hard to distinguish a contained-slowing from the start of a more pernicious break in hiring behavior. Our0.10.20.30.40.5515253545520182019DI, saFigure 1: Global PMI and US recession riskProbabilitySource: J.P. MorganAll-industry PMIUS 12m ahead rececession risk0.81.01.21.41.61.8505152531213141516171819DI, saFigure 2: Global employment%3m/3m, saarSource: J.P. MorganEmployment PMIEmploymentContentsUS: Corporate sector looks more levered after profits news10Rotation in EM vulnerabilities: High-yielders on the mend13China: How much lower can interest rates go?17Japan: QE is not a precondition for fiscal stimulus21China's external sector adjusts amid tariff hikes24Global Economic Outlook Summary4Global Central Bank Watch6Nowcast of global growth7Selected recent research from J.P. Morgan Economics9Data WatchesUnited States27Euro area35Japan39Canada43Mexico45Brazil47Argentina49Andeans51United Kingdom53Emerging Europe55South Africa & SSA60MENA63Australia and New Zealand65China, Hong Kong, and Taiwan67Korea71ASEAN73India77Asia focus79Regional Data Calendars80Bruce Kasman(1-212) 834-5515bruce.c.kasman@jpmorgan.comJPMorgan Chase Bank NAJoseph Lupton(1-212) 834-5735joseph.p.lupton@jpmorgan.comJPMorgan Chase Bank NAMichael S Hanson(1-212) 622-8603michael.s.hanson@jpmchase.comJ.P. Morgan Securities LLCwww.jpmorganmarkets.com2Economic ResearchGlobal Data WatchSeptember 6, 2019JPMorgan Chase Bank NABruce Kasman (1-212) 834-5515bruce.c.kasman@jpmorgan.comJoseph Lupton (1-212) 834-5735joseph.p.lupton@jpmorgan.comMichael S Hanson (1-212) 622-8603michael.s.hanson@jpmchase.comglobal employment PMI has been falling precipitously this year and reached a three-year low last month alongside an equally impressive downshift in global employment growth to near a 1% annualized pace (Figure 2). The message of labor market slowing is clear across the DM. Today’s US report shows a material slowing in private payroll gains to a 129k pace over the past three months. The latest reports in Japan and the Euro area also show cooling in labor markets. Nota-bly, German data show hiring slowing to a crawl in August. Against this backdrop, policy supports provide an important offset to the broadening storm. More easing is on the way. We now expect the Fed to cut three more times this year, in line with Powell’s recent comments that the easing in financial con-ditions of late (which embed four more cuts from now) is an important source of support to the FOMC’s constructive out-look. Next week’s expected broad-based package of easing from the ECB is to be followed by BoJ easing t...




发表评论取消回复