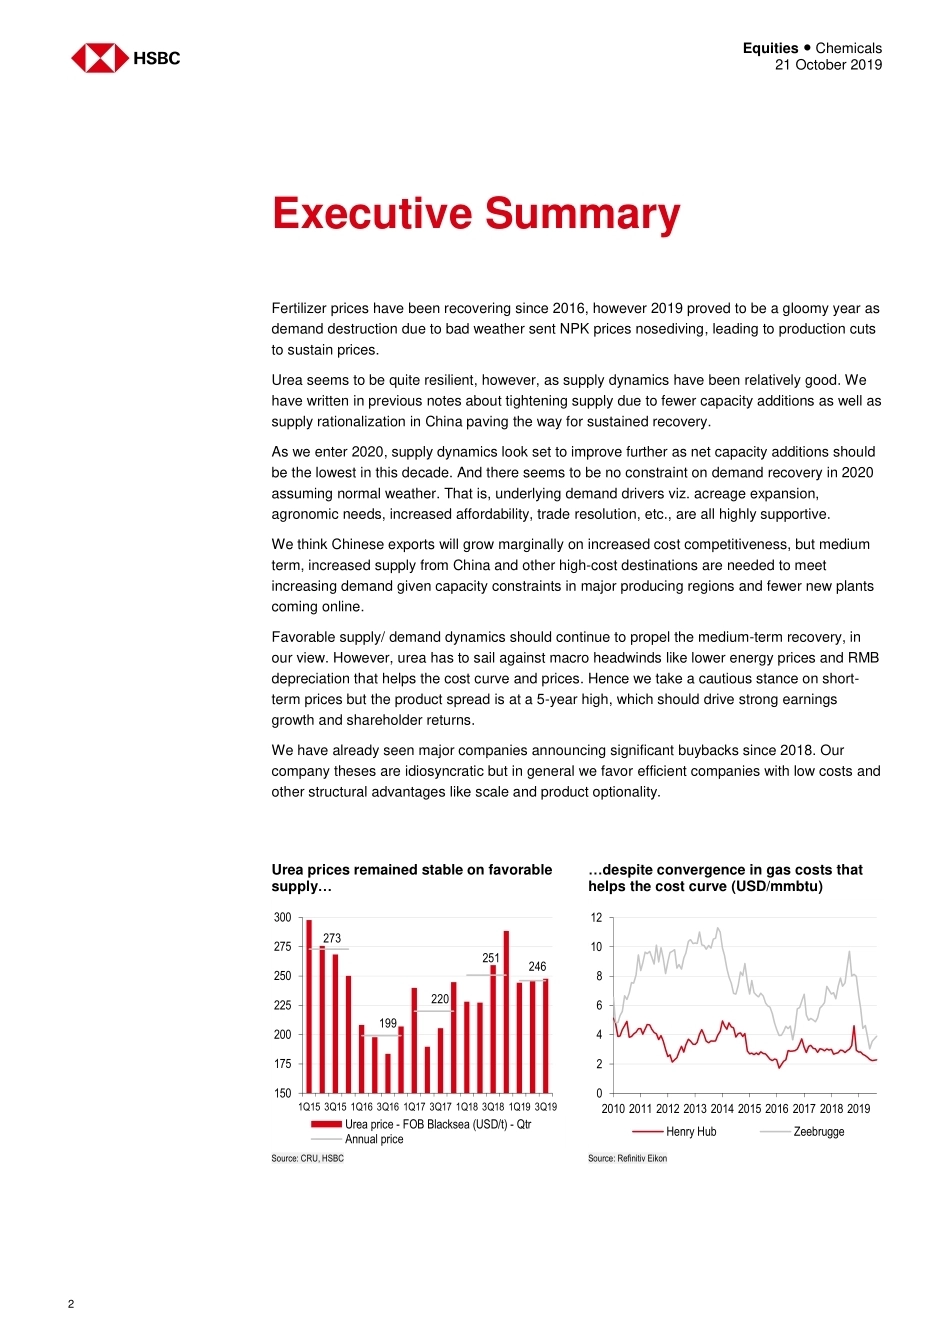
Disclosures & Disclaimer This report must be read with the disclosures and the analyst certifications in the Disclosure appendix, and with the Disclaimer, which forms part of it. Issuer of report: HSBC Securities (USA) Inc View HSBC Global Research at: https://www.research.hsbc.com THIS CONTENT MAY NOT BE DISTRIBUTED TO MAINLAND CHINA Urea stands out as the most defensive segment amid weakening fertilizer prices We turn cautious on short-term urea price but spread at multiyear high benefits earnings We prefer Buy-rated OCI (TP EUR26.60), CF (TP to USD55 from USD52), China Blue (TP HKD2.54) in the space We leverage our research presence in China, Middle East, US and India to develop a global view on urea supply and demand dynamics Although weak demand in 2019 has seen NPK prices nosediving, urea has remained largely stable due to tightening supply despite falling energy costs. In our view, urea balance could tighten further in 2020 with net capacity additions expected to be the lowest in this decade and as demand rebounds on agronomic needs. We take a cautious view on short-term urea prices, however, as macro headwinds like lower energy prices and FX have trimmed the cost curve by USD15-20/t; we cut our price forecasts by 5-7% (pg 3). Nevertheless urea spread is close to a 5yr high (pg 2) and any further decline in energy costs should support profitability in our view. Growing production in China (pg 10) presents a short-term risk but not enough to derail broader recovery in our view (see Sowing the Seeds of Growth 27 Jan 2019). Supply constraint could sustain urea recovery: Although global utilization is at c77%, many low-cost, export-oriented destinations are operating at close to full utilization (pg 2), hence a major part of supply has to come from high-cost regions that hold the current price floor. In 2020, seasonal and trade constraints should warrant a sharp rise in utilization rates (+3-6%) in regions closer to end markets and North American producers will likely have to switch away from other nitrogen products, thereby eventually improving spreads for the nitrogen chain. Our preferred picks, all rated Buy: We like OCI (TP EUR26.60) due to its deleveraging story and potential to crystallize value from accretive investments; CF Industries (TP to USD55 from USD52) given its scale, cost advantage and strong cash generation; China Blue (TP HKD2.54) due to improving product spread that should lead to margin expansion and its preferential access to natural gas that should lead to a spread premium vs China industry average. Key stock summary Current ______ TP ________ __ Rating ___ Upside/ Market cap PE EV/EBITDA Company Ticker Currency price Old New Old New downside (USDm) 2019e 2019e CF Industry CF.N USD 48.94 52.00 55.00 Buy Buy 26.7% 28,035 18.0x 7.8x Nutrien NTR.TO USD 47.77 65.00 62.00 Buy Buy 15.1% 10,429 21.7x 9.1x OCI NV OCI.AS EUR 21.21 26.60 26.60 Buy Buy 25.4% 4,978 NA 10.3x SAFCO 2020.SE SAR 80.60 78.00 77.60 Hold Hold -3.7% 8,954 24.5x 18.1x China BlueChemical 3983.HK HKD 1.99 2.54 2.54 Buy Buy 28.9% 1,188 12.3x 7.0x Source: HSBCe, Refinitiv Eikon. Priced as of close at 18 Oct 2019 21 October 2019 Alexandre Falcao Global Ag/EV Materials & LatAm Industrials Analyst HSBC Securities (USA) Inc. alexandre.p.falcao@us.hsbc.com +1 212 525 4449 Santhosh Seshadri*, CFA Analyst HSBC Securities and Capital Markets (India) Private Limited santhosh.seshadri@hsbc.co.in +91 80 4555 2758 Eric Shen* (S1700519030001) Head of A-share Petrochem & New Materials Research HSBC Qianhai Securities Limited eric.shen@hsbcqh.com.cn +86 10 5795 2343 Nicholas Paton*, CFA Senior Analyst HSBC Bank Middle East Ltd nicholas.paton@hsbc.com +971 4 423 6923 Sriharsha Pappu* Global Head of Chemicals Research HSBC Bank plc sriharsha.pappu@hsbc.com +44 20 7991 9243 Prateek Bhatnagar*, CFA Analyst HSBC Securities and Capital Markets (India) Private Limited prateekbhatnagar@hsbc.co.in +91 80 4555 2757 Augusto Ensiki LatAm Industrials, Agri, Healthcare and Education HSBC Securities (USA) Inc. augusto.a.ensiki@us.hsbc.com +1 212 525 4915 * Employed by a non-US affiliate of HSBC Securities (USA) Inc, and is not registered/ qualified pursuant to FINRA regulations Global Agribusiness Equities Chemicals Global Fertilizers: Finding the bright spot Equities ● Chemicals 21 October 2019 2 Executive Summary Fertilizer prices have been recovering since 2016, however 2019 proved to be a gloomy year as demand destruction due to bad weather sent NPK prices nosediving, leading to production cuts to sustain prices. Urea seems to be quite resilient, however, as supply dynamics have been relatively good. We have written in previous notes about tightening supply due to fewer capacity additions as well as supply rationalization in China paving the way for sustained recovery. As we enter 2020, supply dynamics look set to improve further as net capacity additions should be the lowest in this decade. And there seems to be no constraint on demand recov...




发表评论取消回复