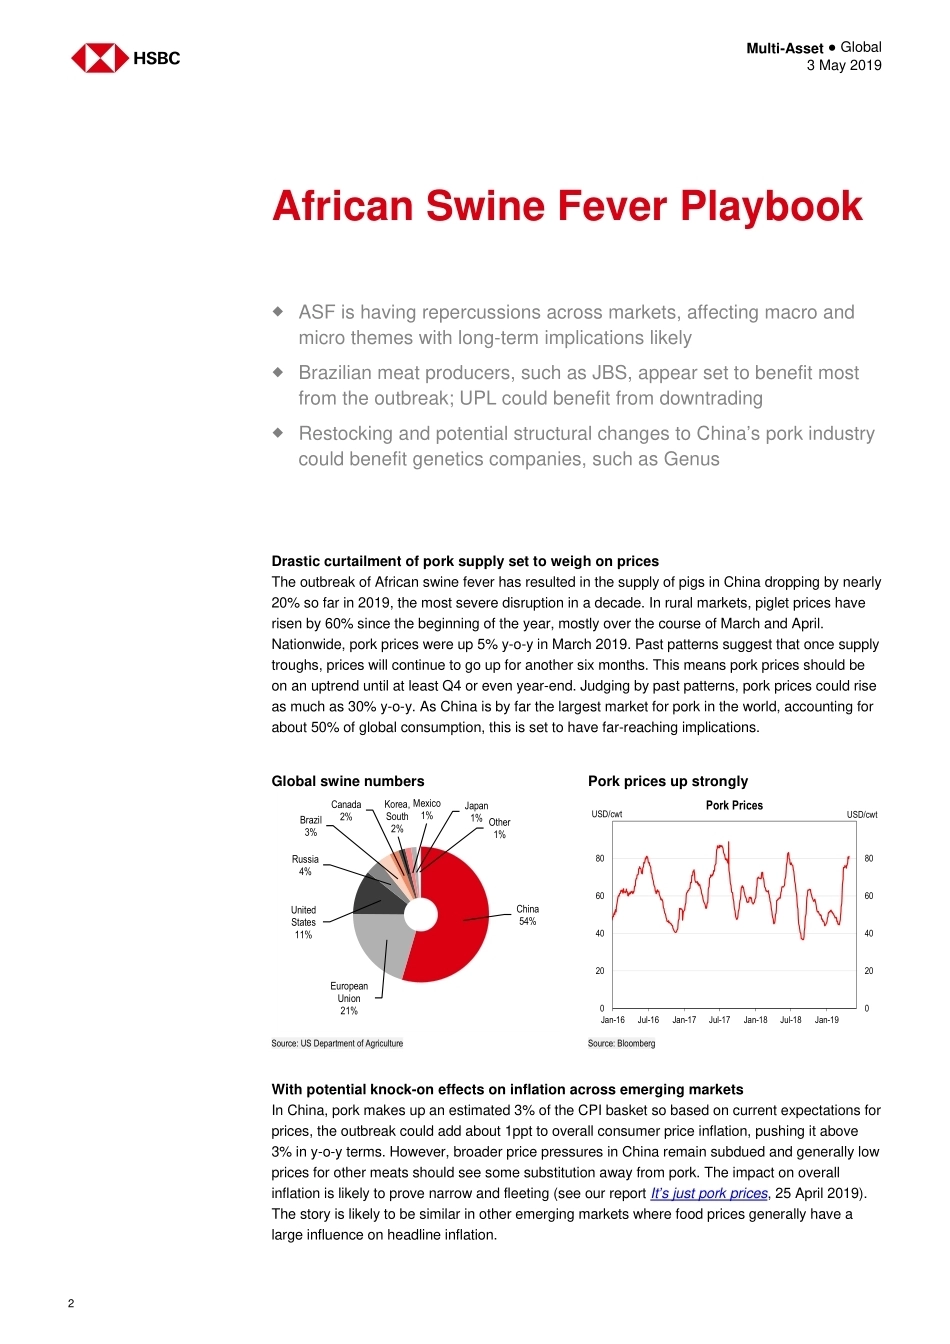
Disclosures & Disclaimer This report must be read with the disclosures and the analyst certifications in the Disclosure appendix, and with the Disclaimer, which forms part of it. Issuer of report: HSBC Securities (USA) Inc View HSBC Global Research at: https://www.research.hsbc.com ASF continues to grow in intensity and magnitude, sending shockwaves across assets and the ag value chains The HSBC global team has collaborated to analyze the potential impact on inflation, trade and sectors worldwide Protein and genetic companies likely to benefit while lower grain demand set to drag down value chain (agchem, seeds) Emerging markets, specifically China, appear more exposed than developed markets to African swine fever: The supply disruption due to swine fever has pushed up rural piglet prices by 60% in China so far in 2019. It is hard to determine how long the outbreak of ASF will take to be contained, but its scale and past experience points to a 3-5 year effect. In China, pork makes up about 3% of the CPI basket; thus, ASF could add about 1ppt to overall CPI. The story is likely to be similar in other EMs where food generally have a large influence on headline inflation. For DMs, food typically comprises a smaller share of consumer expenditures, which should limit the inflation impact. ASF is complicating the ongoing US-China negotiations and may affect the composition of US-China trade: The sharp decline in its pig population and the resultant lower demand for soybeans could constrain China’s ability to substantially increase soybean imports from the US, a key requirement of the US negotiators. Instead, China may agree to reduce or remove its additional duties on US pork if the ASF crisis leads to a sustained pork shortage. The sharp decline in Chinese pork production will likely lower corn and soybean demand as they constitute a major portion of animal feed. In a nutshell, if the reduction in Chinese pork output is c30%, we estimate global demand for soybeans and corn would fall by 1.8-4.2% and 1.5-3.4%, respectively, which would likely dragging down most of the grain value chain, including chemicals and fertilizers. Exposed stocks: We believe Brazilian meat producers JBS and Marfrig are likely to benefit most from the effects of ASF while Genus, Cranswick and UPL should also benefit. But we see negative impacts for Adecoagro as its exposure to grains in LatAm could curb any short-term earnings momentum. Lower crop prices are also likely to be a net negative for fertilizer names CF, MOS and NTR; OCI looks less affected. This is a reissue of our note published on 1 May 2019; this version contains a correction to the authorship of the protein industry section. Please disregard the version previously distributed. 3 May 2019 Alexandre Falcao Global Ag/EV Materials & LatAm Industrials Analyst HSBC Securities (USA) Inc. alexandre.p.falcao@us.hsbc.com +1 212 525 4449 Santhosh Seshadri*, CFA Analyst HSBC Securities and Capital Markets (India) Private Limited santhosh.seshadri@hsbc.co.in +91 80 4555 2758 Alessia Maria Apostolatos Analyst, Global Beverages and LatAm Food HSBC Securities (USA) Inc. alessia.m.apostolatos@us.hsbc.com +1 212 525 7457 Saurabh Jain* Analyst HSBC Securities and Capital Markets (India) Private Limited saurabh2jain@hsbc.co.in +91 22 6164 0691 Anand Date*, CFA HSBC UK MidCap Equity Analyst HSBC Bank plc anand.date@hsbc.com +44 20 3359 6003 Sriharsha Pappu* Global Head of Chemicals Research HSBC Bank plc sriharsha.pappu@hsbc.com +44 20 7991 9243 Augusto Ensiki LatAm Industrials, Agri, Healthcare and Education HSBC Securities (USA) Inc. augusto.a.ensiki@us.hsbc.com +1 212 525 4915 Ronny Berger, CFA Analyst, LatAm Airlines, Healthcare, Education HSBC Securities (USA) Inc. ronny.berger@us.hsbc.com +1 212 525 6707 * Employed by a non-US affiliate of HSBC Securities (USA) Inc, and is not registered/ qualified pursuant to FINRA regulations Global Agribusiness Multi-Asset Global Key changes to ratings and estimates Sector Company Ticker Rating Currency Latest price Target Price Implied Upside/Downside Market cap (USDm) Analyst Ag and Food Adecoagro AGRO US Buy USD 6.80 14.50 113.2% 793 Alexandre Falcao Ag and Food Cranswick CWK LN Hold GBp 2,882 2,680 -7.0% 1,924 Doriana Russo Ag and Food JBS JBSS3 BZ Buy BRL 19.35 25.00 29.2% 13,420 Alessia Maria Apostolatos Ag and Food Marfrig MRFG3 BZ Buy BRL 7.20 8.00 11.1% 1,137 Alessia Maria Apostolatos Biotech Genus GNS LN Buy GBp 2,396 2,700 12.7% 2,014 Anand Date Chemicals CF Industries CF US Buy USD 44.92 60.00 33.6% 9,990 Alexandre Falcao Chemicals Mosaic MOS US Buy USD 26.13 38.00 45.4% 10,081 Alexandre Falcao Chemicals Nutrien NTR US Buy USD 53.65 65.00 21.2% 32,392 Alexandre Falcao Chemicals OCI NV OCI NA Buy EUR 25.09 29.50 17.6% 5,903 Nicholas Paton Chemicals UPL Ltd UPI IN Buy INR 970.35 1,050.00 8.2% 7,080 Saurabh Jain Note: Latest Prices as of close on 29 April 2019. Source: Refinitv Eikon HSBC estimates African Swine Fever Playbook Multi-Asse...




发表评论取消回复