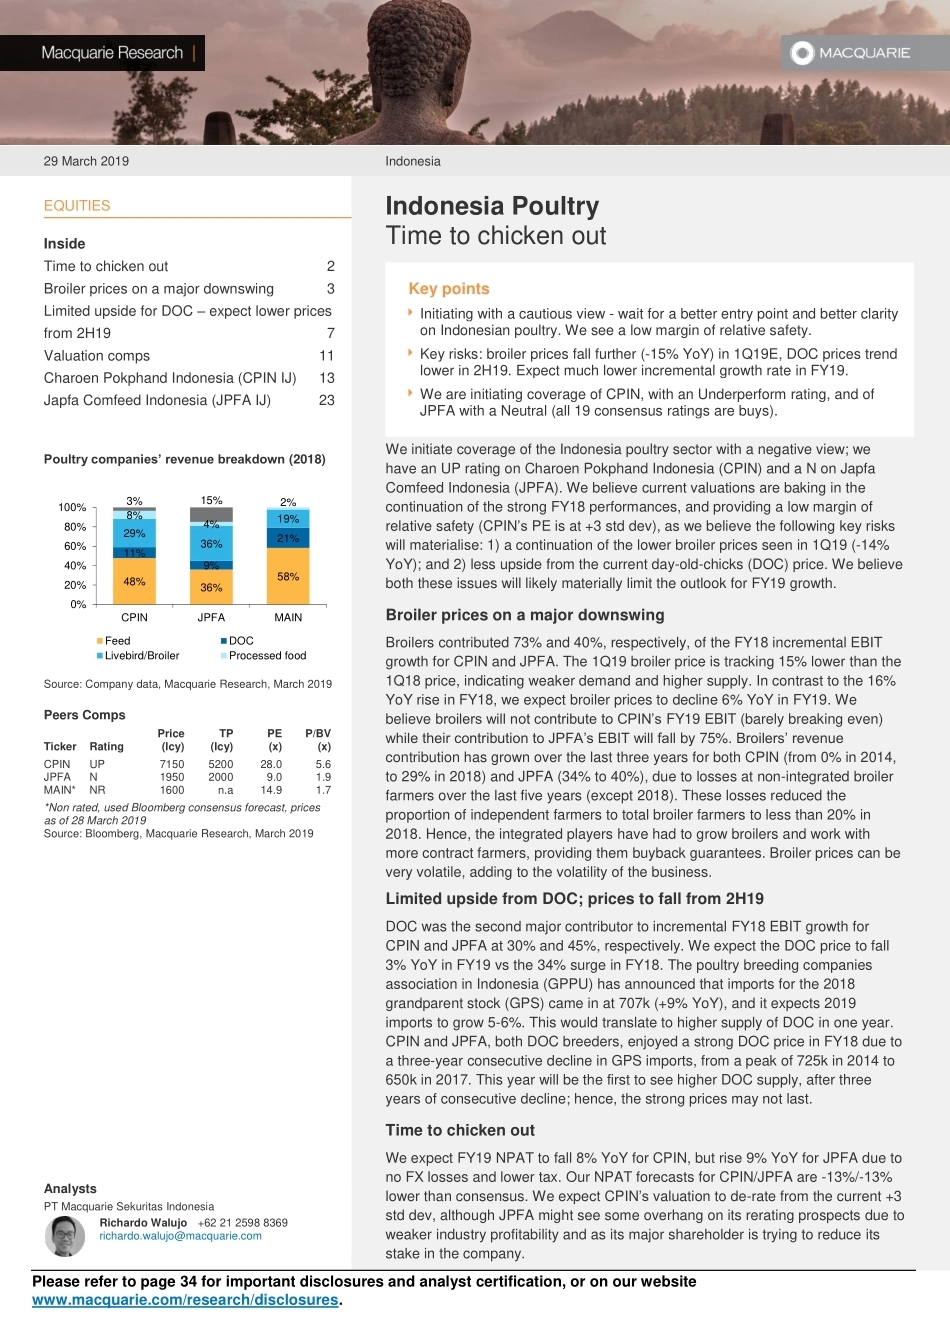
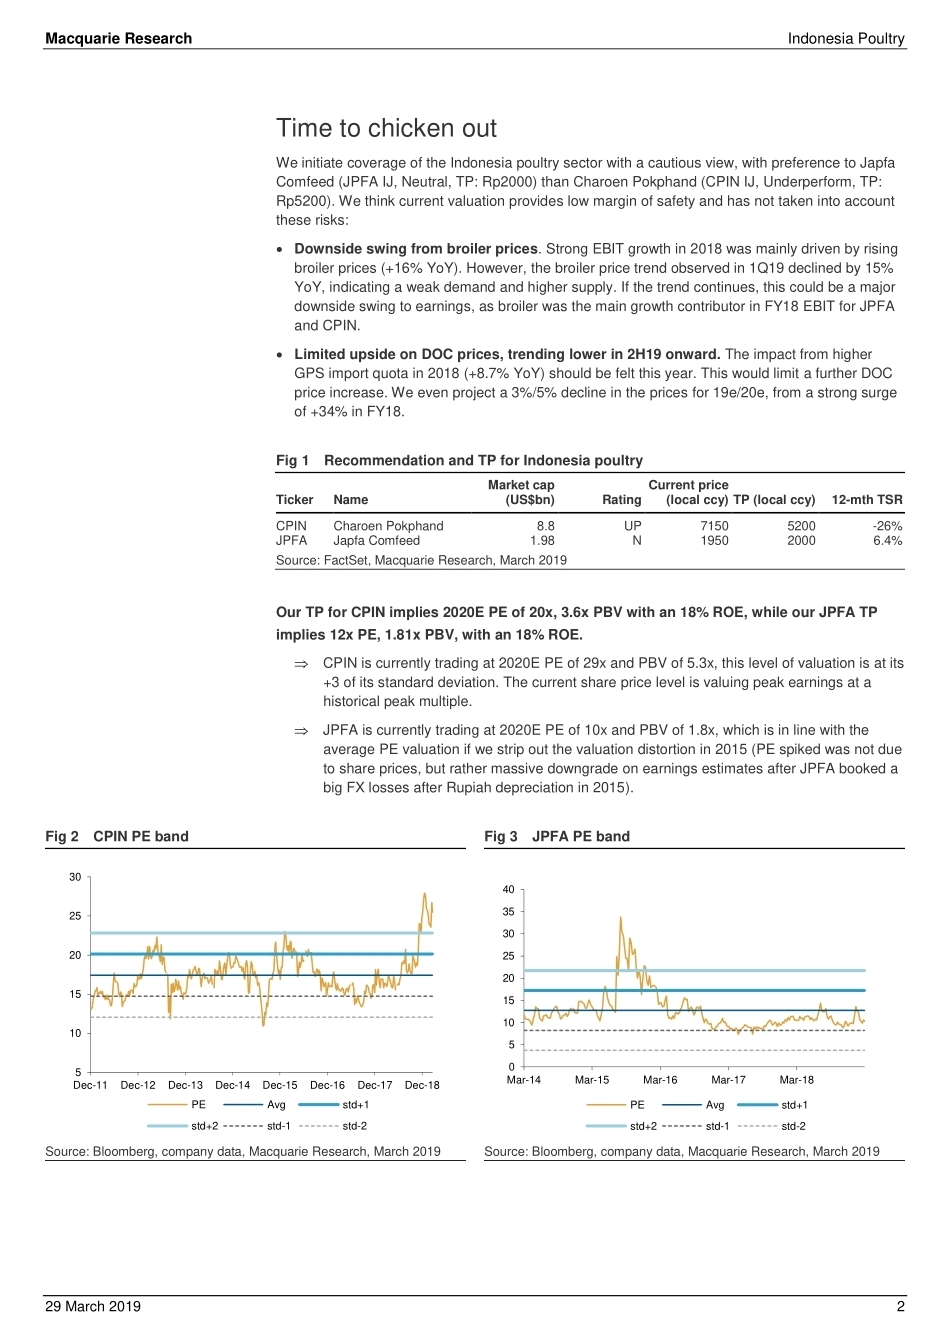
Please refer to page 34 for important disclosures and analyst certification, or on our website www.macquarie.com/research/disclosures. 29 March 2019 Indonesia EQUITIES Inside Time to chicken out 2 Broiler prices on a major downswing 3 Limited upside for DOC – expect lower prices from 2H19 7 Valuation comps 11 Charoen Pokphand Indonesia (CPIN IJ) 13 Japfa Comfeed Indonesia (JPFA IJ) 23 Poultry companies’ revenue breakdown (2018) Source: Company data, Macquarie Research, March 2019 Peers Comps Ticker Rating Price (lcy) TP (lcy) PE (x) P/BV (x) CPIN UP 7150 5200 28.0 5.6 JPFA N 1950 2000 9.0 1.9 MAIN* NR 1600 n.a14.9 1.7 *Non rated, used Bloomberg consensus forecast, prices as of 28 March 2019Source: Bloomberg, Macquarie Research, March 2019Analysts PT Macquarie Sekuritas IndonesiaRichardo Walujo +62 21 2598 8369richardo.walujo@macquarie.com Indonesia Poultry Time to chicken out Key points Initiating with a cautious view - wait for a better entry point and better clarity on Indonesian poultry. We see a low margin of relative safety. Key risks: broiler prices fall further (-15% YoY) in 1Q19E, DOC prices trend lower in 2H19. Expect much lower incremental growth rate in FY19. We are initiating coverage of CPIN, with an Underperform rating, and of JPFA with a Neutral (all 19 consensus ratings are buys). We initiate coverage of the Indonesia poultry sector with a negative view; we have an UP rating on Charoen Pokphand Indonesia (CPIN) and a N on Japfa Comfeed Indonesia (JPFA). We believe current valuations are baking in the continuation of the strong FY18 performances, and providing a low margin of relative safety (CPIN’s PE is at +3 std dev), as we believe the following key risks will materialise: 1) a continuation of the lower broiler prices seen in 1Q19 (-14% YoY); and 2) less upside from the current day-old-chicks (DOC) price. We believe both these issues will likely materially limit the outlook for FY19 growth. Broiler prices on a major downswing Broilers contributed 73% and 40%, respectively, of the FY18 incremental EBIT growth for CPIN and JPFA. The 1Q19 broiler price is tracking 15% lower than the 1Q18 price, indicating weaker demand and higher supply. In contrast to the 16% YoY rise in FY18, we expect broiler prices to decline 6% YoY in FY19. We believe broilers will not contribute to CPIN’s FY19 EBIT (barely breaking even) while their contribution to JPFA’s EBIT will fall by 75%. Broilers’ revenue contribution has grown over the last three years for both CPIN (from 0% in 2014, to 29% in 2018) and JPFA (34% to 40%), due to losses at non-integrated broiler farmers over the last five years (except 2018). These losses reduced the proportion of independent farmers to total broiler farmers to less than 20% in 2018. Hence, the integrated players have had to grow broilers and work with more contract farmers, providing them buyback guarantees. Broiler prices can be very volatile, adding to the volatility of the business. Limited upside from DOC; prices to fall from 2H19 DOC was the second major contributor to incremental FY18 EBIT growth for CPIN and JPFA at 30% and 45%, respectively. We expect the DOC price to fall 3% YoY in FY19 vs the 34% surge in FY18. The poultry breeding companies association in Indonesia (GPPU) has announced that imports for the 2018 grandparent stock (GPS) came in at 707k (+9% YoY), and it expects 2019 imports to grow 5-6%. This would translate to higher supply of DOC in one year. CPIN and JPFA, both DOC breeders, enjoyed a strong DOC price in FY18 due to a three-year consecutive decline in GPS imports, from a peak of 725k in 2014 to 650k in 2017. This year will be the first to see higher DOC supply, after three years of consecutive decline; hence, the strong prices may not last. Time to chicken out We expect FY19 NPAT to fall 8% YoY for CPIN, but rise 9% YoY for JPFA due to no FX losses and lower tax. Our NPAT forecasts for CPIN/JPFA are -13%/-13% lower than consensus. We expect CPIN’s valuation to de-rate from the current +3 std dev, although JPFA might see some overhang on its rerating prospects due to weaker industry profitability and as its major shareholder is trying to reduce its stake in the company. 48%36%58%11%9%21%29%36%19%8%4%2%3%15%0%20%40%60%80%100%CPINJPFAMAINFeedDOCLivebird/BroilerProcessed foodMacquarie Research Indonesia Poultry 29 March 2019 2 Time to chicken out We initiate coverage of the Indonesia poultry sector with a cautious view, with preference to Japfa Comfeed (JPFA IJ, Neutral, TP: Rp2000) than Charoen Pokphand (CPIN IJ, Underperform, TP: Rp5200). We think current valuation provides low margin of safety and has not taken into account these risks: Downside swing from broiler prices. Strong EBIT growth in 2018 was mainly driven by rising broiler prices (+16% YoY). However, the broiler price trend observed in 1Q19 declined by 15% YoY, indicating a weak demand and higher supply. If the trend continues, this could be a major downside swing to earnings, as br...




发表评论取消回复