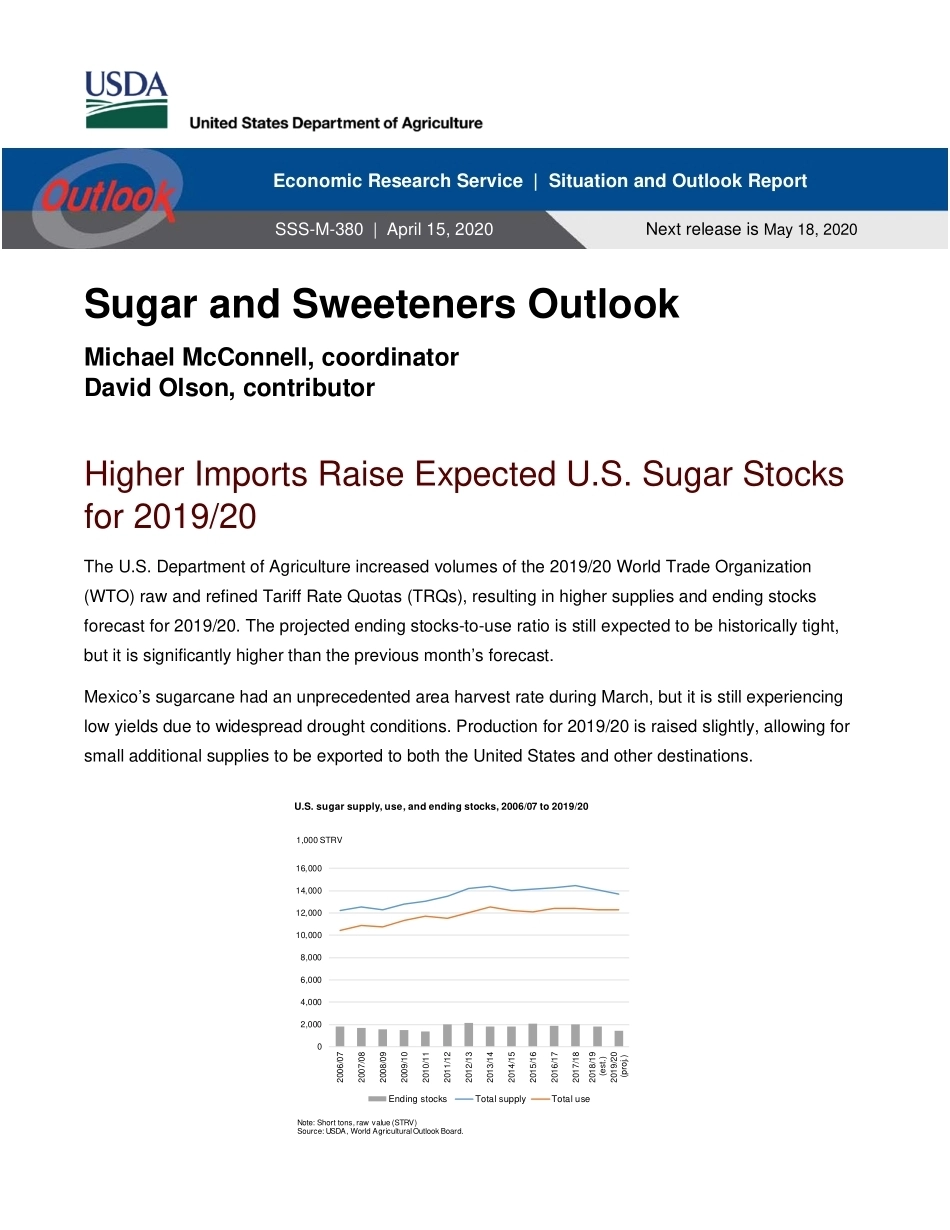
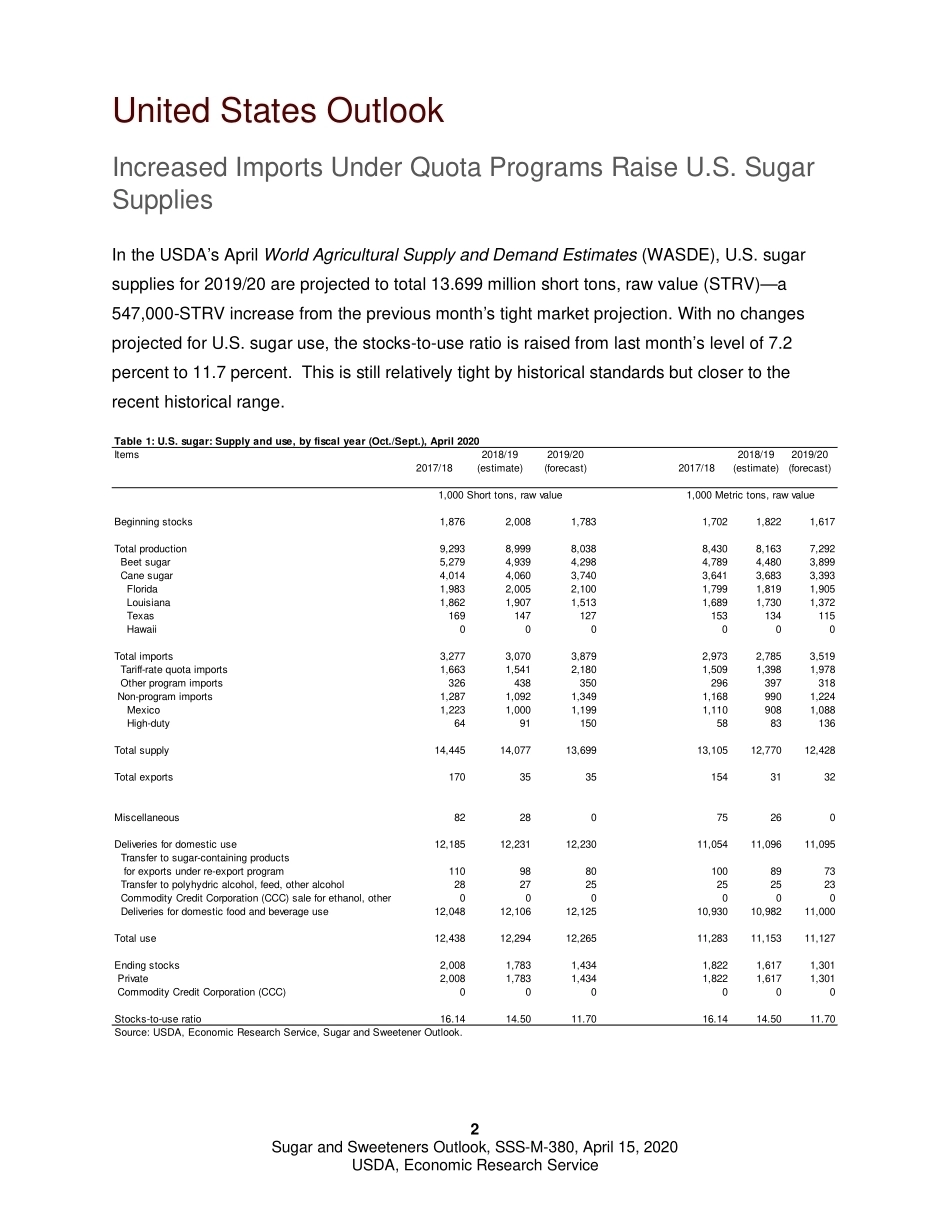
Approved by USDA’s World Agricultural Outlook Board Sugar and Sweeteners Outlook Michael McConnell, coordinator David Olson, contributor Higher Imports Raise Expected U.S. Sugar Stocks for 2019/20 The U.S. Department of Agriculture increased volumes of the 2019/20 World Trade Organization (WTO) raw and refined Tariff Rate Quotas (TRQs), resulting in higher supplies and ending stocks forecast for 2019/20. The projected ending stocks-to-use ratio is still expected to be historically tight, but it is significantly higher than the previous month’s forecast. Mexico’s sugarcane had an unprecedented area harvest rate during March, but it is still experiencing low yields due to widespread drought conditions. Production for 2019/20 is raised slightly, allowing for small additional supplies to be exported to both the United States and other destinations. 02,0004,0006,0008,00010,00012,00014,00016,0002006/072007/082008/092009/102010/112011/122012/132013/142014/152015/162016/172017/182018/19 (est.)2019/20 (proj.)1,000 STRVU.S. sugar supply, use, and ending stocks, 2006/07 to 2019/20Ending stocksTotal supplyTotal useNote: Short tons, raw value (STRV)Source: USDA, World Agricultural Outlook Board.Economic Research Service | Situation and Outlook Report Next release is May 18, 2020 SSS-M-380 | April 15, 20202 Sugar and Sweeteners Outlook, SSS-M-380, April 15, 2020 USDA, Economic Research Service United States Outlook Increased Imports Under Quota Programs Raise U.S. Sugar Supplies In the USDA’s April World Agricultural Supply and Demand Estimates (WASDE), U.S. sugar supplies for 2019/20 are projected to total 13.699 million short tons, raw value (STRV)—a 547,000-STRV increase from the previous month’s tight market projection. With no changes projected for U.S. sugar use, the stocks-to-use ratio is raised from last month’s level of 7.2 percent to 11.7 percent. This is still relatively tight by historical standards but closer to the recent historical range. Table 1: U.S. sugar: Supply and use, by fiscal year (Oct./Sept.), April 2020Items2019/202019/20(forecast)(forecast)Beginning stocks 1,8762,0081,7831,7021,8221,617Total production 9,2938,9998,0388,4308,1637,292 Beet sugar5,2794,9394,2984,7894,4803,899 Cane sugar4,0144,0603,7403,6413,6833,393 Florida1,9832,0052,1001,7991,8191,905 Louisiana1,8621,9071,5131,6891,7301,372 Texas169147127153134115 Hawaii000000Total imports3,2773,0703,8792,9732,7853,519 Tariff-rate quota imports 1,6631,5412,1801,5091,3981,978 Other program imports326438350296397318 Non-program imports1,2871,0921,3491,1689901,224 Mexico 1,2231,0001,1991,1109081,088 High-duty64911505883136Total supply14,44514,07713,69913,10512,77012,428Total exports 17035351543132Miscellaneous8228075260Deliveries for domestic use12,18512,23112,23011,05411,09611,095 Transfer to sugar-containing products for exports under re-export program11098801008973 Transfer to polyhydric alcohol, feed, other alcohol282725252523 Commodity Credit Corporation (CCC) sale for ethanol, other000000 Deliveries for domestic food and beverage use 12,04812,10612,12510,93010,98211,000Total use12,43812,29412,26511,28311,15311,127Ending stocks 2,0081,7831,4341,8221,6171,301 Private2,0081,7831,4341,8221,6171,301 Commodity Credit Corporation (CCC)000000Stocks-to-use ratio16.1414.5011.7016.1414.5011.70Source: USDA, Economic Research Service, Sugar and Sweetener Outlook.2018/19 (estimate)2017/181,000 Short tons, raw value1,000 Metric tons, raw value2017/182018/19 (estimate)nQsOmOuMuM8OaO9PtRrRtRqQjMqQtPiNnMsMbRmNoQuOoOsRxNnMmNThe increase in supply is primarily the result of policy actions taken by the Secretary of the U.S. Department of Agriculture (USDA) and the Office of the U.S. Trade Representative (USTR). On April 1, the USDA increased the 2019/20 WTO raw sugar TRQ by 350,000 STRV and the refined sugar TRQ by 200,000 STRV. On April 8, USTR allocated these increases, including the country allocations for the raw sugar TRQ. It allocated part of the refined TRQ to Canada (nearly 6,000 STRV) and the rest to the Global, first-come-first serve nations (194,000 STRV). It also included a schedule of tranches for entry of the Global allocation, starting on April 13, 2020, with 105,000 STRV of the additional allocation, with successively smaller tranches becoming available every 2 weeks until June 29, 2020. These action were taken to bring additional supplies to the U.S. sugar market in 2019/20, as domestic production for 2019/20 is projected to be significantly lower due to poor weather conditions—particularly during harvest for many sugarbeet-producing regions—and to fewer imports from Mexico due to drought conditions in many of its sugarcane-producing regions. Imports under quota programs are projected to be 2.180 million STRV in 2019/20, a 540,000-STRV increase. The shortfall of the raw sugar TRQ is projected to be 84,000 STRV, a 44,000- STRV increase from the March forecast. The increased shortfall represents some quantities of the additional TRQ allocations as ...




发表评论取消回复