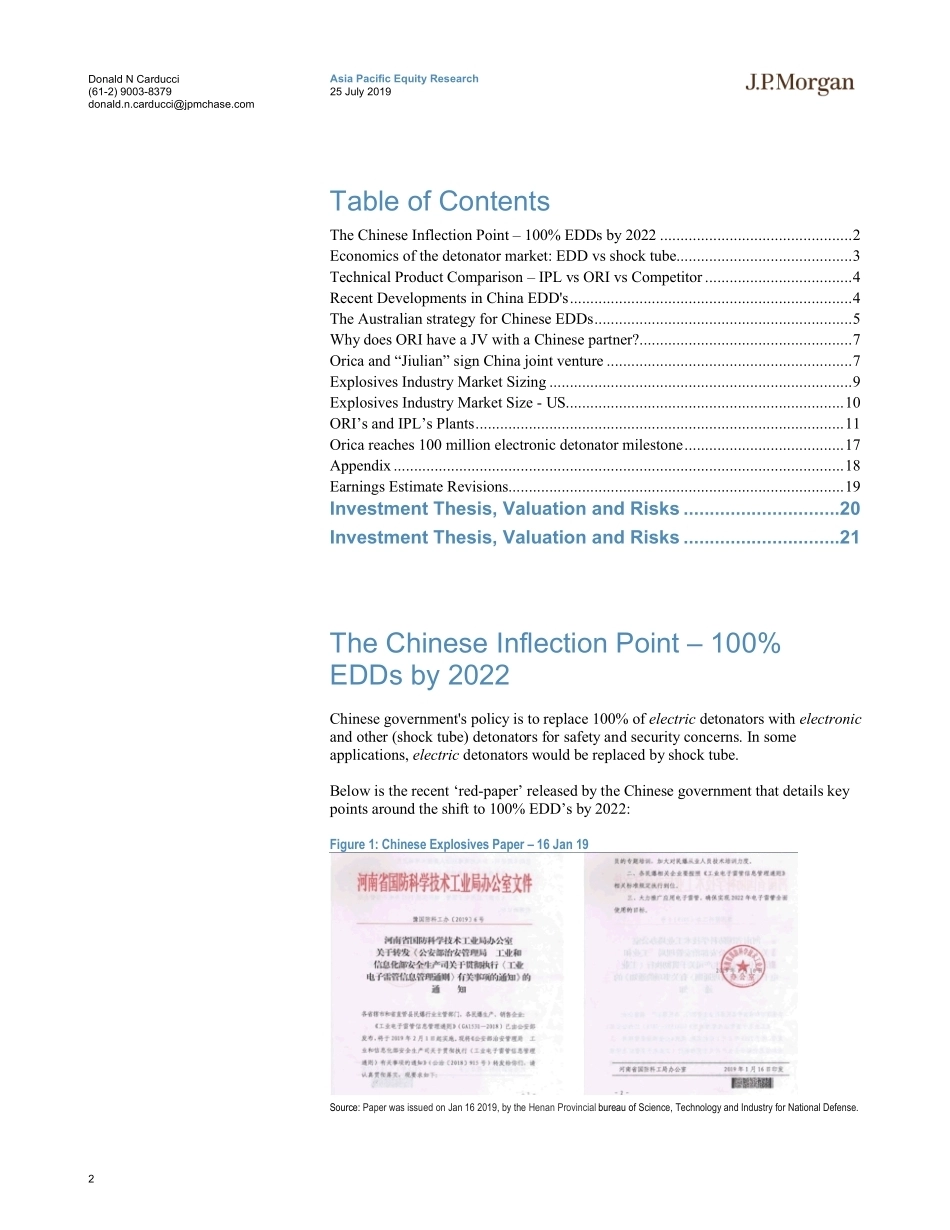
www.jpmorganmarkets.comAsia Pacific Equity Research25 July 2019Australian Chemicals SectorORI.AX, ORI AUUnderweightPrice: A$20.59 (25-Jul)Price Target: A$16.20 (Jun-20)Detonating Change - a Risk to OricaIPL.AX, IPL AUOverweightPrice: A$3.49 (25-Jul)Price Target: A$3.75 (Dec-19)AustraliaAgriculture/FertilizersDonald N Carducci AC(61-2) 9003-8379donald.n.carducci@jpmchase.comBloomberg JPMA CARDUCCI Abhinay Jeggannagari(61-2) 9003 6734abhinay.jeggannagari@jpmorgan.comJ.P. Morgan Securities Australia LimitedEquity Ratings and Price TargetsMkt CapRatingPrice TargetCompanyTicker(A$ mn)Price (A$)CurPrevCurEnd DatePrevEnd DateOrica LimitedORI AU7,808.0320.59UWn/c16.20Jun-2016.50n/cIncitec Pivot LtdIPL AU5,797.203.49OWn/c3.75Dec-19n/cn/cSource: Company data, Bloomberg, J.P. Morgan estimates. n/c = no change. All prices as of 25 Jul 19.See page 27 for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.A significant threat is looming on the horizon for ORI: Chinese regulation requires 100% Electronic Delay Detonator (EDD) use by 2022. On our estimates, the downside could be as much as A$51m (PBT). Key takeaways: 1) China's policy to replace electric detonators with safer EDD alternatives provides a catalyst for commercial innovation and lower production costs; 2) As the EDD cost curve falls with manufacturing innovation, the Chinese value proposition will no doubt threaten current market share; 3) The impact on ORI's earnings could reach A$51m per annum as a result of Chinese competition and we downgrade ORI estimates from FY22 onward, ranging between 1-5%. Retain UW, PT of A$16.20 (was A$16.50). Chinese regulation is providing the catalyst for innovation of EDD’s which will decrease production costs and disrupt the global shock tube market of existing manufacturers. Admittedly, the timeline for Chinese domestic conversion by 2022 is optimistic, and industry feedback suggests slow global adoption of Chinese EDD’s, and references poor reliability, transportation costs, and competitive pricing for superior Western products. While these assertions may have substance in the short term, we believe Chinese manufacturers have already begun the process to address these issues, partially via joint ventures. There are four possible paths for 'Western’ EDD manufacturers if/when high-quality, competitively priced Chinese product becomes more widely adopted: 1) lower prices by 40-60% to match Chinese prices & reduce earnings,2) maintain high prices and promote differentiation but take market share losses on decreased volumes, 3) joint ventures w/Chinese partners to sell into the Western market, or 4) acquire an existing company with Chinese-manufactured product developed by Western expertise. China accounts for 60% of global holes-blasted per year (~2.2bn) and has the capacity to manufacture 130% of global detonator demand. Chinese policy aims to remove electric detonators in favor of EDDs. The cost differential between non-electronic and electronic blasting is significant. Surface blasting a 20 meter shock tube costs $9-$11 per hole, whereas the same application with an EDD costs $28-$35. For context, of the ~1.3bn holes blasted in China, ~650m are via electric detonators and only 20-30m are electronic. For the ~900m holes blasted outside of China, only ~30m are conducted using electronics (as opposed to shock tube or electrics). In this deep dive, we review key factors affecting the EDD market while looking simplistically at nuanced (but key) terms, definitions, and costs.China’s policy is to replace 100% of electric detonators with electronic and non-electric (shock tube) detonators due to safety and security concerns.Chinese innovation is being driven by government regulation, and the conversion of 650m holes currently blasted with electric detonators will no doubt provide the impetus and fundingrequired.As a result of additional costs associated with EDD servicing, theseunits may never be the lowest cost option relative to shock tube.2Asia Pacific Equity Research25 July 2019Donald N Carducci(61-2) 9003-8379donald.n.carducci@jpmchase.comTable of ContentsThe Chinese Inflection Point – 100% EDDs by 2022 ...............................................2Economics of the detonator market: EDD vs shock tube...........................................3Technical Product Comparison – IPL vs ORI vs Competitor ....................................4Recent Developments in China EDD's.....................................................................4The Australian strategy for Chinese EDDs...............................................................5Why does ORI have a JV with...




发表评论取消回复