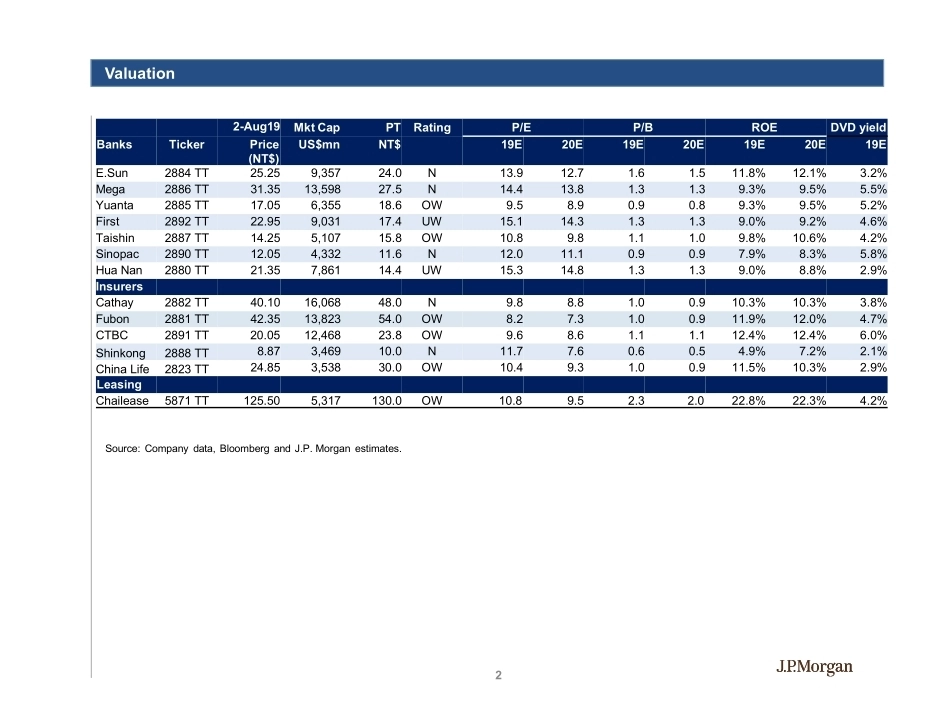
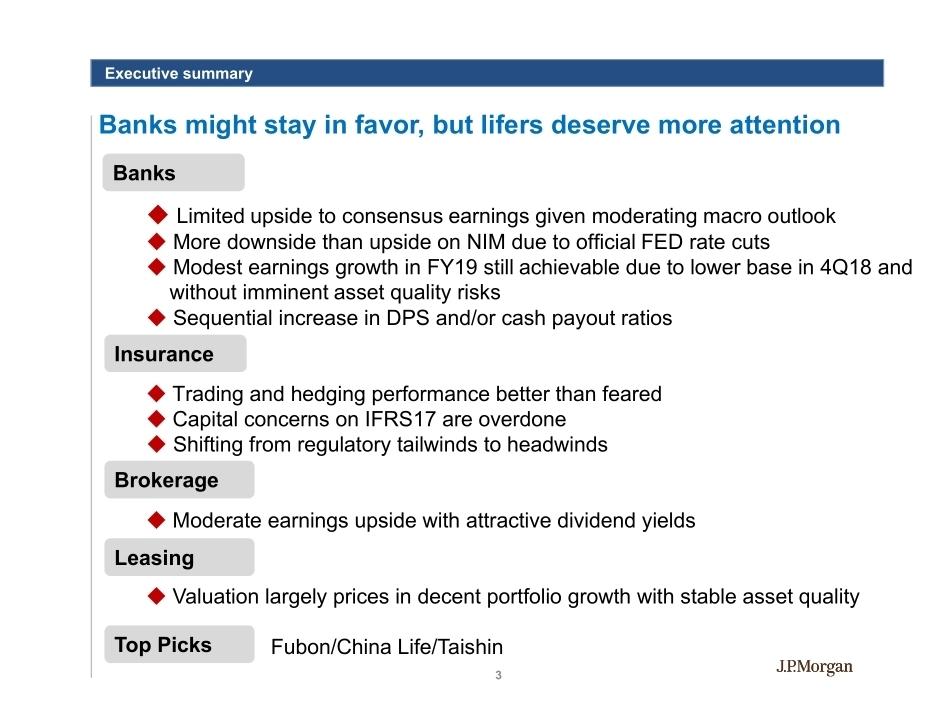
See the end pages of this presentation for analyst certification and important disclosures, including non-US analyst disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. Asia Pacific Equity ResearchAug 2019Taiwan FinancialsJemmy HuangACJ.P. Morgan Securities (Taiwan) LimitedTelephone: (886) 2-2725-9870Email: jemmy.s.huang@jpmorgan.comLeo WengJ.P. Morgan Securities (Asia Pacific) LimitedTelephone: (852) 2800-8511Email: leo.weng@jpmorgan.comKatherine LeiJ.P. Morgan Securities (Asia Pacific) LimitedTelephone: (852) 2800-8552Email: katherine.lei@jpmorgan.com2Source: Company data, Bloomberg and J.P. Morgan estimates. Valuation2-Aug19Mkt CapPTRatingP/EP/BROEDVD yieldBanksTickerPrice (NT$)US$mnNT$19E20E19E20E19E20E19EE.Sun2884 TT25.25 9,357 24.0 N13.9 12.7 1.6 1.5 11.8%12.1%3.2%Mega2886 TT31.35 13,598 27.5 N14.4 13.8 1.3 1.3 9.3%9.5%5.5%Yuanta2885 TT17.05 6,355 18.6 OW9.5 8.9 0.9 0.8 9.3%9.5%5.2%First2892 TT22.95 9,031 17.4 UW15.1 14.3 1.3 1.3 9.0%9.2%4.6%Taishin2887 TT14.25 5,107 15.8 OW10.8 9.8 1.1 1.0 9.8%10.6%4.2%Sinopac2890 TT12.05 4,332 11.6 N12.0 11.1 0.9 0.9 7.9%8.3%5.8%Hua Nan2880 TT21.35 7,861 14.4 UW15.3 14.8 1.3 1.3 9.0%8.8%2.9%InsurersCathay2882 TT40.10 16,068 48.0 N9.8 8.8 1.0 0.9 10.3%10.3%3.8%Fubon2881 TT42.35 13,823 54.0 OW8.2 7.3 1.0 0.9 11.9%12.0%4.7%CTBC2891 TT20.05 12,468 23.8 OW9.6 8.6 1.1 1.1 12.4%12.4%6.0%Shinkong2888 TT8.87 3,469 10.0 N11.7 7.6 0.6 0.5 4.9%7.2%2.1%China Life2823 TT24.85 3,538 30.0 OW10.4 9.3 1.0 0.9 11.5%10.3%2.9%LeasingChailease5871 TT125.50 5,317 130.0OW10.8 9.5 2.3 2.0 22.8%22.3%4.2%3Banks might stay in favor, but lifers deserve more attention◆ Limited upside to consensus earnings given moderating macro outlook ◆ More downside than upside on NIM due to official FED rate cuts◆ Modest earnings growth in FY19 still achievable due to lower base in 4Q18 and without imminent asset quality risks◆ Sequential increase in DPS and/or cash payout ratios◆ Trading and hedging performance better than feared◆ Capital concerns on IFRS17 are overdone◆ Shifting from regulatory tailwinds to headwinds◆ Moderate earnings upside with attractive dividend yields◆ Valuation largely prices in decent portfolio growth with stable asset qualityFubon/China Life/TaishinExecutive summaryBanks Insurance Top Picks BrokerageLeasing4Executive summaryTaiwan Banks: dividend plays to outperform on moderate earningsTaishin (2887 TT, PT: NT$15.8)◆ Improving PPOP growth driven by WM fees and corporate banking revenue◆ Declining credit costs from the high base in 4Q18◆ Sufficient capital position unless for inorganic growth◆ Current valuation of 1.1x P/B is undemanding given 10-11% ROE outlook and compared to an average of 1.2x at peersYuanta (2885 TT, PT: NT$18.6)◆ Successful merger of Ta Chong Bank, over 50% group earnings from banking operations in FY19E◆ Stable securities operations with diversification on revenue & geography◆ Current valuation of 0.9x P/B is undemanding given 9-10% ROE outlookTop Picks 5PPOP – Improving loan growth in line with expectationSystem loan growth in TaiwanSource: TEJ, National Statistics of Taiwan, Bloomberg and J.P. Morgan.Corporate loan growth vs Nominal GDPCorporate loan growth in Mar 19 by industrySource: National Statistics, Bloomberg, and J.P. Morgan.Source: National Statistics of Taiwan and J.P. Morgan.•Sector loan growth of 5.2% as of May 2019 was identical to 5.2% as of 4Q18 and slightly ahead of our expectation of 4-5% for FY19.•Corporate loan growth has been driven by financial, utilities, and real estate sectors, which should be driven by the recovery of macro-economic conditions •Mortgage growth has decreased to 4.5% in 1Q1remains largely stable YTD supported by slightly improving property prices and transaction volume but is unlikely to be a meaningful driver for loan growth in the near future•With better than expected GDP growth outlook (JPMe revised up to 2.2% for FY19E), we expect current momentum to stay, with upside hinged on the progress of infrastructure construction and production relocation by corporates6PPOP – FCY/offshore lending remains the focusLoan growth YoY by region Source: As of Mar 19- Central Bank in Taiwan, FSC, and J.P. Morgan.FX, SME and total corporate loans, YoYLDR – FX vs NTDSource: Central Bank in Taiwan, TEJ and J.P. Morgan.Source: Central Bank in Taiwan, TEJ and J.P. Morgan.•Growth momentum of FCY loans remains steady at 7.2% as of 1Q19, better than 6.7% as of 4Q18; the key driver is overseas branches, while momentum at OBU has recovered from the low base dragged by tightening AML rules and concerns on China asset quality •Growth at SME lending has been stable but lower risk appetites at banks in reflection of increasing macro uncertainties suggest limited upsi...




发表评论取消回复