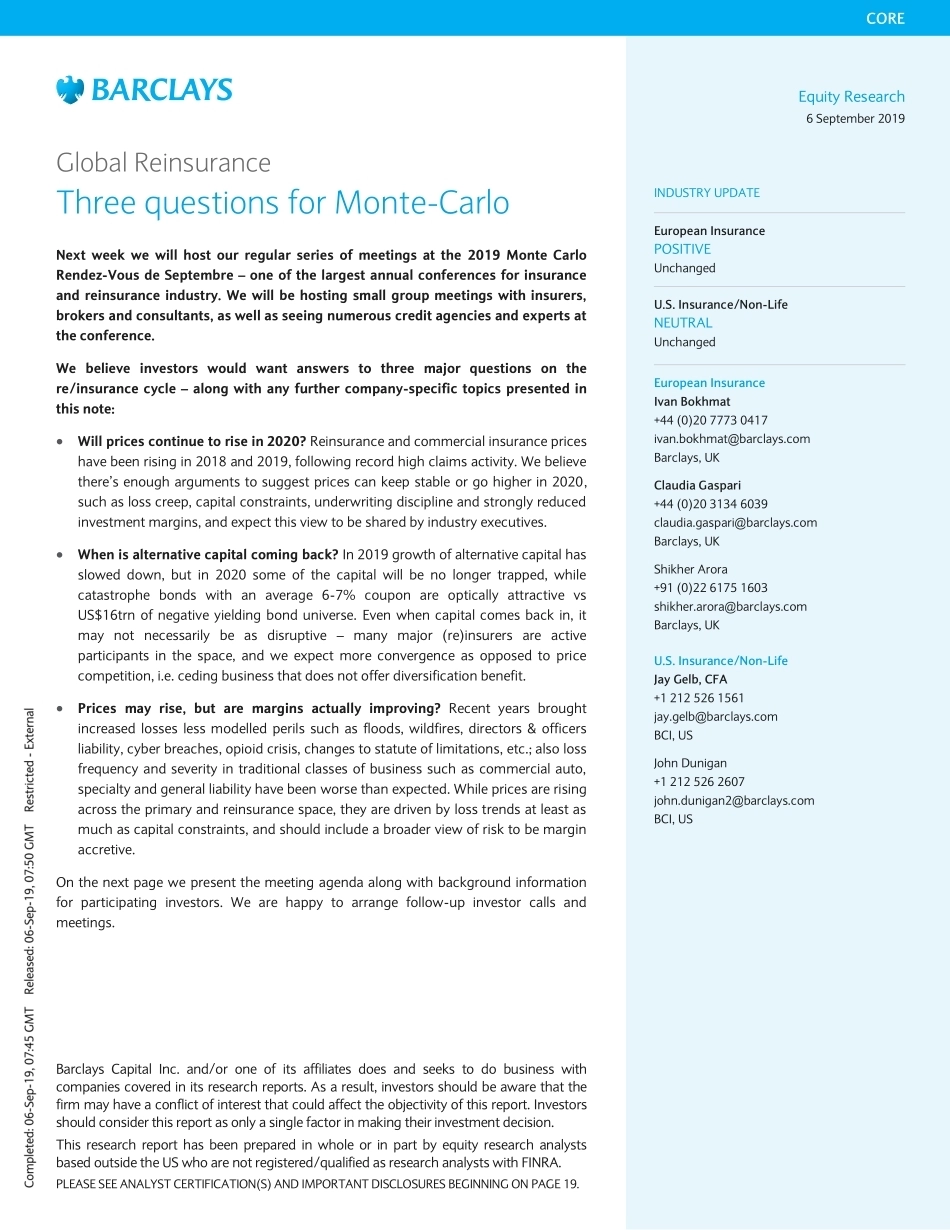
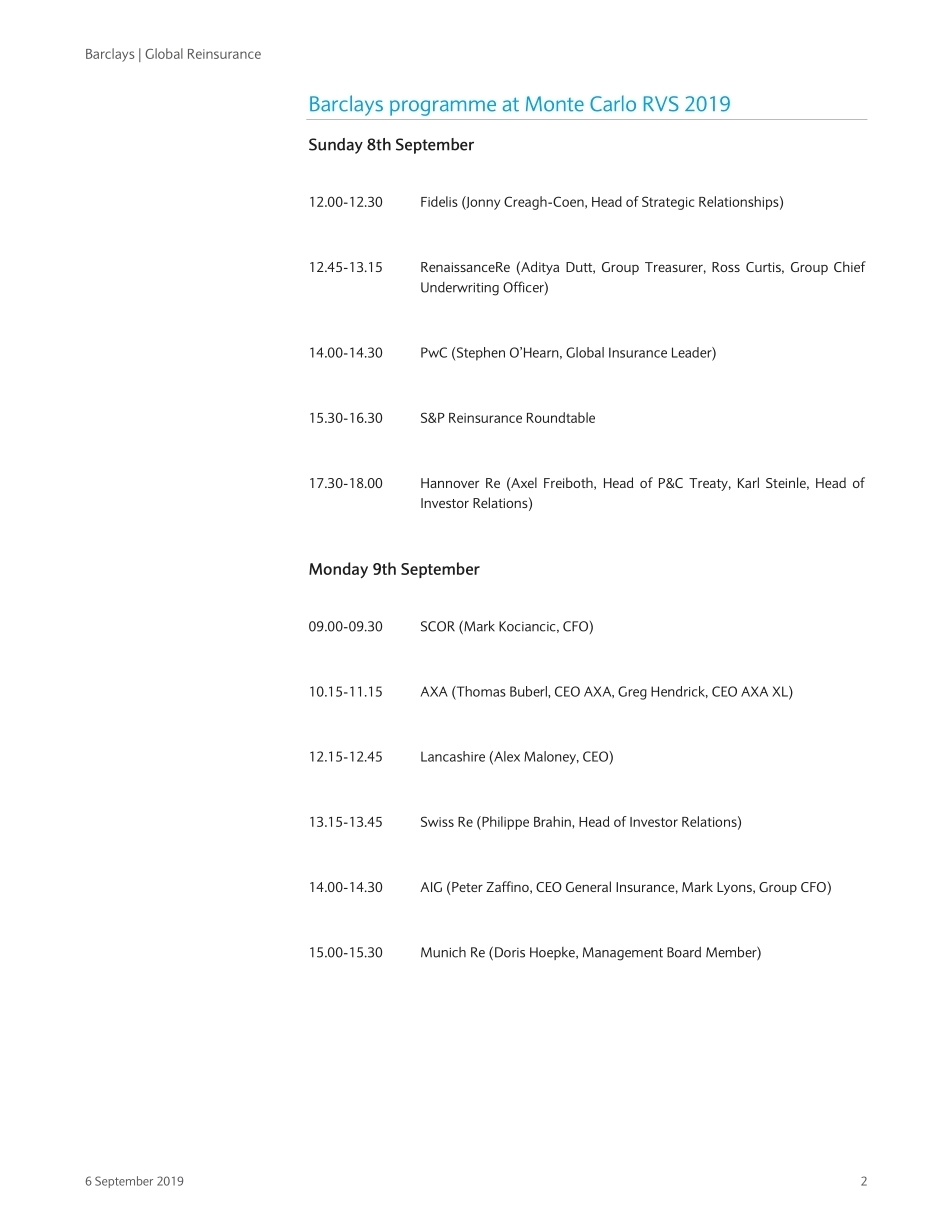
Equity Research 6 September 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. This research report has been prepared in whole or in part by equity research analysts based outside the US who are not registered/qualified as research analysts with FINRA. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 19. Restricted - Internal Global Reinsurance Three questions for Monte-Carlo Next week we will host our regular series of meetings at the 2019 Monte Carlo Rendez-Vous de Septembre – one of the largest annual conferences for insurance and reinsurance industry. We will be hosting small group meetings with insurers, brokers and consultants, as well as seeing numerous credit agencies and experts at the conference. We believe investors would want answers to three major questions on the re/insurance cycle – along with any further company-specific topics presented in this note: Will prices continue to rise in 2020? Reinsurance and commercial insurance prices have been rising in 2018 and 2019, following record high claims activity. We believe there’s enough arguments to suggest prices can keep stable or go higher in 2020, such as loss creep, capital constraints, underwriting discipline and strongly reduced investment margins, and expect this view to be shared by industry executives. When is alternative capital coming back? In 2019 growth of alternative capital has slowed down, but in 2020 some of the capital will be no longer trapped, while catastrophe bonds with an average 6-7% coupon are optically attractive vs US$16trn of negative yielding bond universe. Even when capital comes back in, it may not necessarily be as disruptive – many major (re)insurers are active participants in the space, and we expect more convergence as opposed to price competition, i.e. ceding business that does not offer diversification benefit. Prices may rise, but are margins actually improving? Recent years brought increased losses less modelled perils such as floods, wildfires, directors & officers liability, cyber breaches, opioid crisis, changes to statute of limitations, etc.; also loss frequency and severity in traditional classes of business such as commercial auto, specialty and general liability have been worse than expected. While prices are rising across the primary and reinsurance space, they are driven by loss trends at least as much as capital constraints, and should include a broader view of risk to be margin accretive. On the next page we present the meeting agenda along with background information for participating investors. We are happy to arrange follow-up investor calls and meetings. INDUSTRY UPDATE European Insurance POSITIVE Unchanged U.S. Insurance/Non-Life NEUTRAL Unchanged European Insurance Ivan Bokhmat +44 (0)20 7773 0417 ivan.bokhmat@barclays.com Barclays, UK Claudia Gaspari +44 (0)20 3134 6039 claudia.gaspari@barclays.com Barclays, UK Shikher Arora +91 (0)22 6175 1603 shikher.arora@barclays.com Barclays, UK U.S. Insurance/Non-Life Jay Gelb, CFA +1 212 526 1561 jay.gelb@barclays.com BCI, US John Dunigan +1 212 526 2607 john.dunigan2@barclays.com BCI, US Barclays | Global Reinsurance 6 September 2019 2 Barclays programme at Monte Carlo RVS 2019 Sunday 8th September 12.00-12.30 Fidelis (Jonny Creagh-Coen, Head of Strategic Relationships) 12.45-13.15 RenaissanceRe (Aditya Dutt, Group Treasurer, Ross Curtis, Group Chief Underwriting Officer) 14.00-14.30 PwC (Stephen O’Hearn, Global Insurance Leader) 15.30-16.30 S&P Reinsurance Roundtable 17.30-18.00 Hannover Re (Axel Freiboth, Head of P&C Treaty, Karl Steinle, Head of Investor Relations) Monday 9th September 09.00-09.30 SCOR (Mark Kociancic, CFO) 10.15-11.15 AXA (Thomas Buberl, CEO AXA, Greg Hendrick, CEO AXA XL) 12.15-12.45 Lancashire (Alex Maloney, CEO) 13.15-13.45 Swiss Re (Philippe Brahin, Head of Investor Relations) 14.00-14.30 AIG (Peter Zaffino, CEO General Insurance, Mark Lyons, Group CFO) 15.00-15.30 Munich Re (Doris Hoepke, Management Board Member) Barclays | Global Reinsurance 6 September 2019 3 COMPANY SNAPSHOTSBarclays | Global Reinsurance 6 September 2019 4 AIG: Positioned for Further Improvement (Rating: Overweight; Industry view: Neutral) FIGURE 1 AIG: Operating earnings per share FIGURE 2 AIG: Business Mix $4.58$2.15$0.37$2.40$1.17$5.56$5.40201420152016201720182019E2020E General Insurance -Int'l34%General Insurance -North America33%Individual Retirement12%Group Retirement6%Life Insurance9%Institutional Markets4%Other Operations2%Total Revenues FY18: $47bn Source: Company data, Barclays Research estimates Source: Company data, Barclays Research estimates FIGURE 3 AIG: Book Value and Operating ROE (ex ...




发表评论取消回复