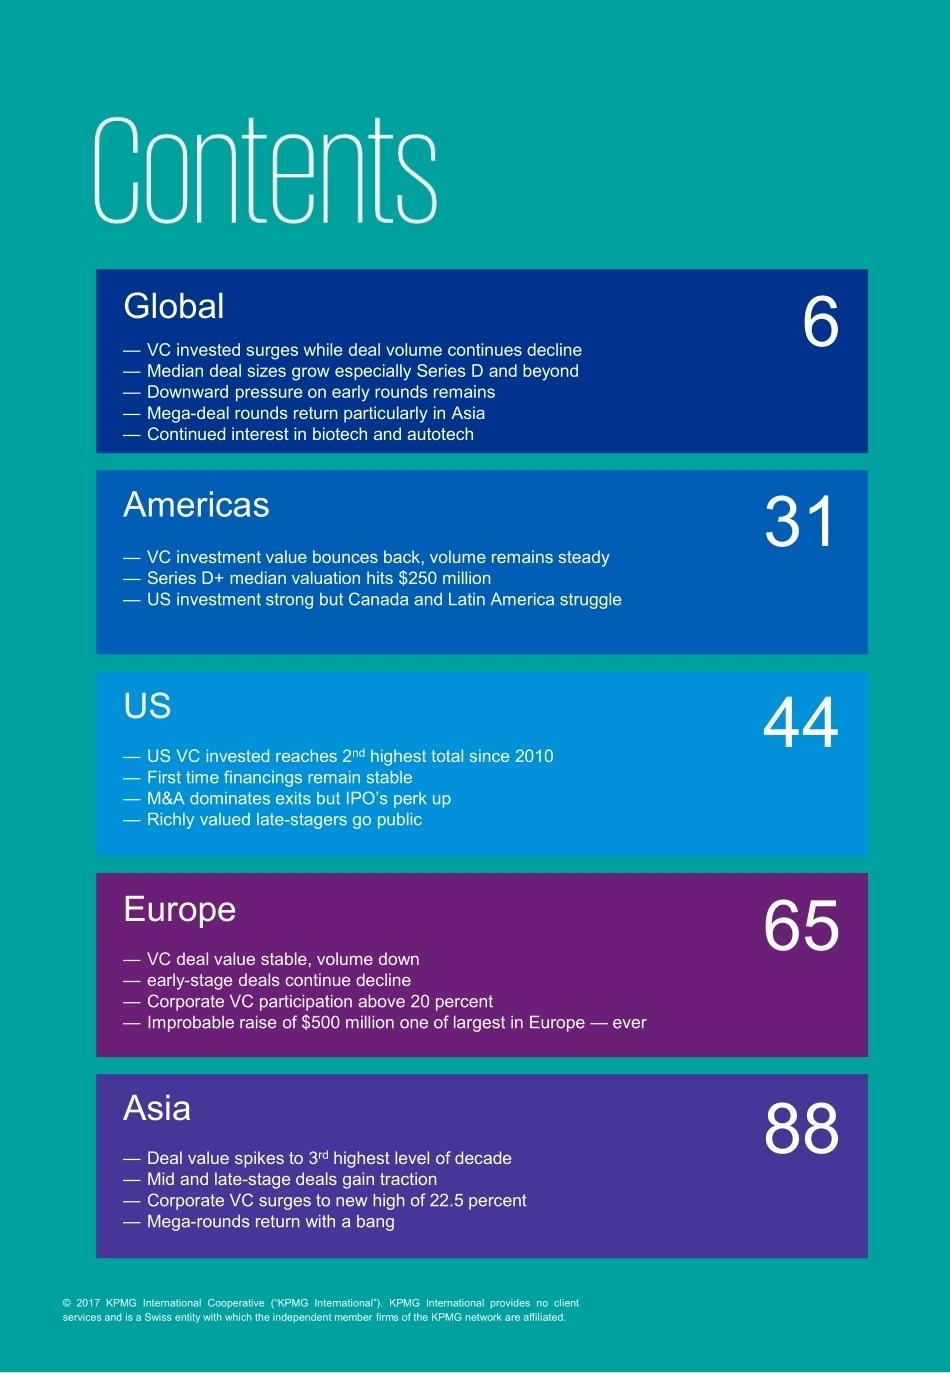
1#Q2VC© 2017 KPMG International Cooperative (“KPMG International”). KPMG International provides no clientservices and is a Swiss entity with which the independent member firms of the KPMG network are affiliated.Global analysis ofventure funding13 July 20172#Q2VC© 2017 KPMG International Cooperative (“KPMG International”). KPMG International provides no clientservices and is a Swiss entity with which the independent member firms of the KPMG network are affiliated.Welcome to the Q2’17 edition of the KPMG Enterprise Venture Pulse Report. In this quarter’s report, we highlight the key trends, opportunities and challenges facing the venture capital (VC) market globally and in key regions around the world.Despite an ongoing decline in the number of VC deals globally, there was a major uptick in VC investment during Q2’17. A significant number of mega-deals in all regions helped drive this funding increase, including China-based Didi Chuxing’s record-shattering $5.5 billion funding round. Given the return of global mega-deals, it comes as no surprise that this quarter saw the birth of 16 new unicorn companies — the highest level experienced since Q2’15. US Initial Public Offering (IPO) activity continued to make a turnaround during the quarter, with a number of technology companies achieving successful exits. In tandem with solid merger and acquisition (M&A) activity, this renewal is a positive sign for the market.Q2 saw biotech and autotech attracting continued interest from investors, these are expected to be hot areas of VC investment in Q3, in addition to artificial intelligence (AI), analytics, and virtual reality technologies. Blockchain is also expected to remain on the radar of investors, with a growing focus on the technology’s applicability across sectors and verticals.In this edition of the Venture Pulse Report, we look at these and other global and regional trends, including:— The pickup in mega-deals activity across the globe— The ongoing decline in number of deals, specifically at the seed and early-stage deal levels— The drivers behind advancements in autotech— The growing focus on business to business (B2B) opportunities.We hope you find this edition of the Venture Pulse Report insightful. If you would like to discuss any of the results in more detail, please contact a KPMG adviser in your area.© 2017 KPMG International Cooperative (“KPMG International”). KPMG International provides no clientservices and is a Swiss entity with which the independent member firms of the KPMG network are affiliated.Jonathan LavenderGlobal Chairman, KPMG Enterprise, KPMG InternationalBrian HughesCo-Leader,KPMG Enterprise Innovative Startups Network, KPMG International, and Partner, KPMG in the USArik SpeierCo-Leader,KPMG Enterprise Innovative Startups Network, KPMG International, and Partner,KPMG in IsraelYou know KPMG, you might not know KPMG Enterprise. KPMG Enterprise advisers in member firms around the world are dedicated to working with businesses like yours. Whether you’re an entrepreneur looking to get started, an innovative, fast growing company, or an established company looking to an exit, KPMG Enterprise advisers understand what is important to you and can help you navigate your challenges — no matter the size or stage of your business. You gain access to KPMG’s global resources through a single point of contact — a trusted adviser to your company. It’s a local touch with a global reach. © 2017 KPMG International Cooperative (“KPMG International”). KPMG International provides no clientservices and is a Swiss entity with which the independent member firms of the KPMG network are affiliated.6Global Americas 3144US65Europe88Asia— VC invested surges while deal volume continues decline— Median deal sizes grow especially Series D and beyond— Downward pressure on early rounds remains— Mega-deal rounds return particularly in Asia— Continued interest in biotech and autotech— VC investment value bounces back, volume remains steady— Series D+ median valuation hits $250 million— US investment strong but Canada and Latin America struggle— US VC invested reaches 2nd highest total since 2010— First time financings remain stable— M&A dominates exits but IPO’s perk up— Richly valued late-stagers go public— VC deal value stable, volume down— early-stage deals continue decline— Corporate VC participation above 20 percent— Improbable raise of $500 million one of largest in Europe — ever— Deal value spikes to 3rd highest level of decade— Mid and late-stage deals gain traction— Corporate VC surges to new high of 22.5 percent— Mega-rounds return with a bang4#Q2VC© 2017 KPMG International Cooperative (“KPMG International”). KPMG International provides no clientservices and is a Swiss entity with which the independent member firms of the KPMG network are affiliated.Completed transaction volume continues a gentle slide as VC invested comes roaring backWorldwide VC deal count slid again by just over 7% between Q1 and Q2'17. However, t...




发表评论取消回复