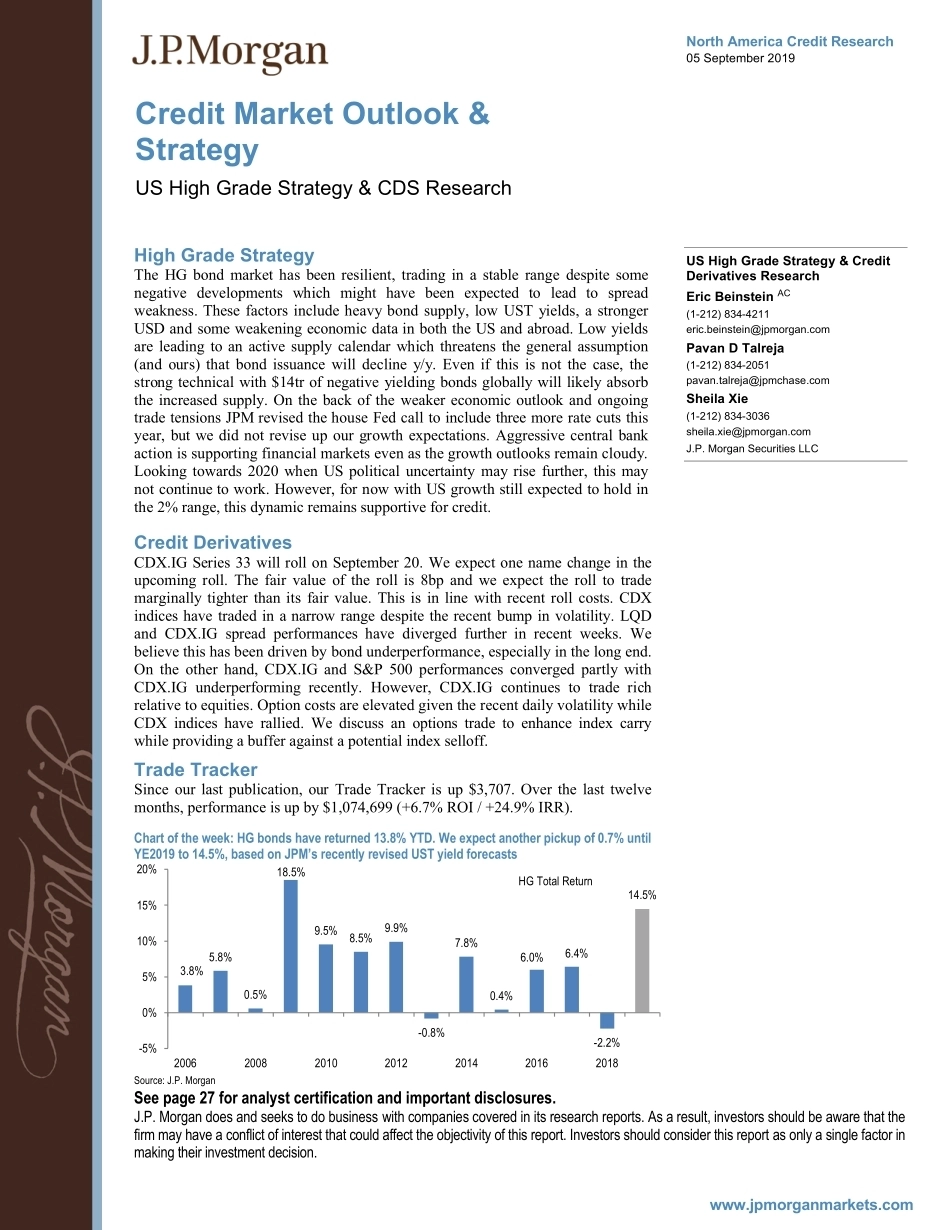
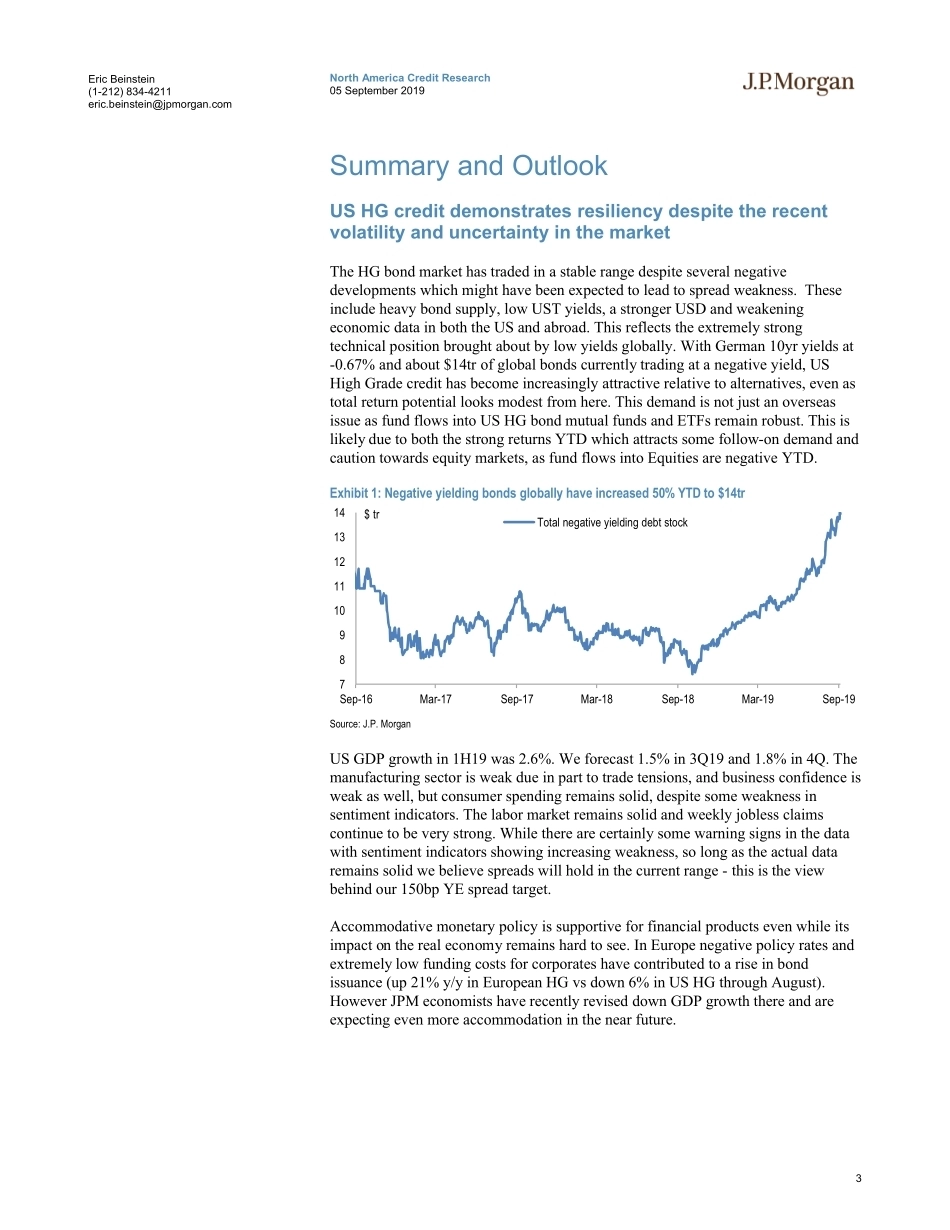
North America Credit Research05 September 2019 Credit Market Outlook & StrategyUS High Grade Strategy & CDS ResearchUS High Grade Strategy & Credit Derivatives ResearchEric Beinstein AC(1-212) 834-4211eric.beinstein@jpmorgan.comPavan D Talreja(1-212) 834-2051pavan.talreja@jpmchase.comSheila Xie(1-212) 834-3036sheila.xie@jpmorgan.comJ.P. Morgan Securities LLCSee page 27 for analyst certification and important disclosures.J.P. Morgan does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision.www.jpmorganmarkets.comHigh Grade StrategyThe HG bond market has been resilient, trading in a stable range despite some negative developments which might have been expected to lead to spread weakness. These factors include heavy bond supply, low UST yields, a stronger USD and some weakening economic data in both the US and abroad. Low yields are leading to an active supply calendar which threatens the general assumption (and ours) that bond issuance will decline y/y. Even if this is not the case, the strong technical with $14tr of negative yielding bonds globally will likely absorb the increased supply. On the back of the weaker economic outlook and ongoing trade tensions JPM revised the house Fed call to include three more rate cuts this year, but we did not revise up our growth expectations. Aggressive central bank action is supporting financial markets even as the growth outlooks remain cloudy. Looking towards 2020 when US political uncertainty may rise further, this may not continue to work. However, for now with US growth still expected to hold in the 2% range, this dynamic remains supportive for credit. Credit DerivativesCDX.IG Series 33 will roll on September 20. We expect one name change in the upcoming roll. The fair value of the roll is 8bp and we expect the roll to trade marginally tighter than its fair value. This is in line with recent roll costs. CDX indices have traded in a narrow range despite the recent bump in volatility. LQD and CDX.IG spread performances have diverged further in recent weeks. We believe this has been driven by bond underperformance, especially in the long end. On the other hand, CDX.IG and S&P 500 performances converged partly with CDX.IG underperforming recently. However, CDX.IG continues to trade rich relative to equities. Option costs are elevated given the recent daily volatility while CDX indices have rallied. We discuss an options trade to enhance index carry while providing a buffer against a potential index selloff. Trade TrackerSince our last publication, our Trade Tracker is up $3,707. Over the last twelve months, performance is up by $1,074,699 (+6.7% ROI / +24.9% IRR).Chart of the week: HG bonds have returned 13.8% YTD. We expect another pickup of 0.7% until YE2019 to 14.5%, based on JPM’s recently revised UST yield forecastsSource: J.P. Morgan3.8%5.8%0.5%18.5%9.5%8.5%9.9%-0.8%7.8%0.4%6.0%6.4%-2.2%14.5%-5%0%5%10%15%20%2006200820102012201420162018HG Total Return2North America Credit Research05 September 2019Eric Beinstein(1-212) 834-4211eric.beinstein@jpmorgan.com Table of ContentsSummary and Outlook .............................................................3The High Grade Week Ahead................................................................................10Credit Derivatives .................................................................................................14Trade Tracker..........................................................................19High Grade Analytics .............................................................20Sector recommendations........................................................................................20JULI sector statistics and performance...................................................................23Credit Derivatives Analytics ..................................................24HG CDS-bond basis across buckets.......................................................................24Previous Featured Articles....................................................25US Economic Calendar..........................................................263North America Credit Research05 September 2019Eric Beinstein(1-212) 834-4211eric.beinstein@jpmorgan.com Summary and OutlookUS HG credit demonstrates resiliency despite the recent volatility and uncertainty in the market The HG bond market has traded in a stable range despite several negative developments which might have been expected to lead to spread weakness. These include heavy bond supply, low UST yields, a stronger USD and weakening economic data in both the US and abroad. This reflects the extremely strong technical position brought about by low yields globally. With German 10yr yields at -0.67% and about $14tr of glob...




发表评论取消回复