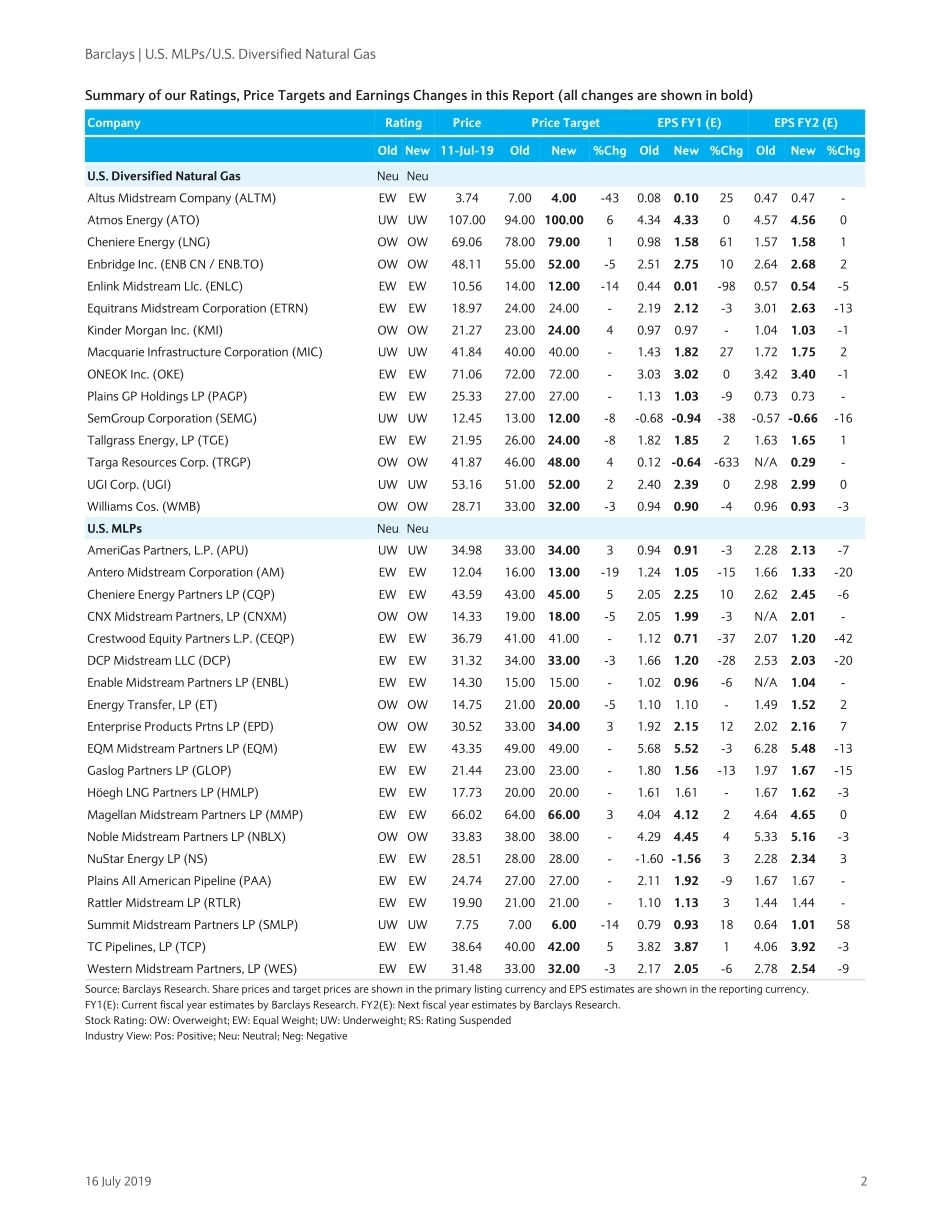
Equity Research 16 July 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 84. Restricted - Internal U.S. MLPs/U.S. Diversified Natural Gas 2Q19 Preview NGL prices will likely continue to be challenged: In the past 2 quarter previews, we had mentioned the risk to NGL prices moving lower as we believed we were approaching LPG export capacity and the inability of the marginal barrel to clear the market would put pressure on prices. While this constraint should be somewhat alleviated by the end of 3Q with some incremental capacity coming online, we remain cautious in light of lower naphtha prices, which have decoupled from Brent, and have the effect of flattening out the cost curve for feedstocks in crackers abroad. With IMO 2020 slated to go into effect in less than 6 months, one of the effects could be increased naphtha production, which would further exacerbate this issue. While there are a number of crackers scheduled to come online in the U.S. in the back half of this year, it’s worth noting that ethane has at times traded below the heating equivalent basis (possibly due to storage constraints?) and despite the low price ethane trades at, butane and propane have been more favorable feedstocks in recent months. With this as our backdrop, we have lowered our average 2019 NGL price from $0.61/gal to $0.52/gal, while the out years range in the $0.46/gal to $0.49/gal vs. our prior $0.61/gal-$0.73/gal forecast. Notable names where we differ from consensus: We expect EPD, ET, and ENB to beat consensus numbers, similar to last quarter, with the variance likely attributable to our expectation for continued robust results in each of the companies’ respective crude segments. While we aren’t forecasting a beat for PAA, we think our number could be conservative and wouldn’t be surprised to see them come in above our number with stronger-than-expected S&L results. Other notable beats are ENLC, which we attribute to continued Permian processing growth and favorable opportunistic processing dynamics in Louisiana and AM, which is tied to a continued ramp in higher margin treated water volumes and a return to more normal cost levels at the treatment facility as it gets full. Our 2Q number for LNG is below the Street as we estimate a modest uptick over prior quarter results with the puts and takes being higher volumes, but lower spot prices for the early cargoes tied to SPL 5 and CC 1. INDUSTRY UPDATE U.S. Diversified Natural Gas NEUTRAL Unchanged U.S. MLPs NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. Diversified Natural Gas Christine Cho, CFA +1 212 526 8419 christine.cho@barclays.com BCI, US Theresa Chen, CFA +1 212 526 7195 theresa.chen@barclays.com BCI, US Christopher Tillett, CFA +1 212 526 4823 christopher.tillett@barclays.com BCI, US Marc Solecitto +1 212 526 9581 marc.solecitto@barclays.com BCI, US Heather Gornik +1 212 526 9237 heather.gornik@barclays.com BCI, US U.S. MLPs Christine Cho, CFA +1 212 526 8419 christine.cho@barclays.com BCI, US Theresa Chen, CFA +1 212 526 7195 theresa.chen@barclays.com BCI, US Barclays | U.S. MLPs/U.S. Diversified Natural Gas 16 July 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 11-Jul-19 Old New %Chg Old New %Chg Old New %Chg U.S. Diversified Natural Gas Neu Neu Altus Midstream Company (ALTM) EW EW 3.74 7.00 4.00 -43 0.08 0.10 25 0.47 0.47 - Atmos Energy (ATO) UW UW 107.00 94.00 100.00 6 4.34 4.33 0 4.57 4.56 0 Cheniere Energy (LNG) OW OW 69.06 78.00 79.00 1 0.98 1.58 61 1.57 1.58 1 Enbridge Inc. (ENB CN / ENB.TO) OW OW 48.11 55.00 52.00 -5 2.51 2.75 10 2.64 2.68 2 Enlink Midstream Llc. (ENLC) EW EW 10.56 14.00 12.00 -14 0.44 0.01 -98 0.57 0.54 -5 Equitrans Midstream Corporation (ETRN) EW EW 18.97 24.00 24.00 - 2.19 2.12 -3 3.01 2.63 -13 Kinder Morgan Inc. (KMI) OW OW 21.27 23.00 24.00 4 0.97 0.97 - 1.04 1.03 -1 Macquarie Infrastructure Corporation (MIC) UW UW 41.84 40.00 40.00 - 1.43 1.82 27 1.72 1.75 2 ONEOK Inc. (OKE) EW EW 71.06 72.00 72.00 - 3.03 3.02 0 3.42 3.40 -1 Plains GP Holdings LP (PAGP) EW EW 25.33 27.00 27.00 - 1.13 1.03 -9 0.73 0.73 - SemGroup Corporation (SEMG) UW UW 12.45 13.00 12.00 -8 -0.68 -0.94 -38 -0.57 -0.66 -16 Tallgrass Energy, LP (TGE) EW EW 21.95 26.00 24.00 -8 1.82 1.85 2 1.63 1.65 1 Targa Resources Corp. (TRGP) OW OW 41.87 46.00 48.00 4 0.12 -0.64 -633 N/A 0.29 - UGI Corp. (UGI) UW UW 53.16 51.00 52.00 2 2.40 2.39 0 2.98 2.99 0 Williams Cos. (...




发表评论取消回复