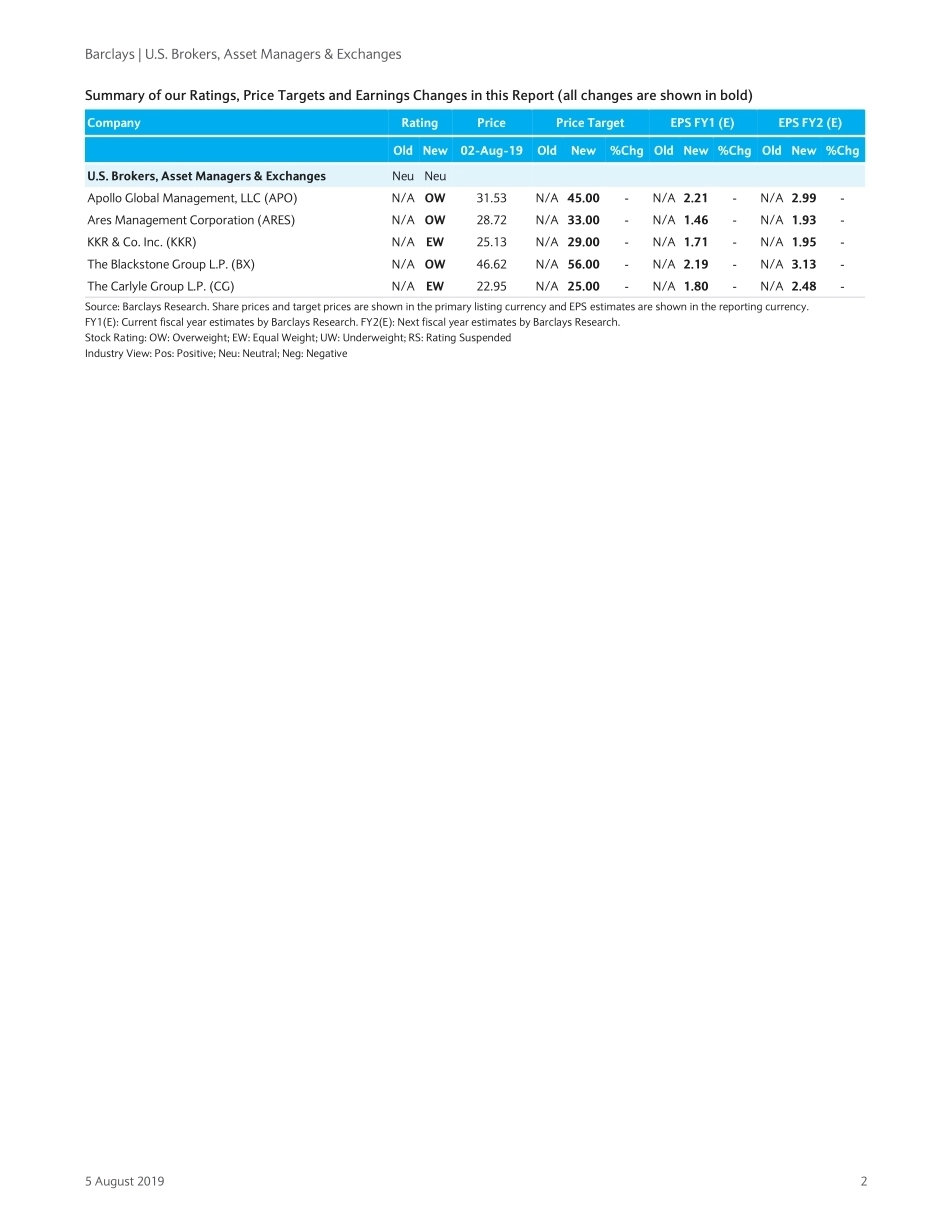
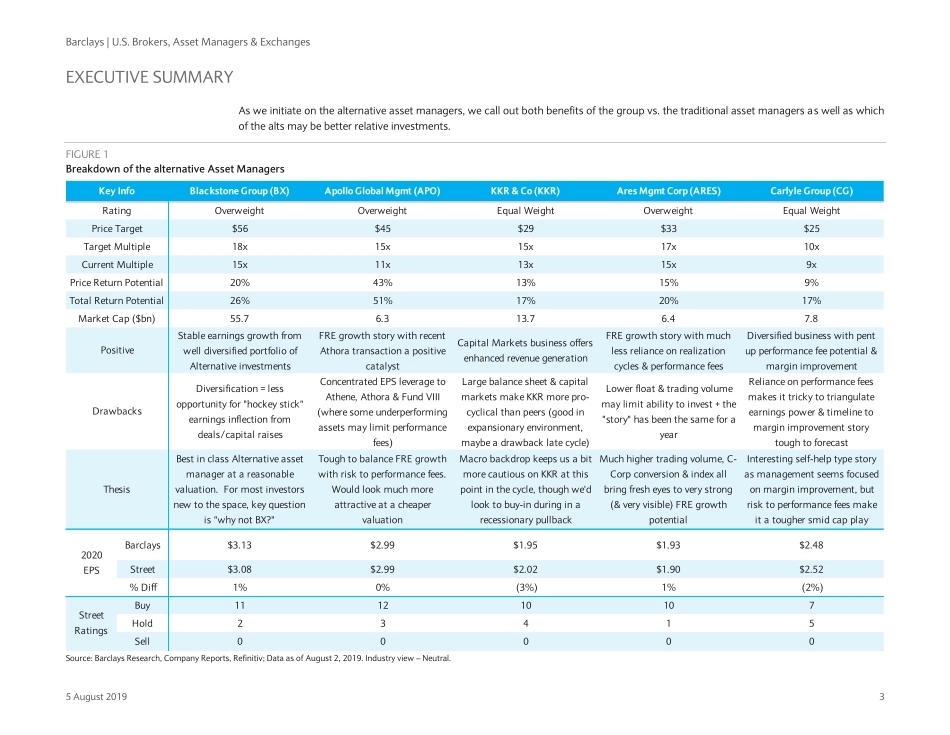
Equity Research 5 August 2019 CORE Barclays Capital Inc. and/or one of its affiliates does and seeks to do business with companies covered in its research reports. As a result, investors should be aware that the firm may have a conflict of interest that could affect the objectivity of this report. Investors should consider this report as only a single factor in making their investment decision. PLEASE SEE ANALYST CERTIFICATION(S) AND IMPORTANT DISCLOSURES BEGINNING ON PAGE 56. Restricted - Internal U.S. Brokers, Asset Managers & Exchanges Looking for an Alternative: Initiating on BX, KKR, APO, CG, and ARES Alternative investment strategies have a structural growth story… Counter to active asset management, there is continued demand for alternatives as an asset class, even after years of expansion. From 2008 through 2017, alternative investment AUM grew at a 12% CAGR and the Preqin data suggests another 8% CAGR through 2023 with many institutional investors looking to increase allocation to alts, including 65% of family offices & 40%-50% of pensions, endowments, & sovereign wealth fund. …as ability to wait & deploy dry powder accretive has yielded outperformance. Alts as a whole are sitting on $2 trillion of dry powder just waiting to deploy when market opportunities arise. The ability to put money to work when they find the right opportunities (not just because they have to) and hold investments through a cycle (instead of selling due to an outflow) helps generate higher IRRs and makes them more attractive vs. the traditional asset managers. Alts earnings streams are more stable than you might think... Alternative managers earn fee revenue on stable committed or invested capital—not AUM like the traditional asset managers—and then generate performance revenue when big assets are sold (in PE) or borrowers continue to make payments (private credit). Unlike traditionals, there’s a stable floor of fee revenue on locked-up capital with just as much (if not more) upside in a bull market from higher realizations & fundraising. …but as stocks, have a high beta. Alternative asset manager stocks have historically traded relatively in tandem with the traditional asset manager stocks, despite a much stickier earnings stream, generating a larger beta than the beta of the businesses. To broaden ownership, all have (or will) converted to C-Corps from LPs, so we see greater potential for stability and higher valuations than in the past. Overweight BX, APO, and ARES; Equal Weight KKR & CG: Figure 1 is a one-page guide to the alts, but we see BX as the best in class & most diversified asset manager of the bunch with sustainable earnings growth & investor demand for the stock. ARES mainly generates fee revenue on invested capital vs. committed capital at the PE shops, we see a pretty clear runway for earnings growth agnostic of the fundraising market. APO has the most upside to our target but it’s a riskier story than the other two. KKR has a unique strategy relative to the peers, but we see it as a bit more pro-cyclical so would be a little cautious here late cycle. CG is a self-help margin improvement story where we see longer-term upside but stay on the sidelines for now. Valuation a bit in flux: Since all the Alts are moving/have moved to C-Corps, historical valuation metrics aren’t terribly useful. While a sum-of-the-parts analysis can be useful (Figure 15), we’ve elected for a more simplistic P/E approach with BX setting the bar at a market multiple with the rest anchored lower from there (Figure 14). INITIATING COVERAGE U.S. Brokers, Asset Managers & Exchanges NEUTRAL Unchanged For a full list of our ratings, price target and earnings changes in this report, please see table on page 2. U.S. Brokers, Asset Managers & Exchanges Jeremy Campbell, CFA +1 212 526 9750 jeremy.campbell@barclays.com BCI, US Francesca Kruk +1 212 526 3856 francesca.kruk@barclays.com BCI, US Jason Weber + 1 212 526 9406 jason.weber@barclays.com BCI, US Ben Jackson +1 212 526-3006 Ben.Jackson@barclays.com BCI, US Barclays | U.S. Brokers, Asset Managers & Exchanges 5 August 2019 2 Summary of our Ratings, Price Targets and Earnings Changes in this Report (all changes are shown in bold) Company Rating Price Price Target EPS FY1 (E) EPS FY2 (E) Old New 02-Aug-19 Old New %Chg Old New %Chg Old New %Chg U.S. Brokers, Asset Managers & Exchanges Neu Neu Apollo Global Management, LLC (APO) N/A OW 31.53 N/A 45.00 - N/A 2.21 - N/A 2.99 - Ares Management Corporation (ARES) N/A OW 28.72 N/A 33.00 - N/A 1.46 - N/A 1.93 - KKR & Co. Inc. (KKR) N/A EW 25.13 N/A 29.00 - N/A 1.71 - N/A 1.95 - The Blackstone Group L.P. (BX) N/A OW 46.62 N/A 56.00 - N/A 2.19 - N/A 3.13 - The Carlyle Group L.P. (CG) N/A EW 22.95 N/A 25.00 - N/A 1.80 - N/A 2.48 - Source: Barclays Research. Share prices and target prices are shown in the primary listing currency and EPS estimates are shown in the reporting currency. FY1(E): Current fiscal year estimates by Barclays Research. FY2(E): Next ...




发表评论取消回复